Why So Many Sellers Are Cutting Their Price Right Now

Why So Many Sellers Are Cutting Their Price Right Now
Why So Many Sellers Are Cutting Their Price Right Now Simplifying The Market

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.

Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.

This is what’s actually driving all those price cuts, and why it matters no matter which side of the deal you’re on.

42% of Homes for Sale Are Now Carrying a Price Cut

According to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):
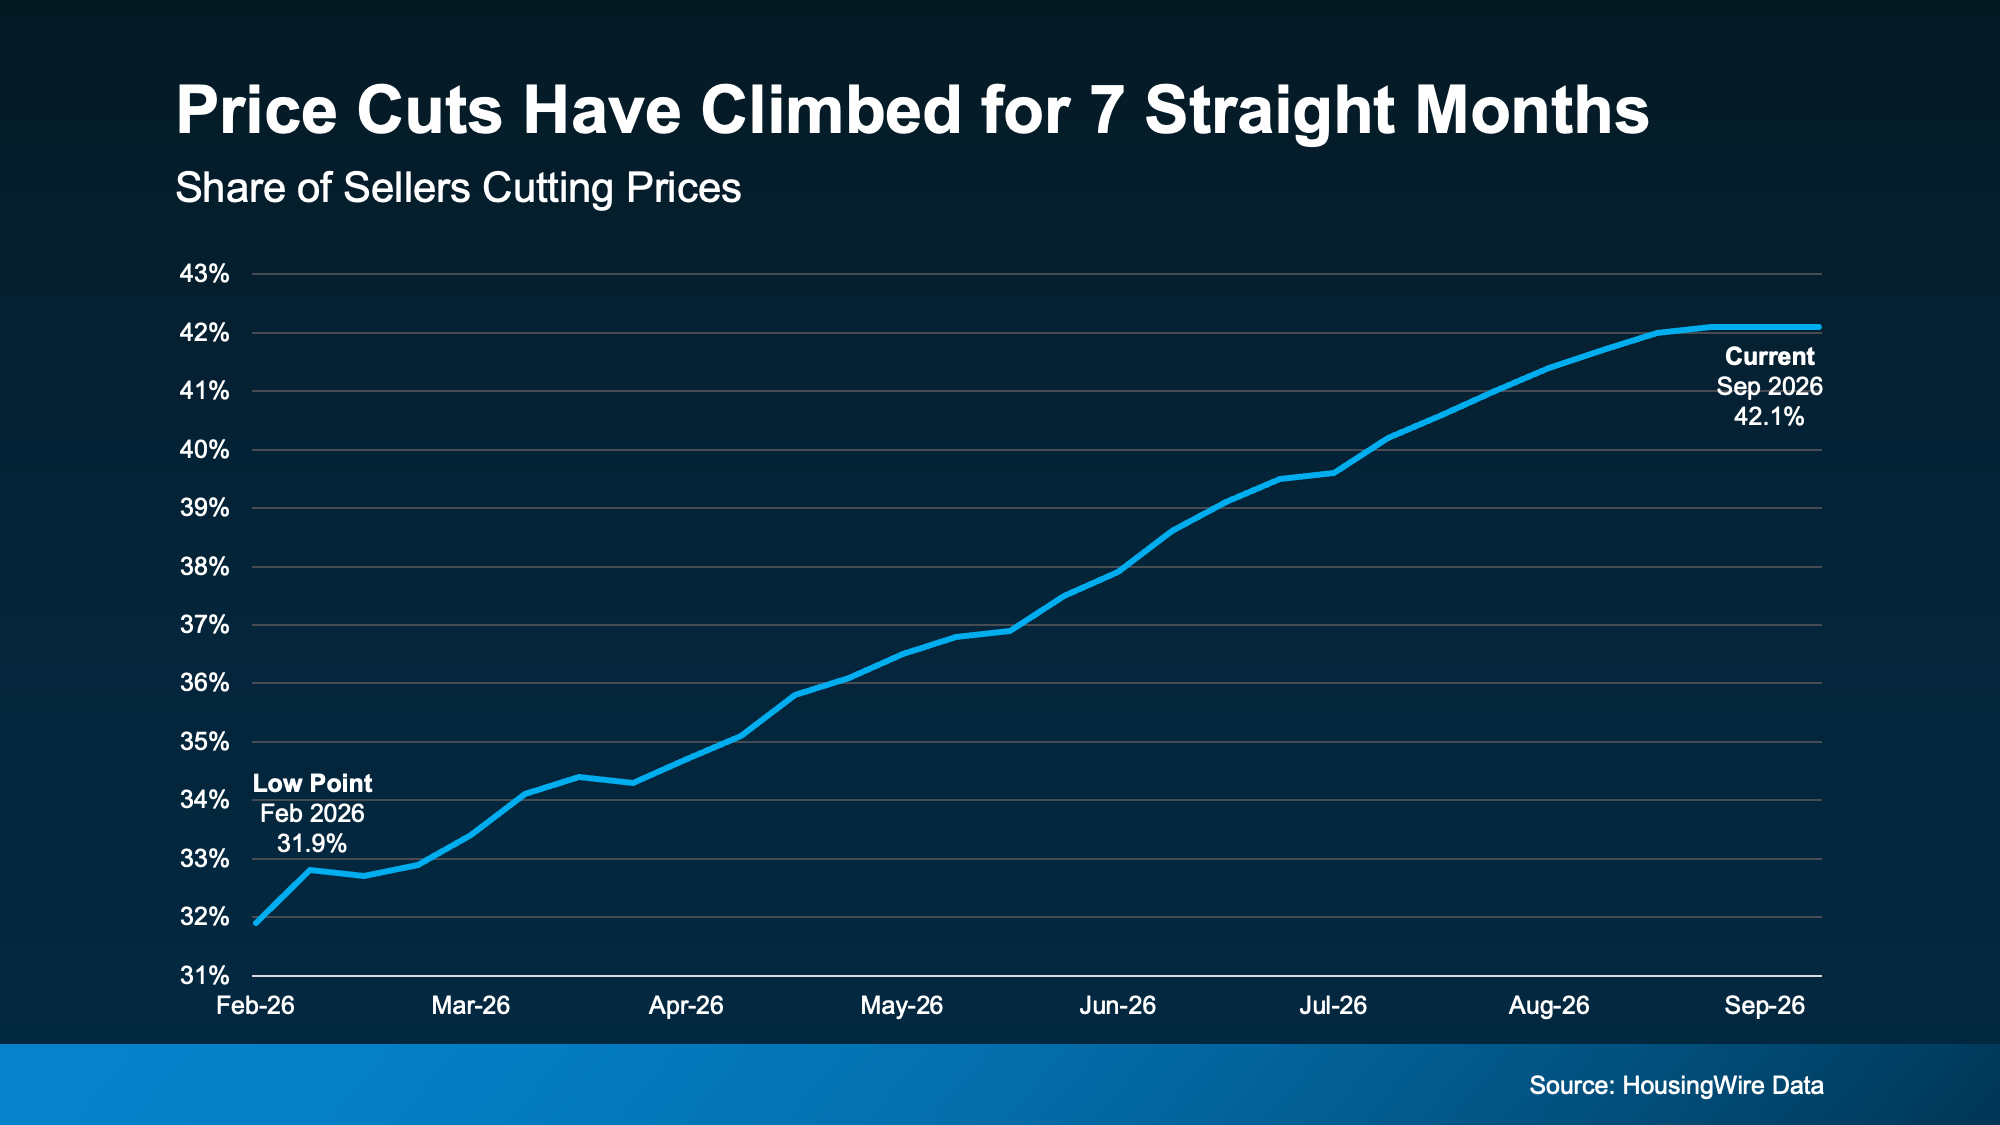
a graph showing the growth of a straight month 

Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. 

Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.

What does that mean for you?

  • If you’re selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market’s been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.

  • If you’re buying, it’s easy to assume a price cut means something’s wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that’s exactly the kind of opening you need to get a better deal.

Why Sellers Are Adjusting Faster than Before

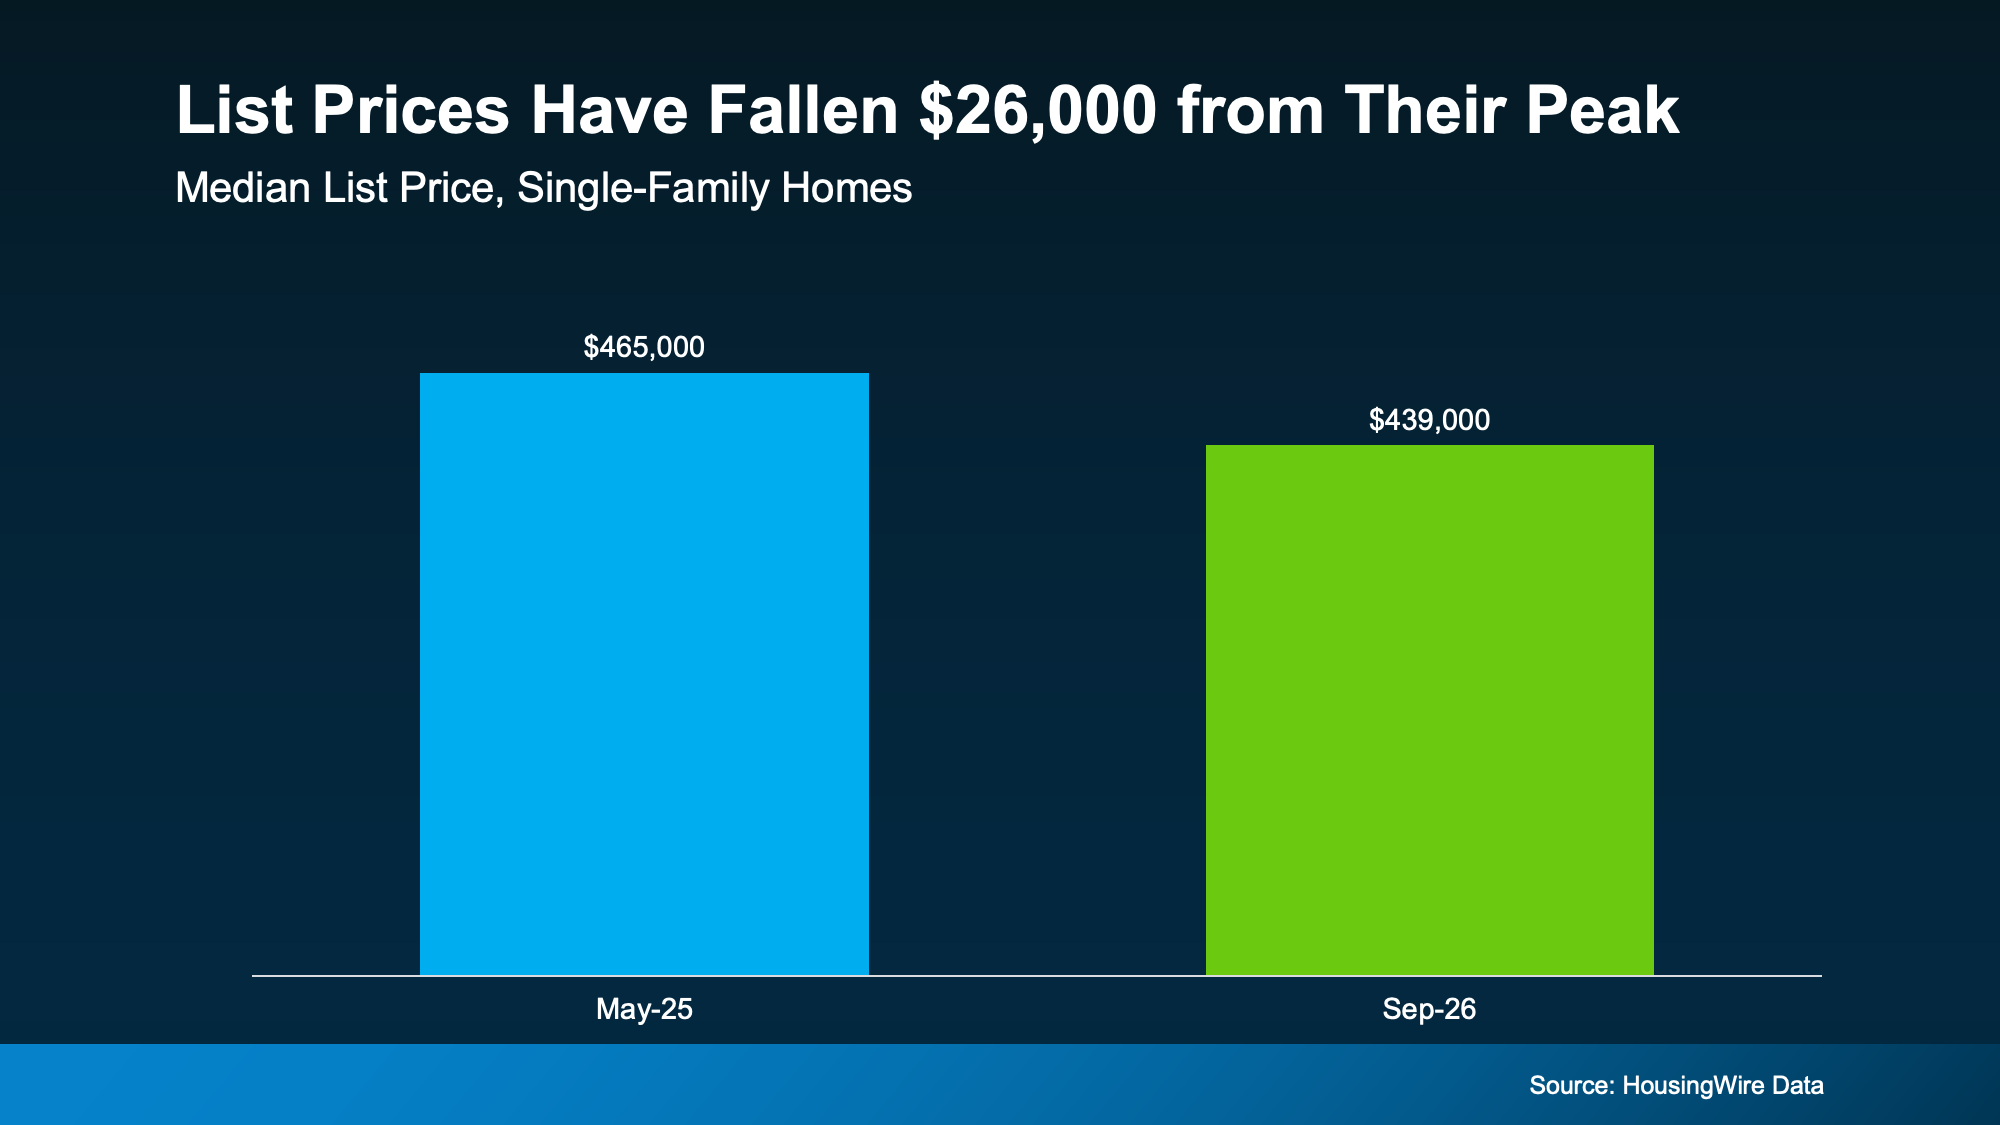
HousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year’s peak.

Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below):
a graph of a number of people 

Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.

Buyers, You’ve Got Room To Negotiate Again

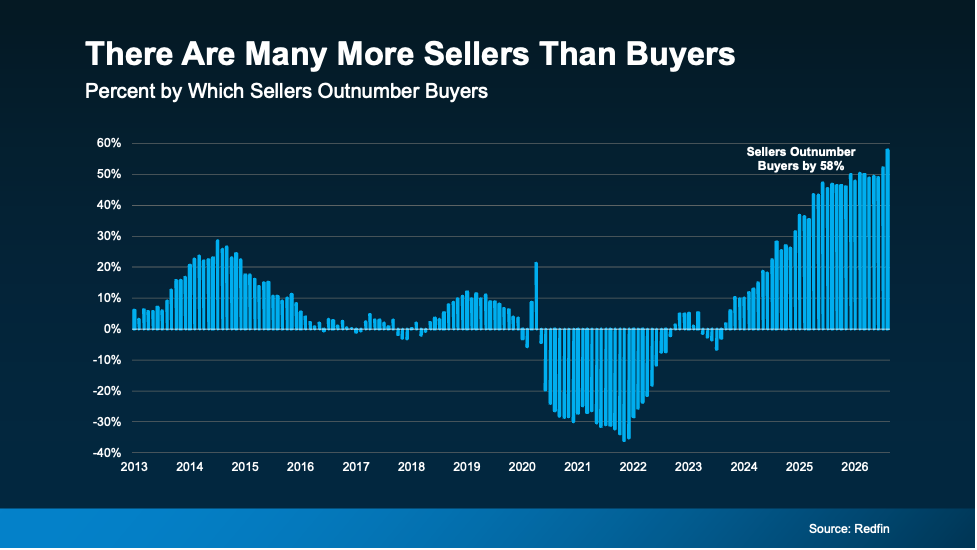
At the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below):
a graph of sales 

That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.

  • For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.

  • For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.

Bottom Line

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Connect with a local real estate agent to look at what’s actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.
There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In? Simplifying The Market

Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell. Which type you’re in changes how you should buy or sell. Ryan Serhant, CEO of SERHANT agrees:

“There is no longer a housing market . . . There are four Americas.”

Here’s what each looks like, and what it means for you.

Cash Buyers: 1 in 4 Buyers Are Paying with Cash

If you already own a home, you may be able to buy your next place in cash thanks to your equity. In fact, 26% of existing home sales this summer were all-cash, according to the National Association of Realtors (NAR). That’s roughly 1 in 4 buyers skipping a home loan entirely.

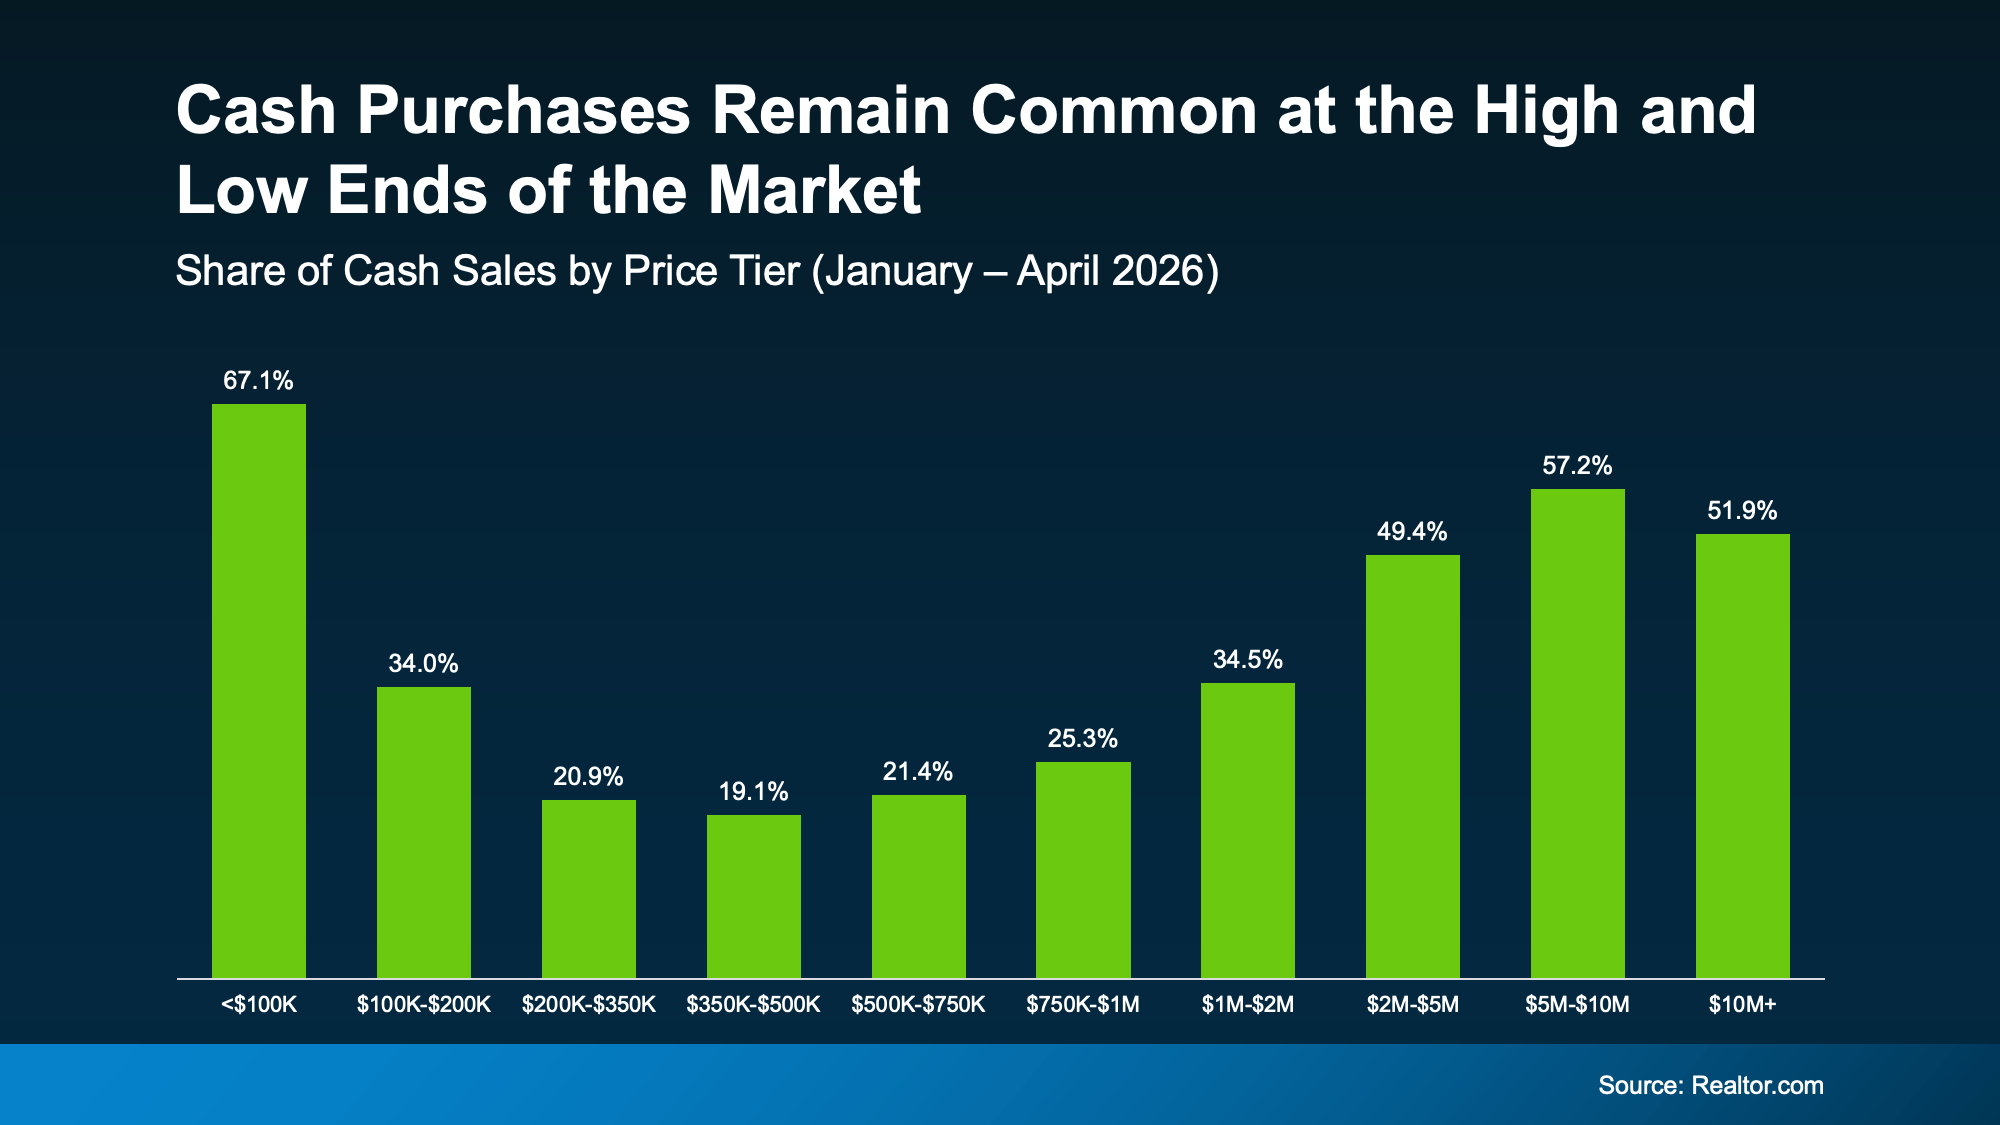
Data from Realtor.com shows most are at the very top and very bottom of the market by price point (see graph below):

a graph of green bars

For Buyers: If you’re able to buy in cash too, having no financing contingency means your offer is going to look really appealing to sellers. You may get a faster close and more room to negotiate.

For Sellers: A cash offer can mean less risk of the deal falling through, but that certainty sometimes comes with a lower number attached. Compare the whole picture before deciding it’s automatically your best offer.

Buyers Using Financing: They’re Not Getting Help from Rates, But They Are from Sellers

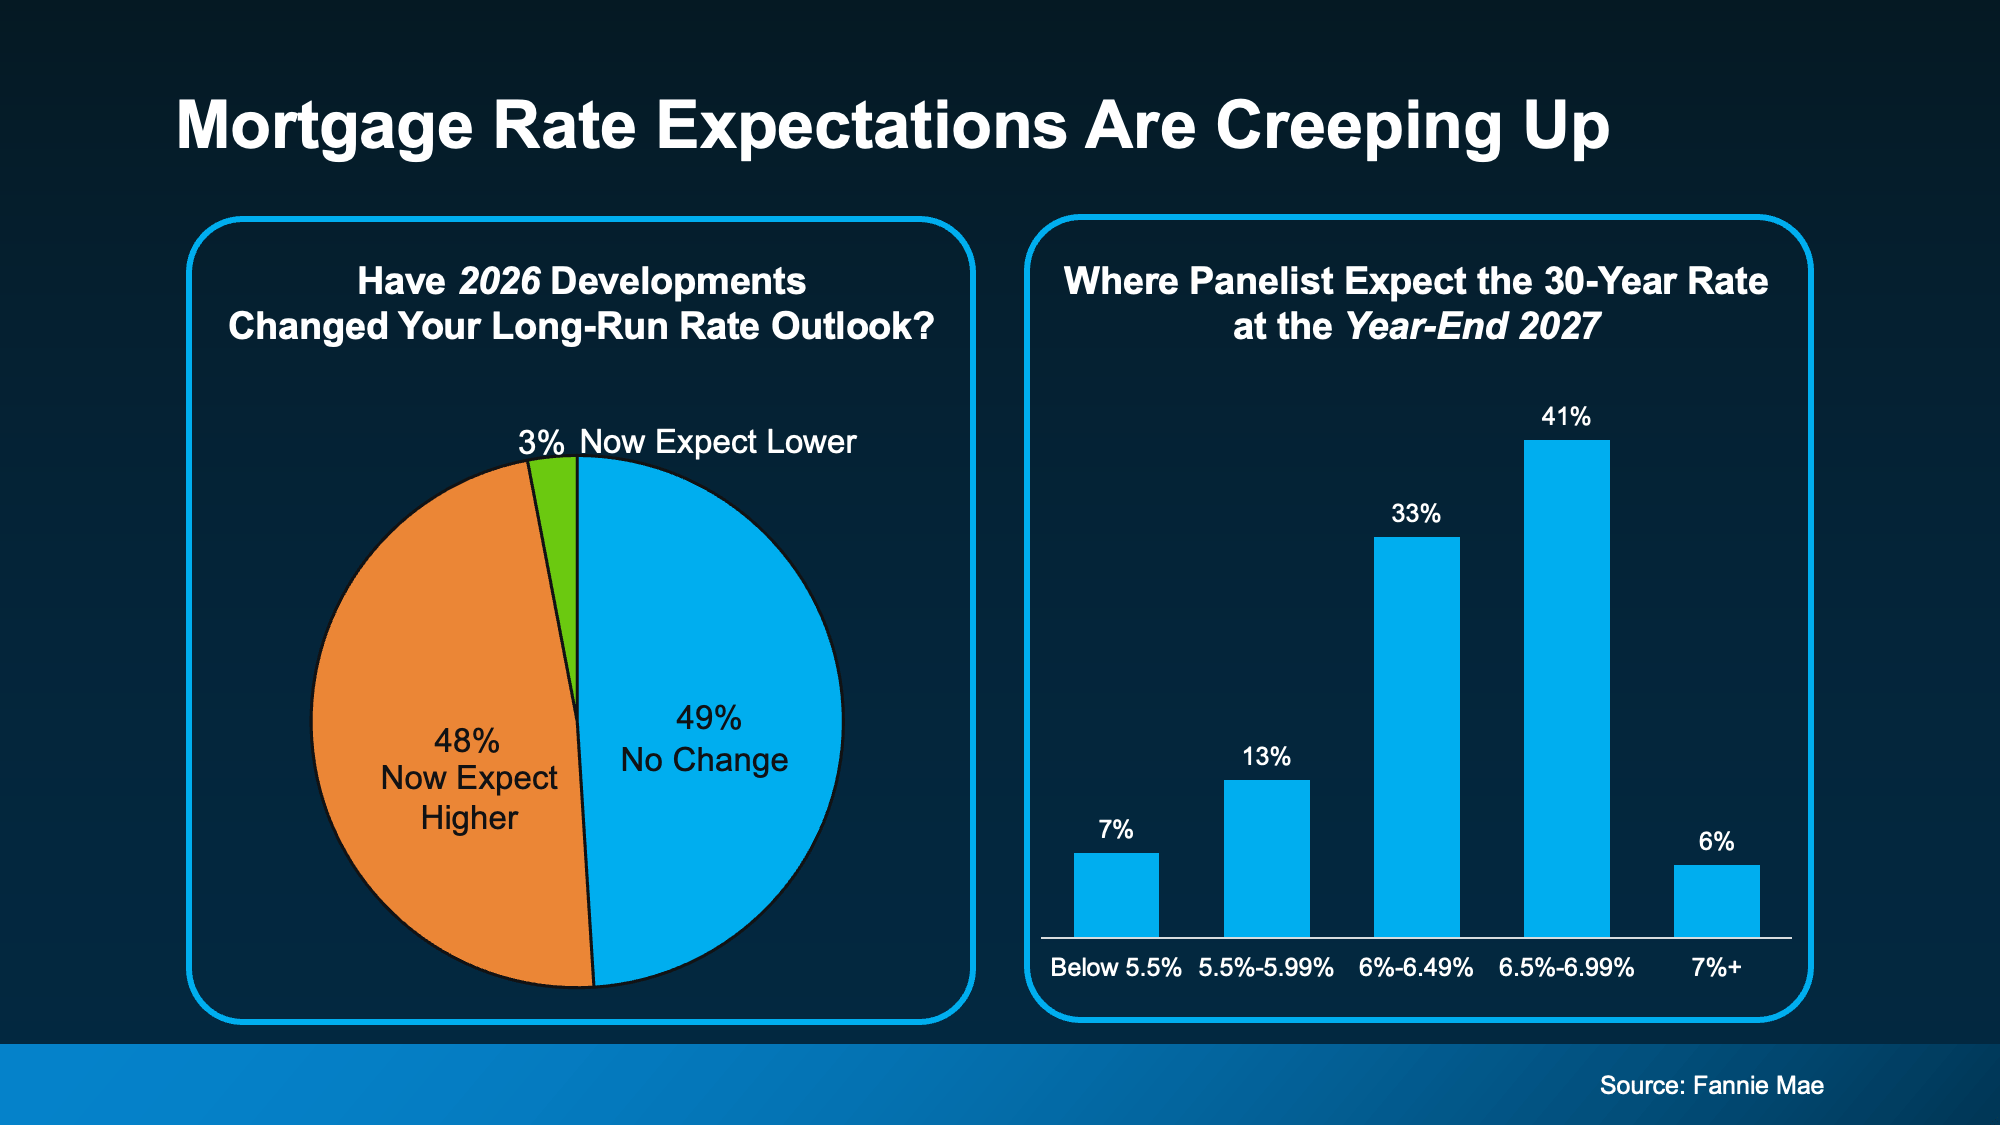
If you’re looking to take out a mortgage, you should know mortgage rates aren’t likely to come down anytime soon. Data from Fannie Mae shows nearly half of experts actually raised their long-term rate forecast this year (see graphs below):

a graph of growth and growth

That’s tough for homebuyers relying on a mortgage, especially first-time buyers. But it’s not all bad news.

While buyers may not be getting the lower rates they want, at least there’s help to be had if you ask sellers for what you really need. Redfin data shows almost half of May sales included a concession like a rate buydown or closing-cost credit from the homeowner.

For Buyers: Stop waiting on rates to drop. Negotiate the concession instead. If the payment works today, that’s your signal.

For Sellers: Expect to negotiate. Build a concession into your pricing strategy from the start could be the thing that gets a deal done.

Rate-Locked Homeowners: Most Are Sitting on a Rate Below 5%

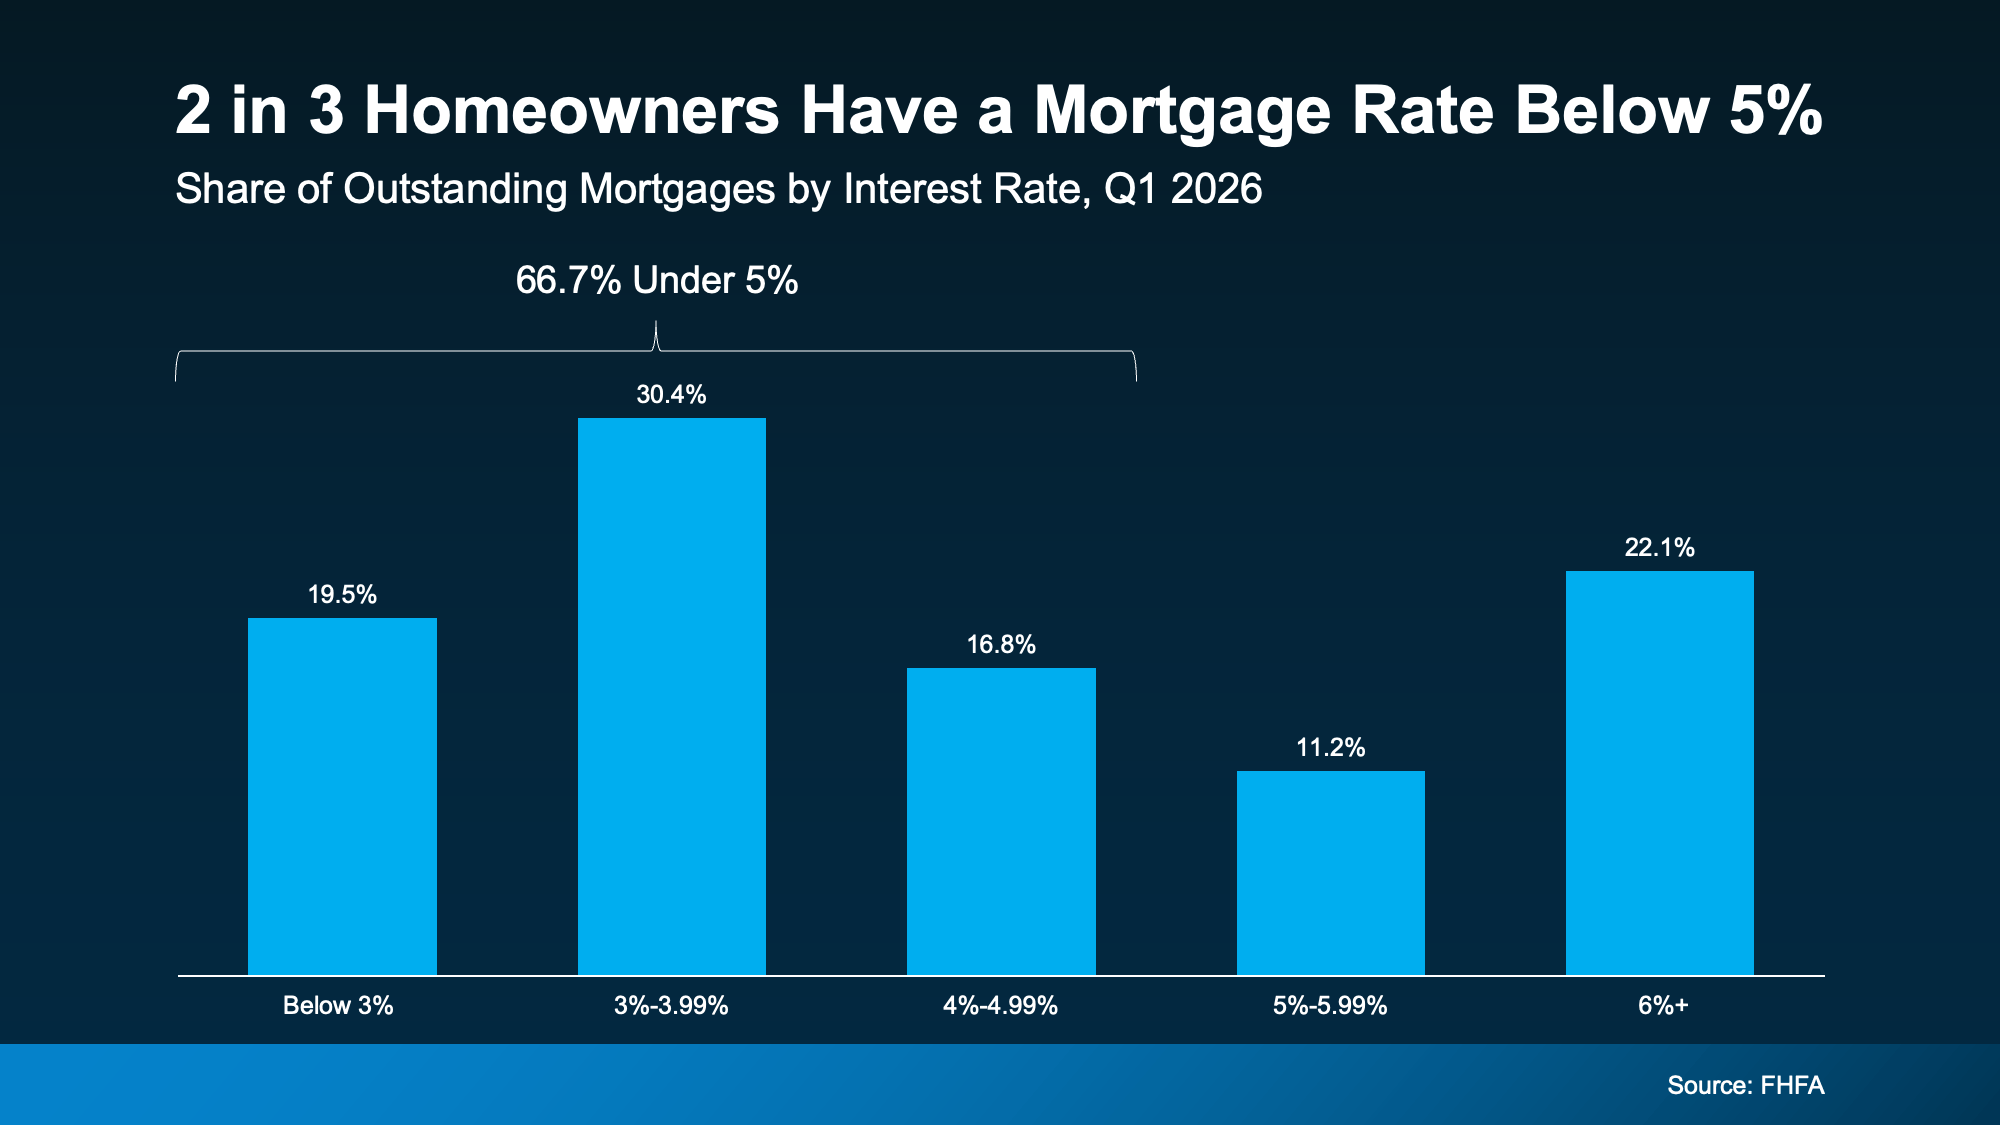
If you own a home already, you might not want to move and take on a higher rate than the one you’ve got. That’s the case for a lot of people. About 2 in 3 homeowners have a mortgage rate under 5%, according to Federal Housing Finance Agency (FHFA) data (see graph below).

When a homeowner has a rate that low, it’s harder for them to want to move and leave behind that ultra-low rate. Because, they’d likely have to take on a higher one on their next home. Hence “rate locked” – they feel locked in.

a graph of a graph with text

And, according to Fannie Mae data, most experts think that lock-in will stick around another 3-5 years. That means this will continue to be a factor in how many homes come up for sale.

For Buyers: Fewer homeowners are listing, but the ones who do usually have a real reason to move. They’re often more flexible, motivated sellers.

For Sellers: Run the math on what your equity actually buys before ruling out a move. Got an FHA or VA loan? Ask about making it assumable. It’s rare, but it’s a real selling point.

Homebuilders: They’re Negotiating More Than You Think

If you’re looking at new construction, this might be your moment. According to the latest Census data, builders have more unsold new homes sitting around than usual, enough that it would take nearly 10 months to sell them all at the current pace (well above the normal 4-6 months pace). That’s pushing builders toward price cuts and rate buydowns.

For Buyers: That’s where the deals are right now. Just be sure to use your own agent and compare the whole incentive package, not only the price tag.

For Sellers: Lead with what a builder can’t offer – mature landscaping, an established neighborhood, and a house that’s ready today, not in 8 months. That can help your house seem like a better optiona

Bottom Line

Four different housing markets are running at once: cash buyers, financed buyers, locked-in owners, and builders. Each one plays by its own rules, and the right move for one is exactly the wrong move for another.

Connect with a local real estate agent to figure out which one you’re actually in and build your next move from there.

3 Things You Can Actually Control About Your Mortgage Rate Right Now

3 Things You Can Actually Control About Your Mortgage Rate Right Now

3 Things You Can Actually Control About Your Mortgage Rate Right Now Simplifying The Market

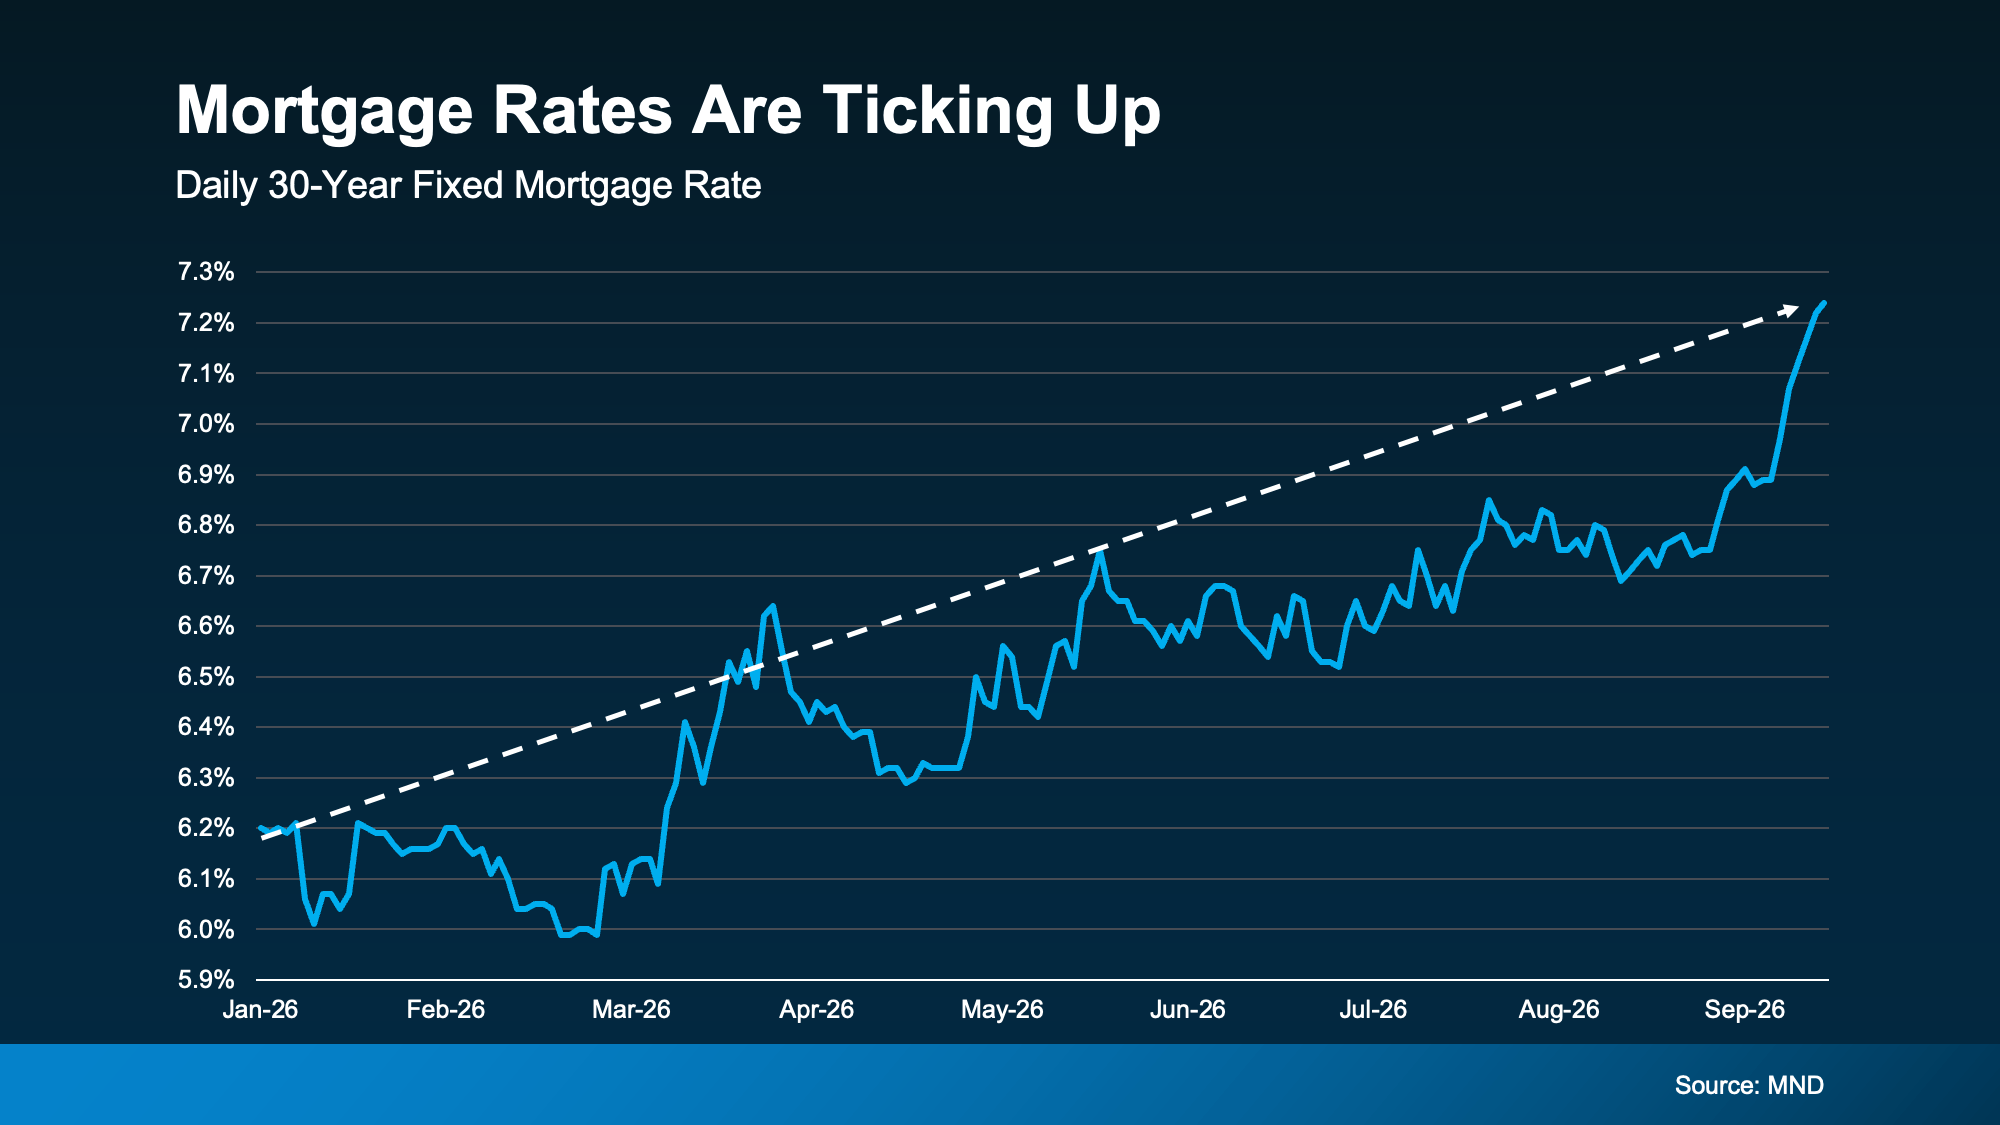
If you’re trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and wait for them to go down.

For now, though, they’re headed the other way. Mortgage News Daily data shows how rates have risen this year (see graph below):

a graph of a moving rate

And if you’re wondering why? There are actually a number of reasons. 

Mortgage rates are impacted by the situation overseas, economic data, inflation numbers, oil prices, and even decisions from the Federal Reserve (who recently decided to hike their Fed Funds Rate – which often affects mortgage rates too). As Danielle Hale, Chief Economist at Realtor.com, explains:

“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”

Now, that’s probably not what you wanted to hear. But, it doesn’t mean there’s nothing you can do. While you can’t control where rates go from here, you absolutely can control several things that shape the rate you actually get. 

So where should you focus? Let’s walk through it.

Work on Your Credit Score

Your credit score plays a big role in the rate you qualify for, and even a small improvement can make a real difference in your monthly payment. As Freddie Mac puts it:

“Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate.“

So, make sure you do what you can to keep your credit score up. If you’re not sure where your score stands right now, or how to improve it, talk to a trusted loan officer.

Explore Your Loan Options

The type and term of your loan both affect your rate. Conventional, FHA, VA, and USDA loans each come with their own requirements and rates, and your term (15, 20, or 30 years) changes both your payment and the total interest you’ll pay. The structure matters, too. A fixed-rate loan holds the same rate over time, while an adjustable-rate loan usually starts lower and can move later on. Bankrate explains it this way:

“. . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk.“

It’s important to explore your options with a lender to see what makes the most sense for you. Just be sure to balance your goals, your possible rate, and any potential tradeoffs before making any decision. You may even want to talk to multiple lenders to see how the options vary. 

Consider a Newly Built Home

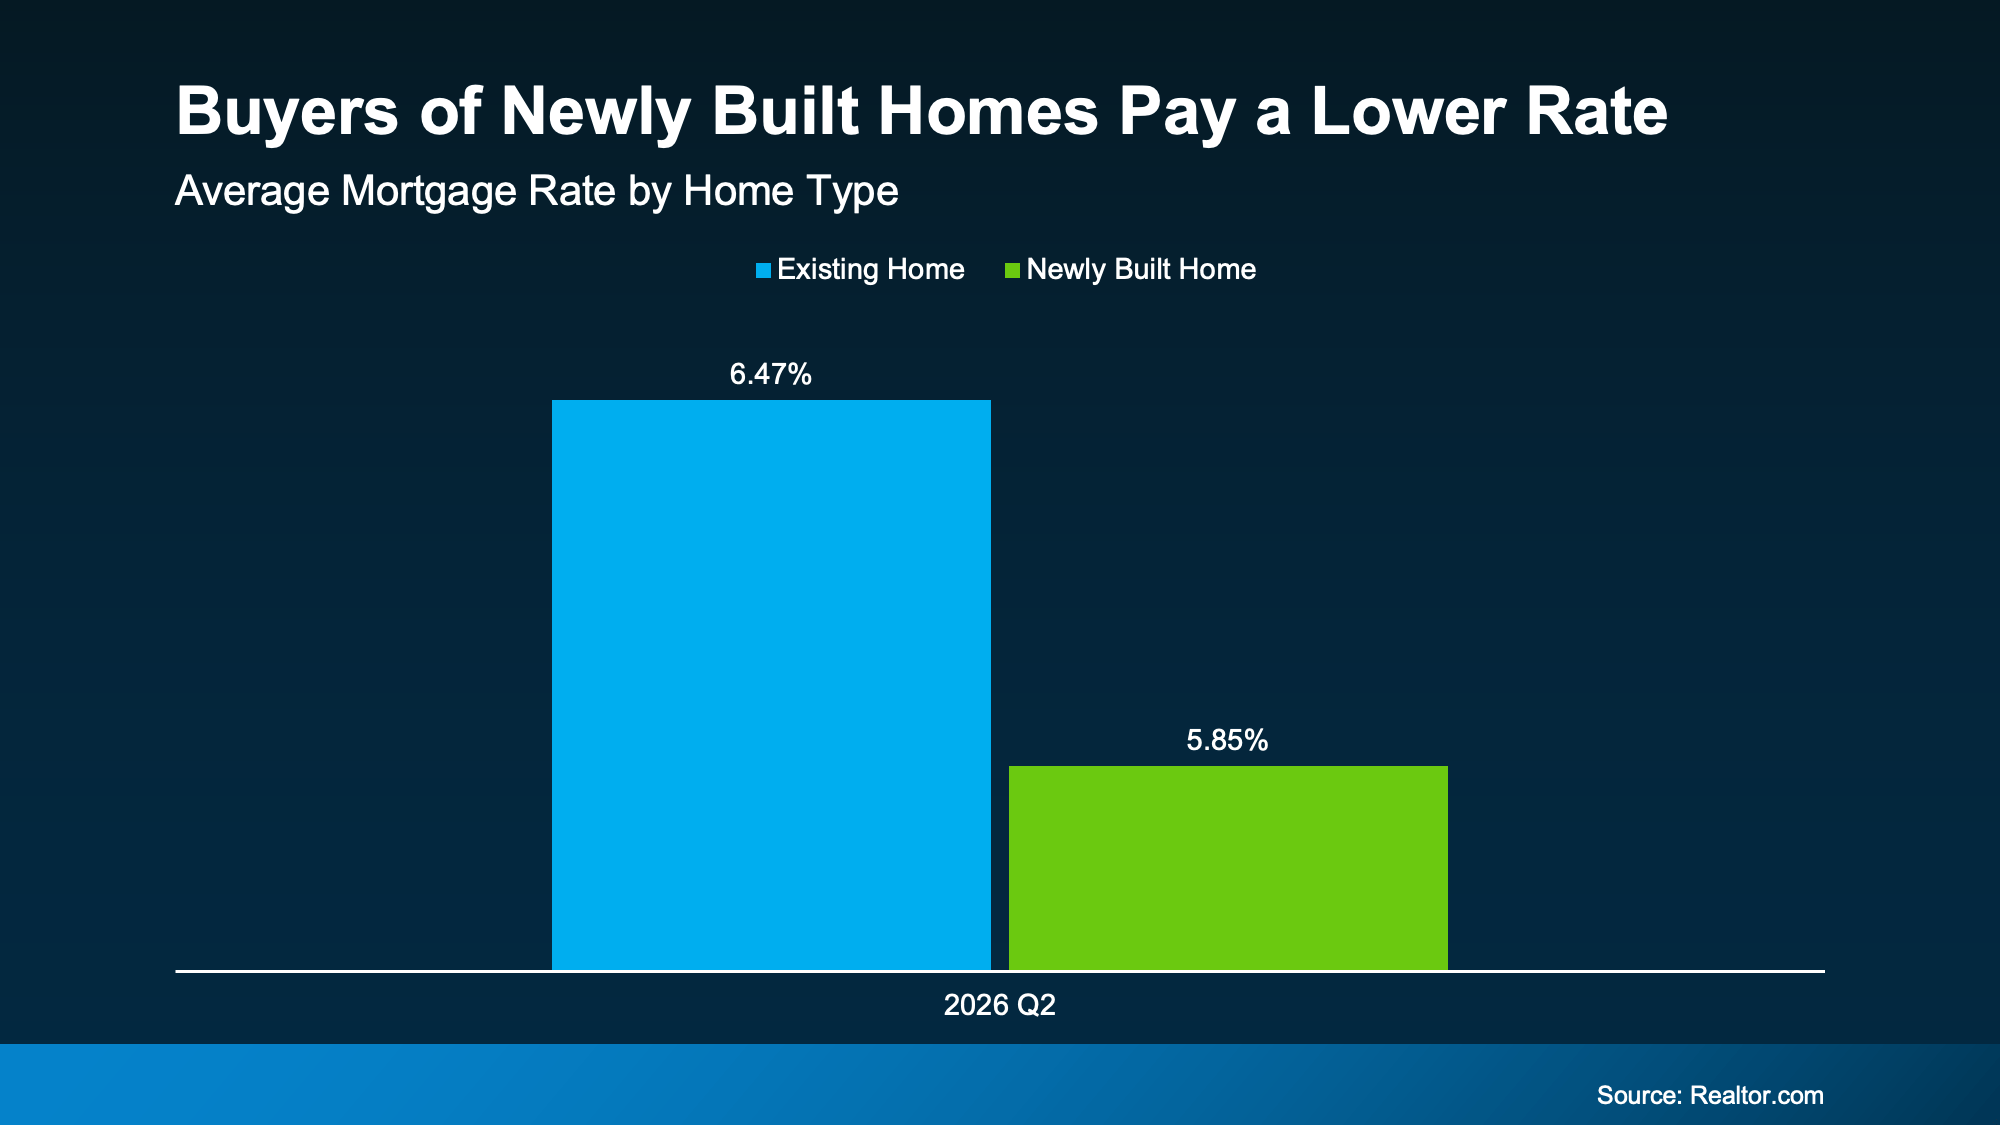
Another path to a lower rate comes down to the kind of home you buy. Many builders are buying down mortgage rates, which lowers your monthly payment. It’s just one way they’re trying to attract buyers and get their homes sold.

According to Realtor.com, buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes (see graph below):

a graph of a graph showing a number of houses

If a lower rate is your goal, it may be worth asking your agent to show you some new build communities that are offering this type of incentive locally.

Bottom Line

You can’t control where mortgage rates go, but you can control your credit, your loan, and the kind of home you buy. Working with a trusted lender can help you lock in the best rate you qualify for. And when you’re ready to make a move that fits your budget, connect with a local real estate agent.

Selling This Fall? You Want To Get These 4 Things Right.

Selling This Fall? You Want To Get These 4 Things Right.

Selling This Fall? You Want To Get These 4 Things Right. Simplifying The Market

Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year. 

Buyer activity typically starts to slow while the number of homes for sale climb – and you need the right strategy to get attention in this type of market.

The good news? There’s a lot you can control.

From how you price and present your house to how you negotiate and respond to feedback. Here are four things you’ll want to get right this fall. 

#1: Price To Get Buyers’ Attention

In the fall, there are typically fewer buyers looking and more homes for them to choose from. So, you want to make the most of every buyer who comes across your house.

And your price is one of the first things that can make them stop and take a closer look – or keep scrolling. 

That’s why this isn’t the time to start high “just to see what happens.”

If buyers think your house is overpriced, they have plenty of other options to move on to. And that could leave you sitting and waiting.

So, if you want to sell before year-end, work with your agent to find the right price for your house and today’s market. That may mean listing at market value – or even slightly below it – to grab buyers’ attention.

Redfin explains how a seemingly small difference can change your buyer pool: 

“Buyers often search in round-number price brackets, so pricing at $499,000 instead of $505,000 can make your home appear in more searches and feel like a better deal.” 

#2: Make a Great First Impression

When buyers had very few homes to choose from, they were often more willing to overlook dated finishes or a house that needed some work. That’s harder to count on now.

With more choices, how your house looks online and in person can determine whether it makes a buyer’s shortlist at all.

That doesn’t mean you need a full renovation before you sell, but you should take care of essential repairs, do what you can to boost curb appeal, and make sure your house photographs well. Maybe that’s some light staging, maybe it’s swapping out faucets or lights, or maybe a fresh coat of paint. Small details can help a lot.

After all, you only get one chance to make that first impression. Make it count.

#3: Stay Open To Negotiating

Some sellers are still expecting the kind of leverage they had a few years ago. But in many markets, buyers have more negotiating power today and there’s a lot more give and take.

The latest data from Redfin shows 46.2% of sellers gave buyers some type of concession. So, consider throwing in a little help with closing costs or covering a repair. Almost half of sellers are.

The takeaway? Playing hard ball may not get you what you want. But being flexible might. The key is not getting so focused on “winning” every individual negotiation that you lose sight of the bigger goal: making your move happen.

Sometimes a small concession is what gets you to the closing table.

#4: Know When It’s Time To Adjust

Sometimes your house tells you when something isn’t working. Maybe you’re getting plenty of online views but very few showings. Or buyers are coming through, but you’re not getting offers. Or maybe buyer feedback has one recurring theme.

Pay attention to those signals. They can help you figure out what needs to change.

Let’s say your price is the most common point of feedback. Talk to your agent about a price drop. It doesn’t have to be a big change to make a big difference. The average price cut right now is 4% according to HousingWire Data. That’s normal.

Now, that doesn’t mean you should panic and slash your price after a week. It means you and your agent should pay attention to what buyers are telling you and adjust if you need to.

Sometimes the smartest move isn’t waiting for the right buyer. It’s making sure you’re giving that buyer a reason to act.

Bottom Line

Selling this fall is absolutely doable. And now you know four of the biggest things to get right.

If you want to sell before the end of the year, connect with a local agent to make sure you have the right strategy from day one.

The Best Time To Buy a Home in 2026 Is Almost Here

The Best Time To Buy a Home in 2026 Is Almost Here

The Best Time To Buy a Home in 2026 Is Almost Here Simplifying The Market

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.

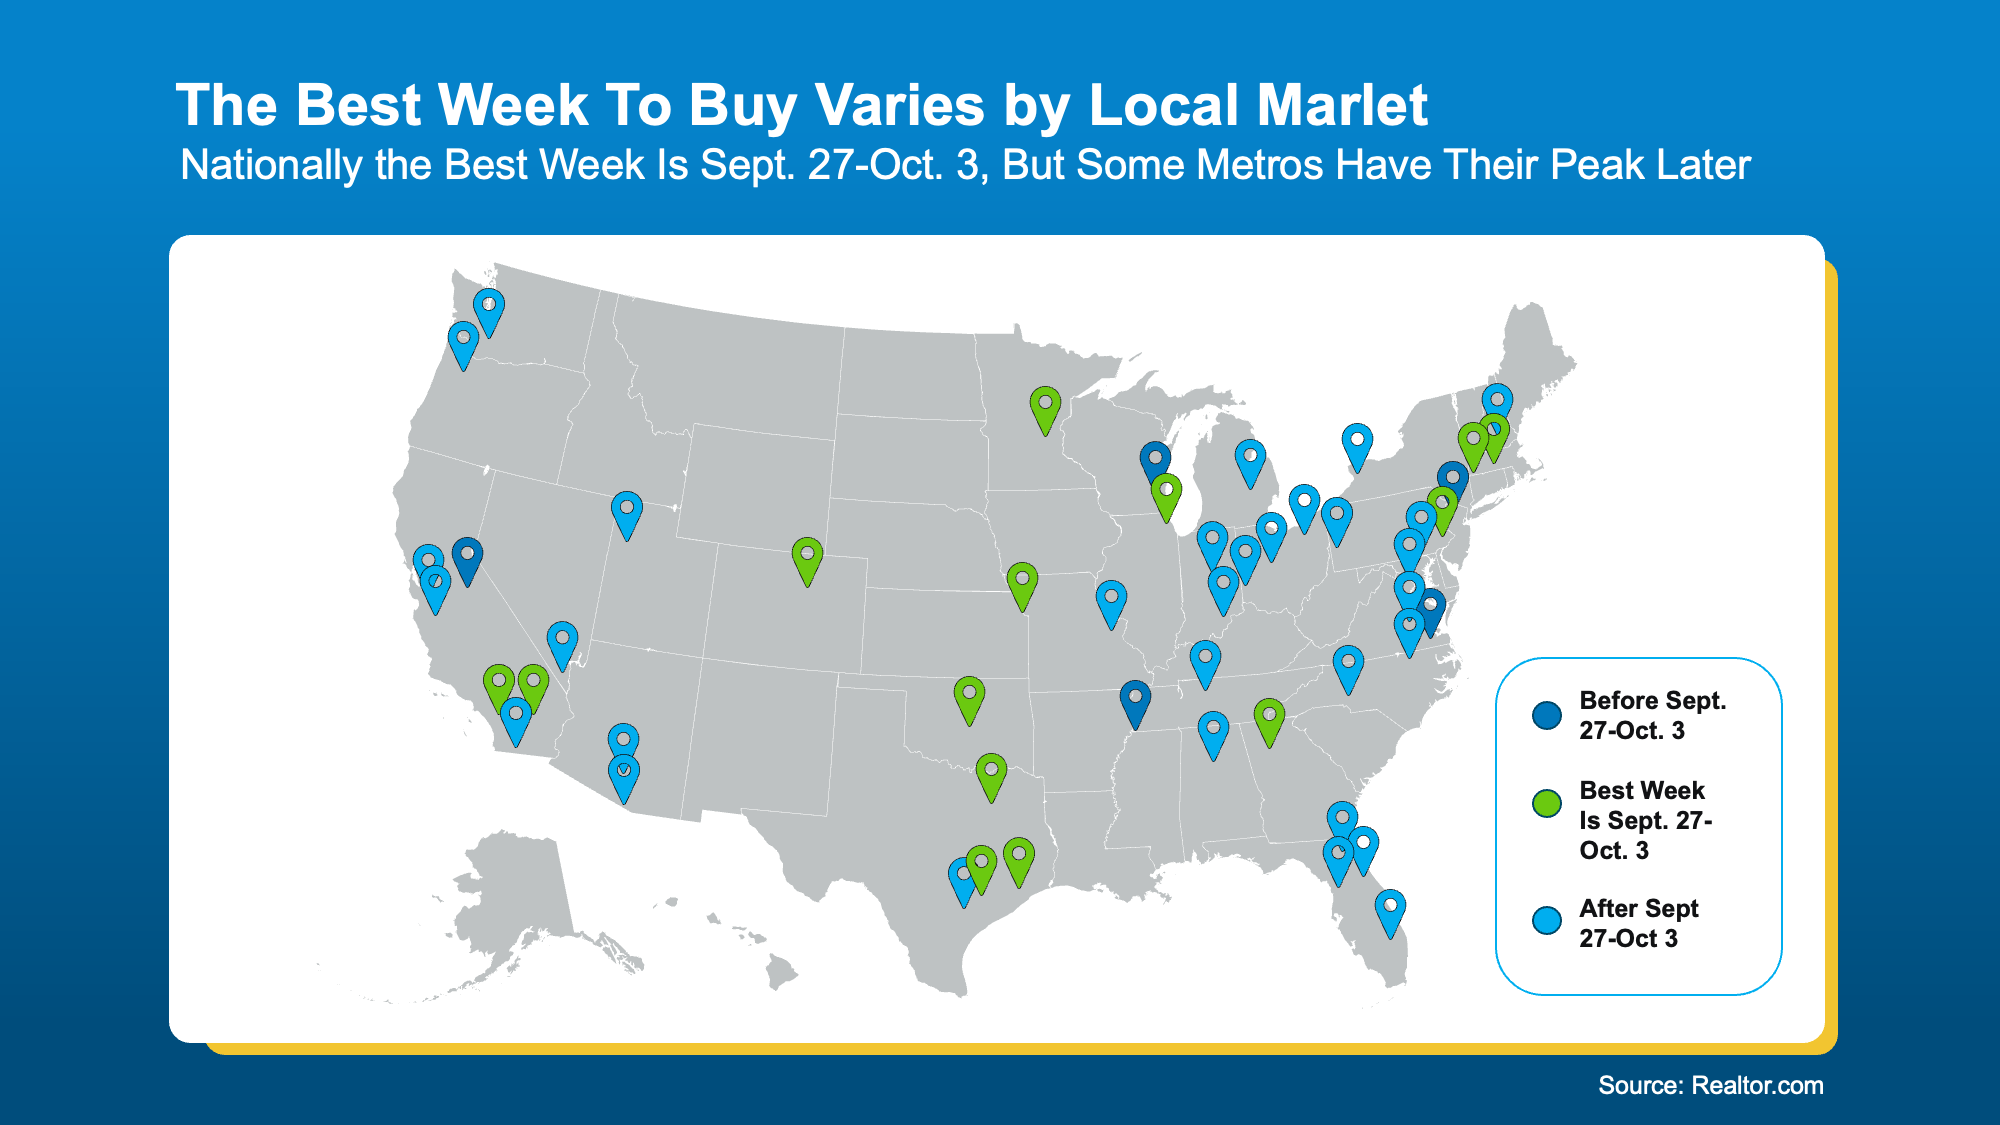
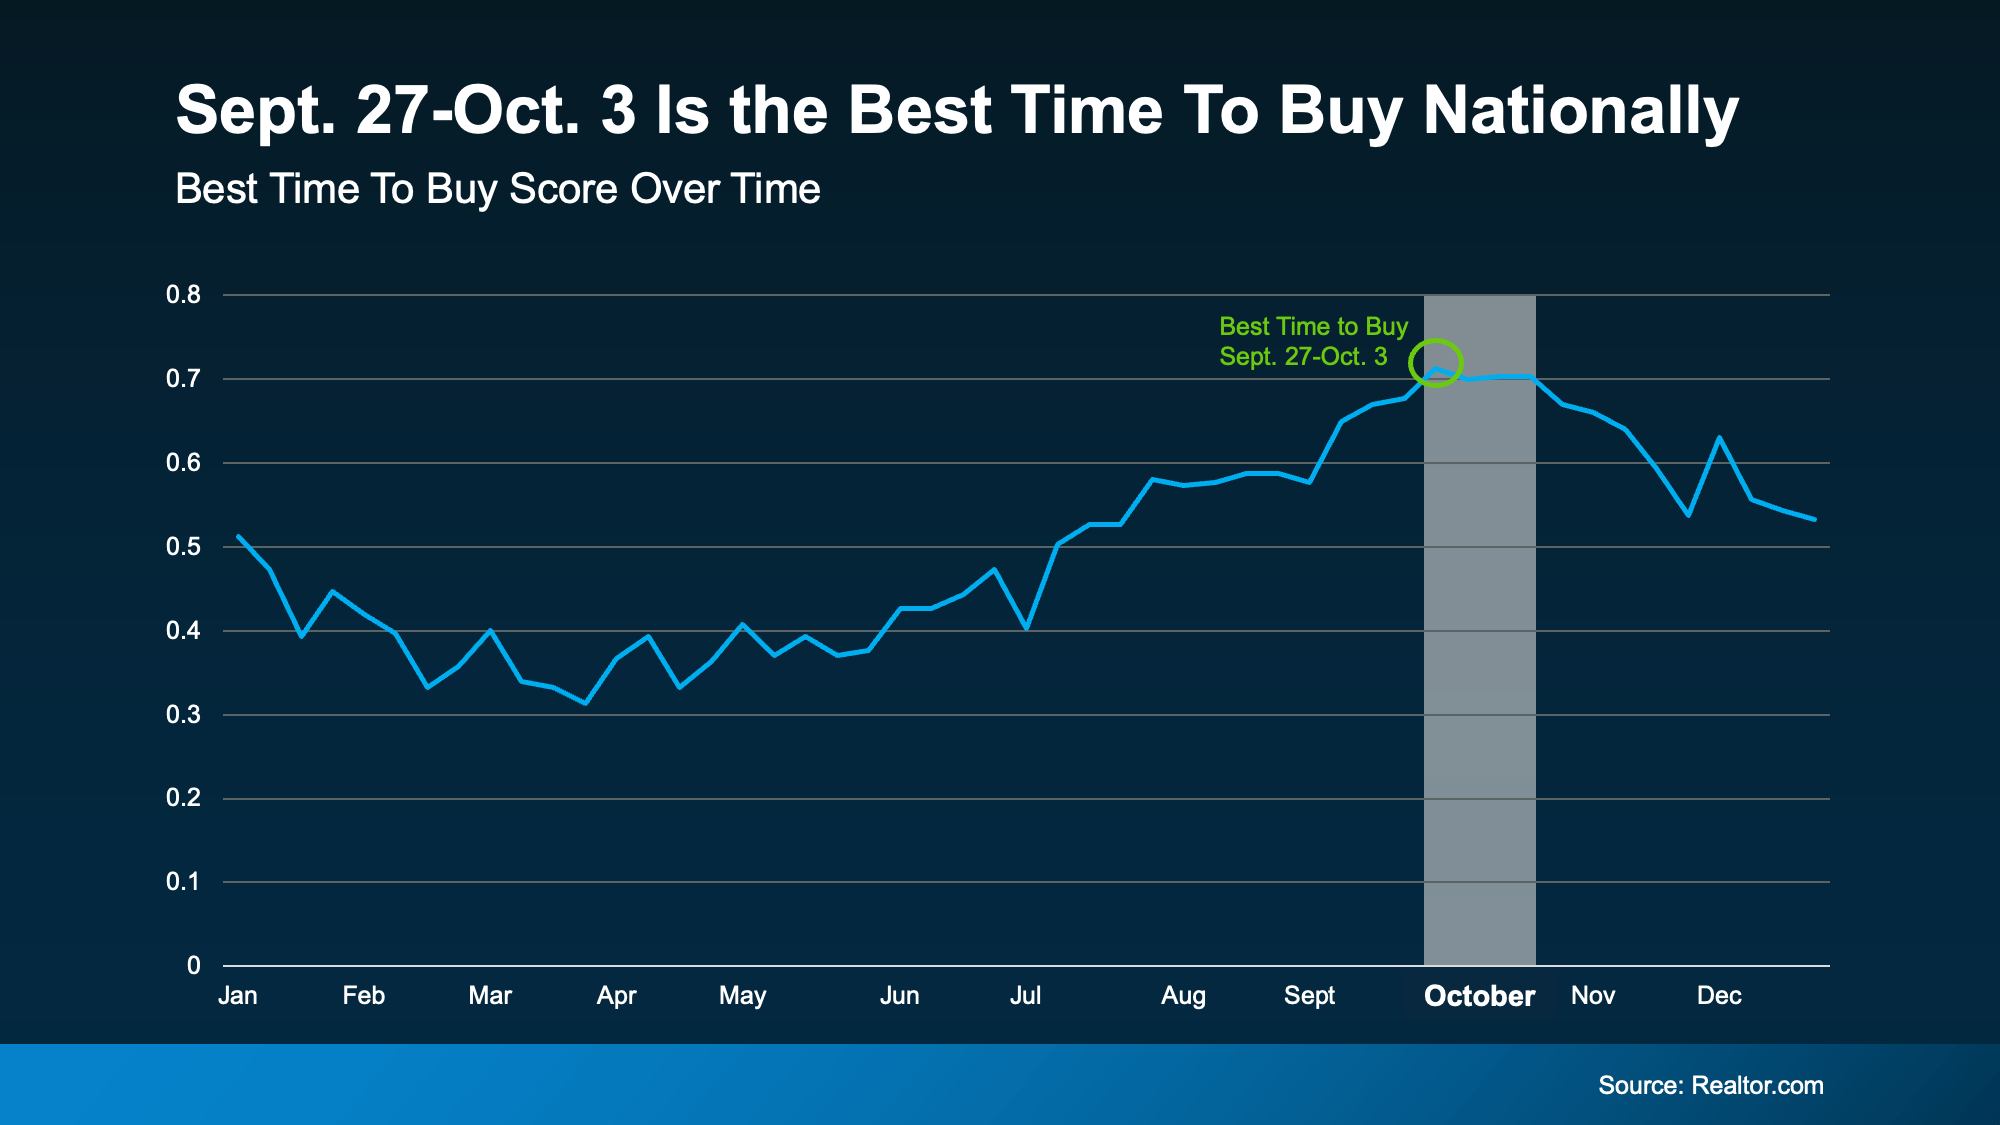
According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:

“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence.”

But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):

a map of the united states with pins

It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.

More Choices, Better Prices, and Less Competition

For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:

“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”

That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.

Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision. 

  • More choices.

  • Better pricing.

  • Less competition.

That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.

The Window Doesn’t Close After This One Week

But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:

a graph on a dark background

In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains: 

“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”

Bottom Line

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in your market?

Have a quick conversation with a lender and a local agent about how your market works and the steps you’ll need to take to get ready. 

Pin It on Pinterest