The Biggest Credit Hurdle for Renters Who Want To Buy

The Biggest Credit Hurdle for Renters Who Want To Buy
The Biggest Credit Hurdle for Renters Who Want To Buy Simplifying The Market

What’s the biggest payment you make every month? If you’re a renter, it’s probably your rent. 

But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It’s pretty frustrating, especially if you’d like to buy a home someday and you’re trying to build your credit.

The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.

The Problem for Would-Be Buyers

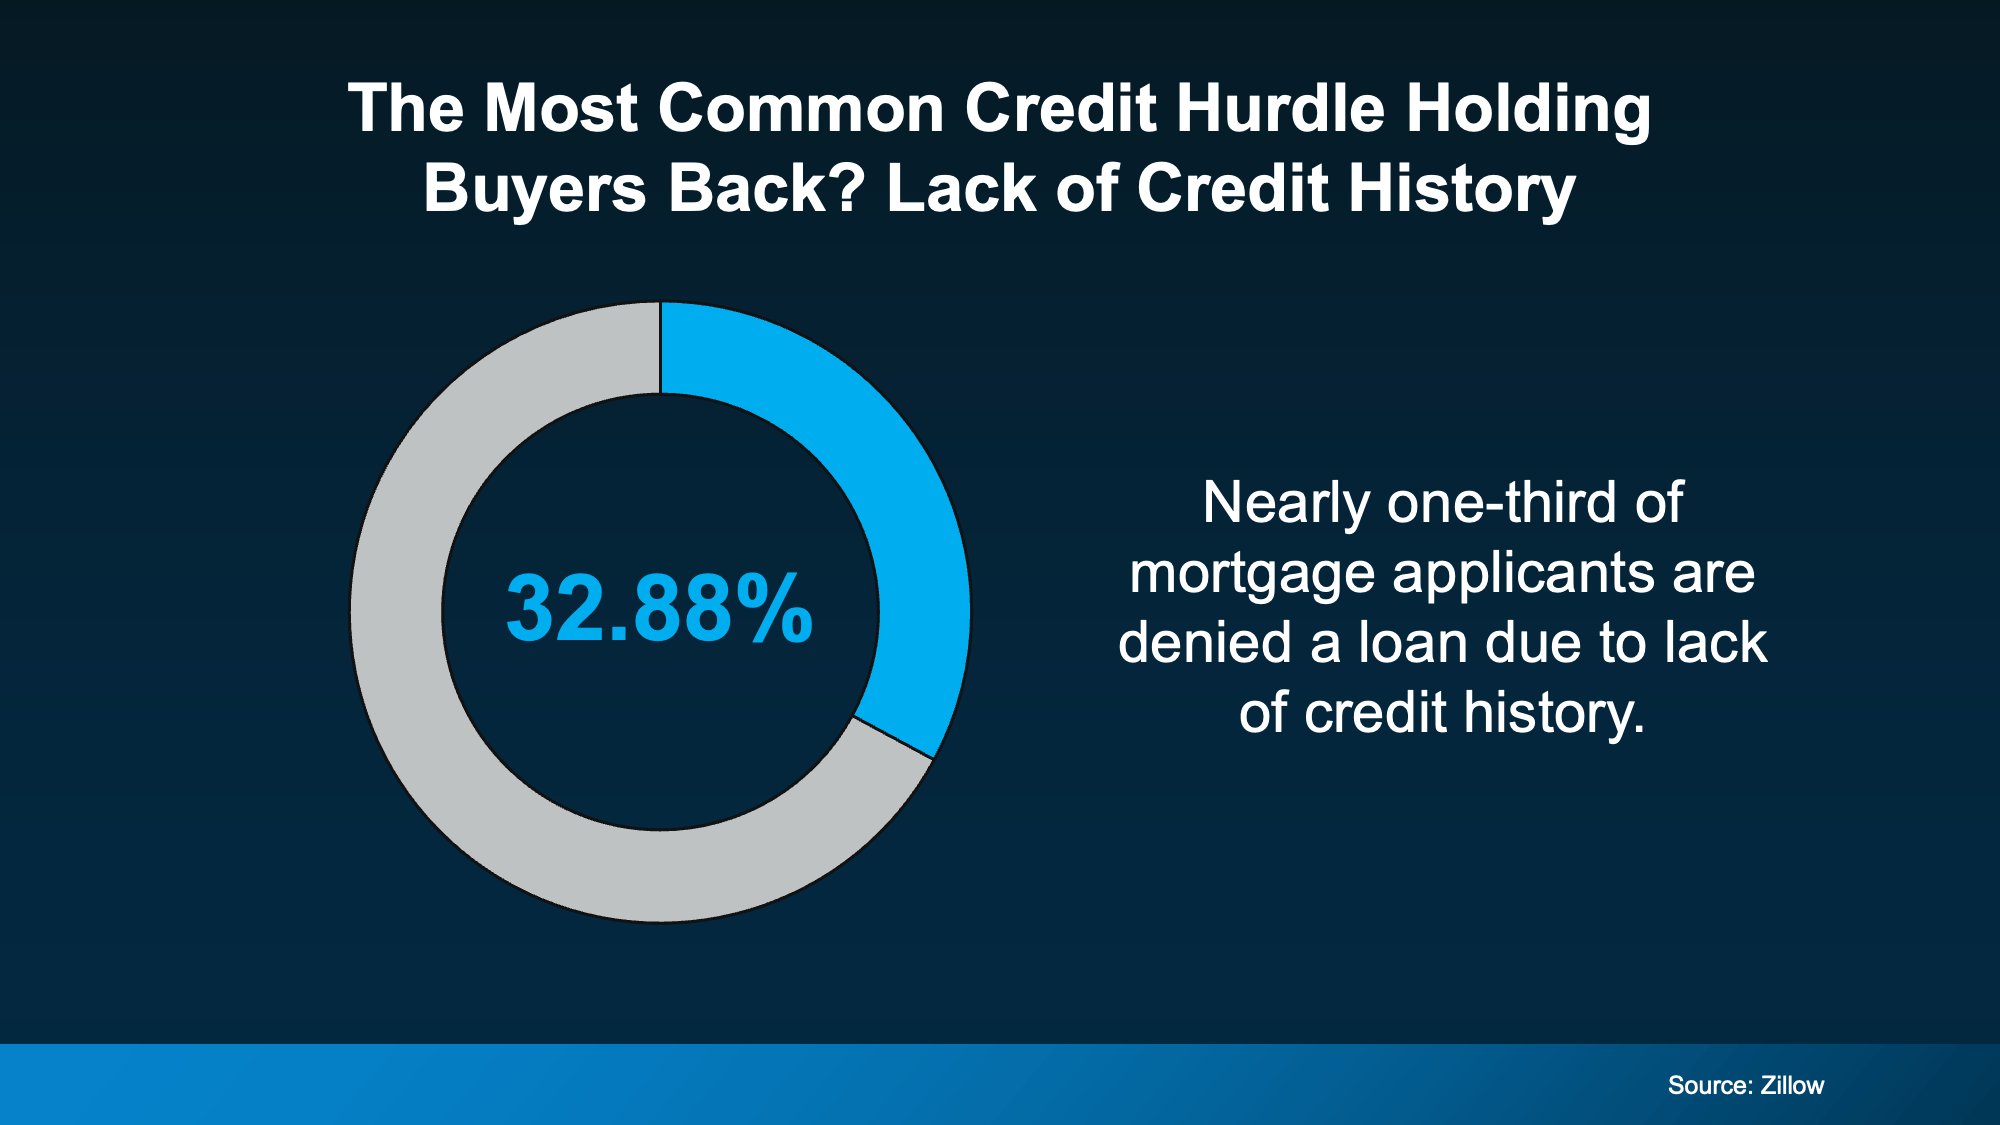
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history – not missed payments or too much debt. Just not enough credit history for a lender to say “yes.”

It’s the most common hurdle would-be buyers have. As Zillow explains:

“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
a blue and grey pie chart

But there’s finally a way in now that how credit gets measured is changing.

The Good News: Credit Is Getting Broader

As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:

“Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”

Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.

VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.

A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.

Here’s the catch though, you still have to walk through it.

Counting Rental Payment History Is Not Automatic

There are more options available to build credit, but you have to be proactive. Your rent won’t necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.

Here’s how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:

  • Ask your landlord or property manager if your rent is being reported. If it’s not, opt in. 

  • If your landlord doesn’t offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.

  • Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.

  • Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don’t apply for a bunch of new credit at once.

  • Don’t close any accounts – even if you have paid them off and don’t use them often.

  • Diversify your profile by getting a secured credit card or becoming an authorized user on someone else’s account to help you build history beyond rent.

These steps take a little time and effort, but it could be worth it if it starts building up your credit history. 

Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better. 

Even if you’re not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.

Bottom Line

The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.

Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you’re closer to owning a home than you think.
Homes Are Still Selling – Even in a Slower Market

Homes Are Still Selling – Even in a Slower Market

Homes Are Still Selling – Even in a Slower Market Simplifying The Market

If you’ve seen headlines saying home sales are slowing down, you may be wondering: is this really a good time to sell?

While the latest numbers show sales picked up slightly in September, they’re still down compared to last year. But here’s the perspective the headlines can miss.

Homes are still selling every single day. Because no matter what’s happening with mortgage rates or the economy, life keeps happening too. People get new jobs. Families grow. Relationships change. People retire, downsize, or need to move closer to the people they love. 

And those life changes create buyers and sellers in every market.

Just Look at the Math

According to the National Association of Realtors (NAR), based on the current pace homeowners are expected to sell almost 4 million homes this year. Break that down, and that’s roughly:

  • 11,000 homes every day.

  • 450 homes every hour.

  • 8 homes every minute.

So, yes, the market may be moving at a slower pace than it has at other points in time. But slower doesn’t mean it’s stopped. As Hannah Jones, Senior Economic Research Analyst at Realtor.com, says:

“Even in today’s high-price, high-rate market, homebuying activity around major life events, such as having kids, a job change, or a divorce, keeps the market in motion.”

Thousands of buyers are still making moves every day. The key is making sure your house is positioned to get their attention.

What That Means for Your Sale

Today’s buyers have more choices, so they can afford to be more selective about things like price and condition. That makes having the right strategy from the start especially important.

Because you don’t need every buyer to be looking for a home like yours. You just need the right one – and to know how to get in front of that buyer.

Bottom Line

Don’t let a headline about slowing home sales convince you no one is buying. Homes are still selling every minute of every day.

If you need or want to move, talk to an agent about what it’ll take to make sure yours is one of them.

Why There are More Homes for Sale Right Now (and What It Means for You)

Why There are More Homes for Sale Right Now (and What It Means for You)

Why There are More Homes for Sale Right Now (and What It Means for You) Simplifying The Market

Mortgage rates being back above 7% isn’t exactly the news most people wanted. But it’s changing the market in ways that matter whether you’re buying or selling.

The number of homes for sale is growing faster than it was this time last year. And interestingly, the main reason isn’t a flood of new listings. It’s because homes aren’t selling as quickly.

Here’s why – and what that means if you’re thinking about buying or selling.

Inventory Growth Is Picking Up Steam

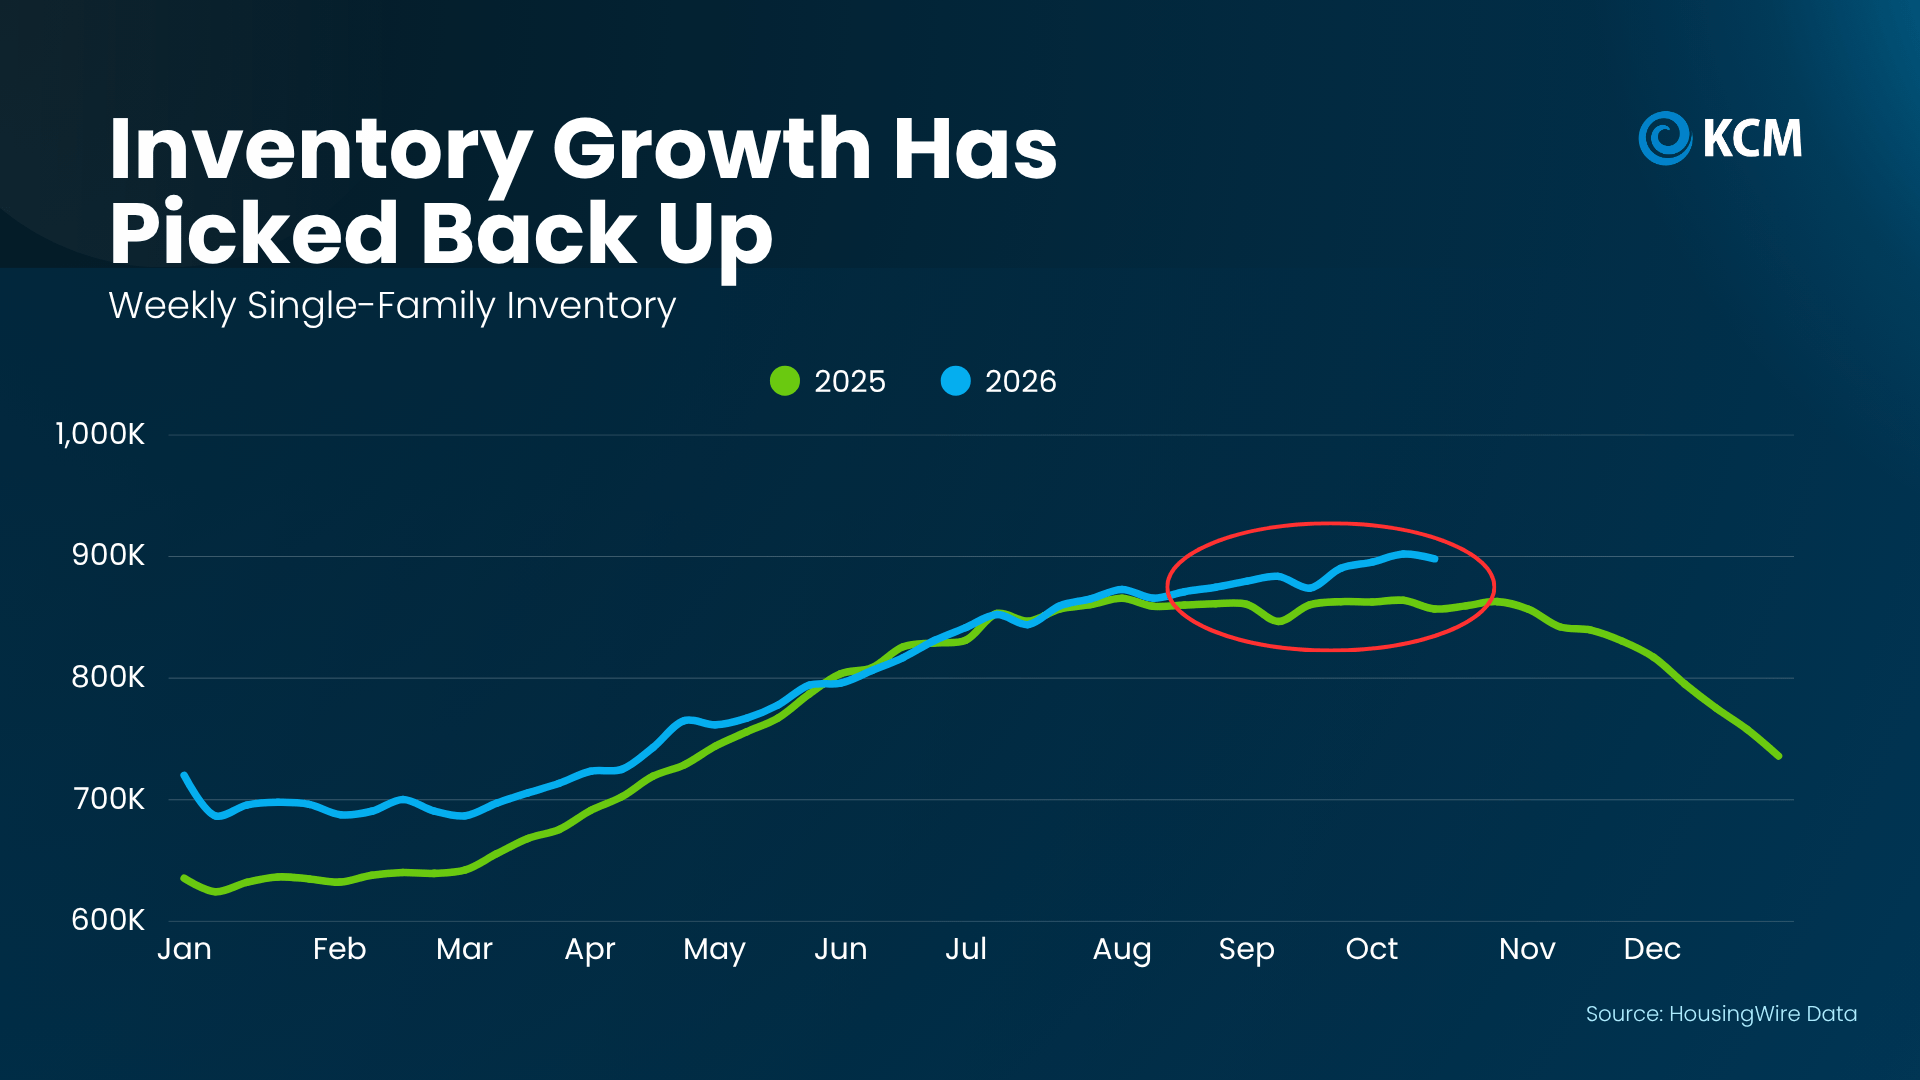
According to HousingWire Data, after inventory growth slowed down for most of the past year, it’s accelerated again in recent weeks. You can see that in the graph below. Just look at the blue line:

a graph of growth and growth

And what’s behind this shift might surprise you.

When rates rise, some buyers hit pause. That means fewer homes sell each week. And as those unsold homes stay on the market alongside new listings, the number available starts to grow (see the blue line in the graph below).

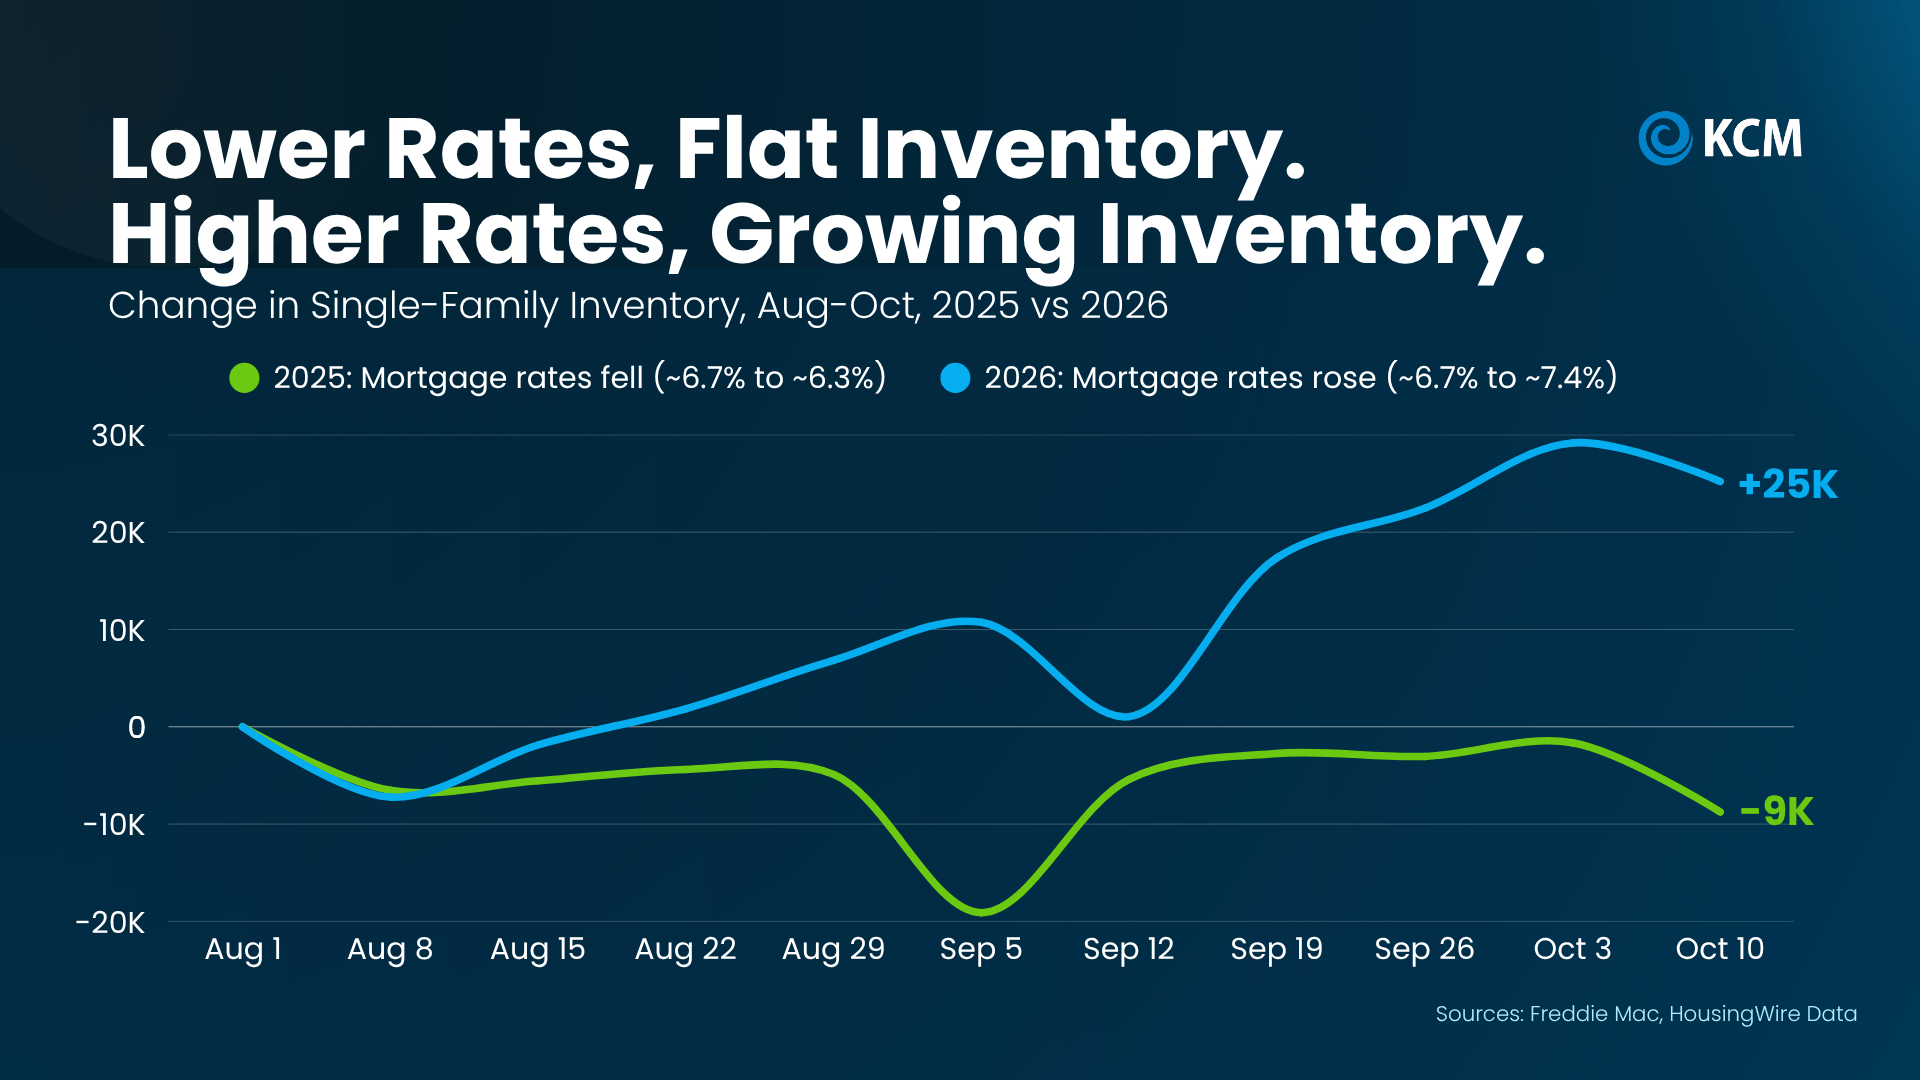
Here’s another way to look at it to make it even more obvious. The graph below shows the relationship between rates and inventory. Again, this year is the blue line. Last year? That’s the green.

With rates inching up this year, you can see inventory has grown by about 25k. But when rates went down this time last year, buyers jumped back in, and inventory actually dropped by about 9k.

a graph of growth and growth of a mortgage

Logan Mohtashami, Lead Analyst at HousingWire, explains how that’s flipped from 2025 to 2026:

“With mortgage rates over 7%, demand tends to soften and inventory rises . . .”

Homes Are Spending More Time on the Market

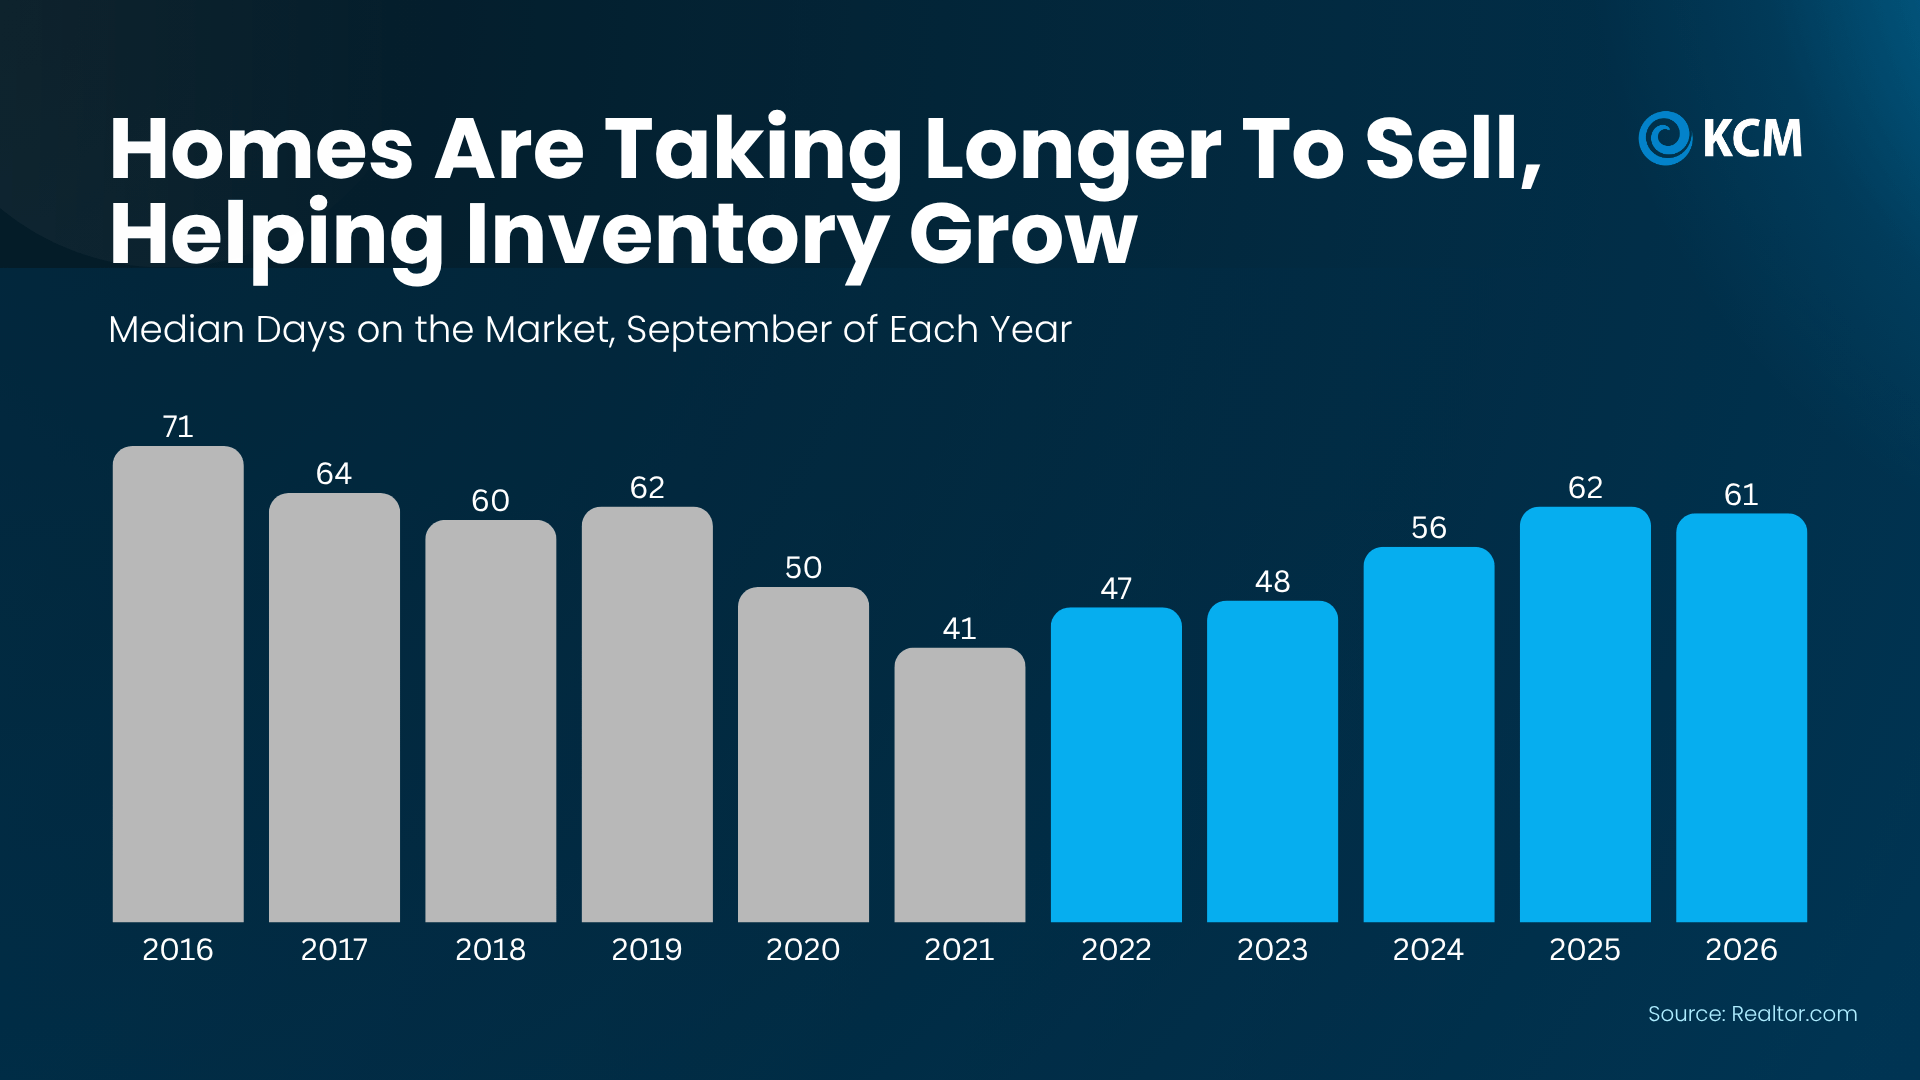
Here’s another metric that shows the impact rates are having: time on market. Data from Realtor.com shows the typical home spent 61 days on the market this September. Back in September 2021, it was just 41 days (see graph below):

a graph of sales growth

Here’s what that tells us. In 2021, when rates were low, more buyers were active, and homes sold fast. But now that rates are a bit higher, not as many buyers are interested, so it takes a bit longer to close a deal.

How To Make This Market Work for You

So, what does all of this mean for your plans? That depends on which side of the move you’re on:

If you’re buying, more homes for sale means more choices and less pressure to rush. And more room to negotiate too. A house that’s been sitting for a while could have a seller who’s more willing to talk – not just about price, but repairs, closing costs, or even helping buy down your mortgage rate.

That doesn’t mean every seller will play ball. But compared to the frenzy of a few years ago, buyers have more leverage now.

If you’re selling, the right strategy can make all the difference. Buyers have more homes to choose from, so making yours stand out is especially important. That starts with pricing it right from day one, making a great first impression, and working with your agent to highlight what makes your house worth choosing. Buyers are still buying and homes are still selling. The key is making sure yours is positioned to attract the right buyer.

The market hasn’t stopped. It’s just moving at a different pace. And whether you’re buying or selling, your strategy needs to move with it.

Bottom Line

In many places right now, inventory is growing and homes are taking a bit longer to sell. And that’s information that should shape the strategy you use going in.

Whether you’re buying or selling, connect with a local real estate agent to look at how long homes are taking to sell in your neighborhood, so your offer, or your price, fits today’s market.

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home Simplifying The Market

With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. 

Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…

Most people who already made that leap would do it again.

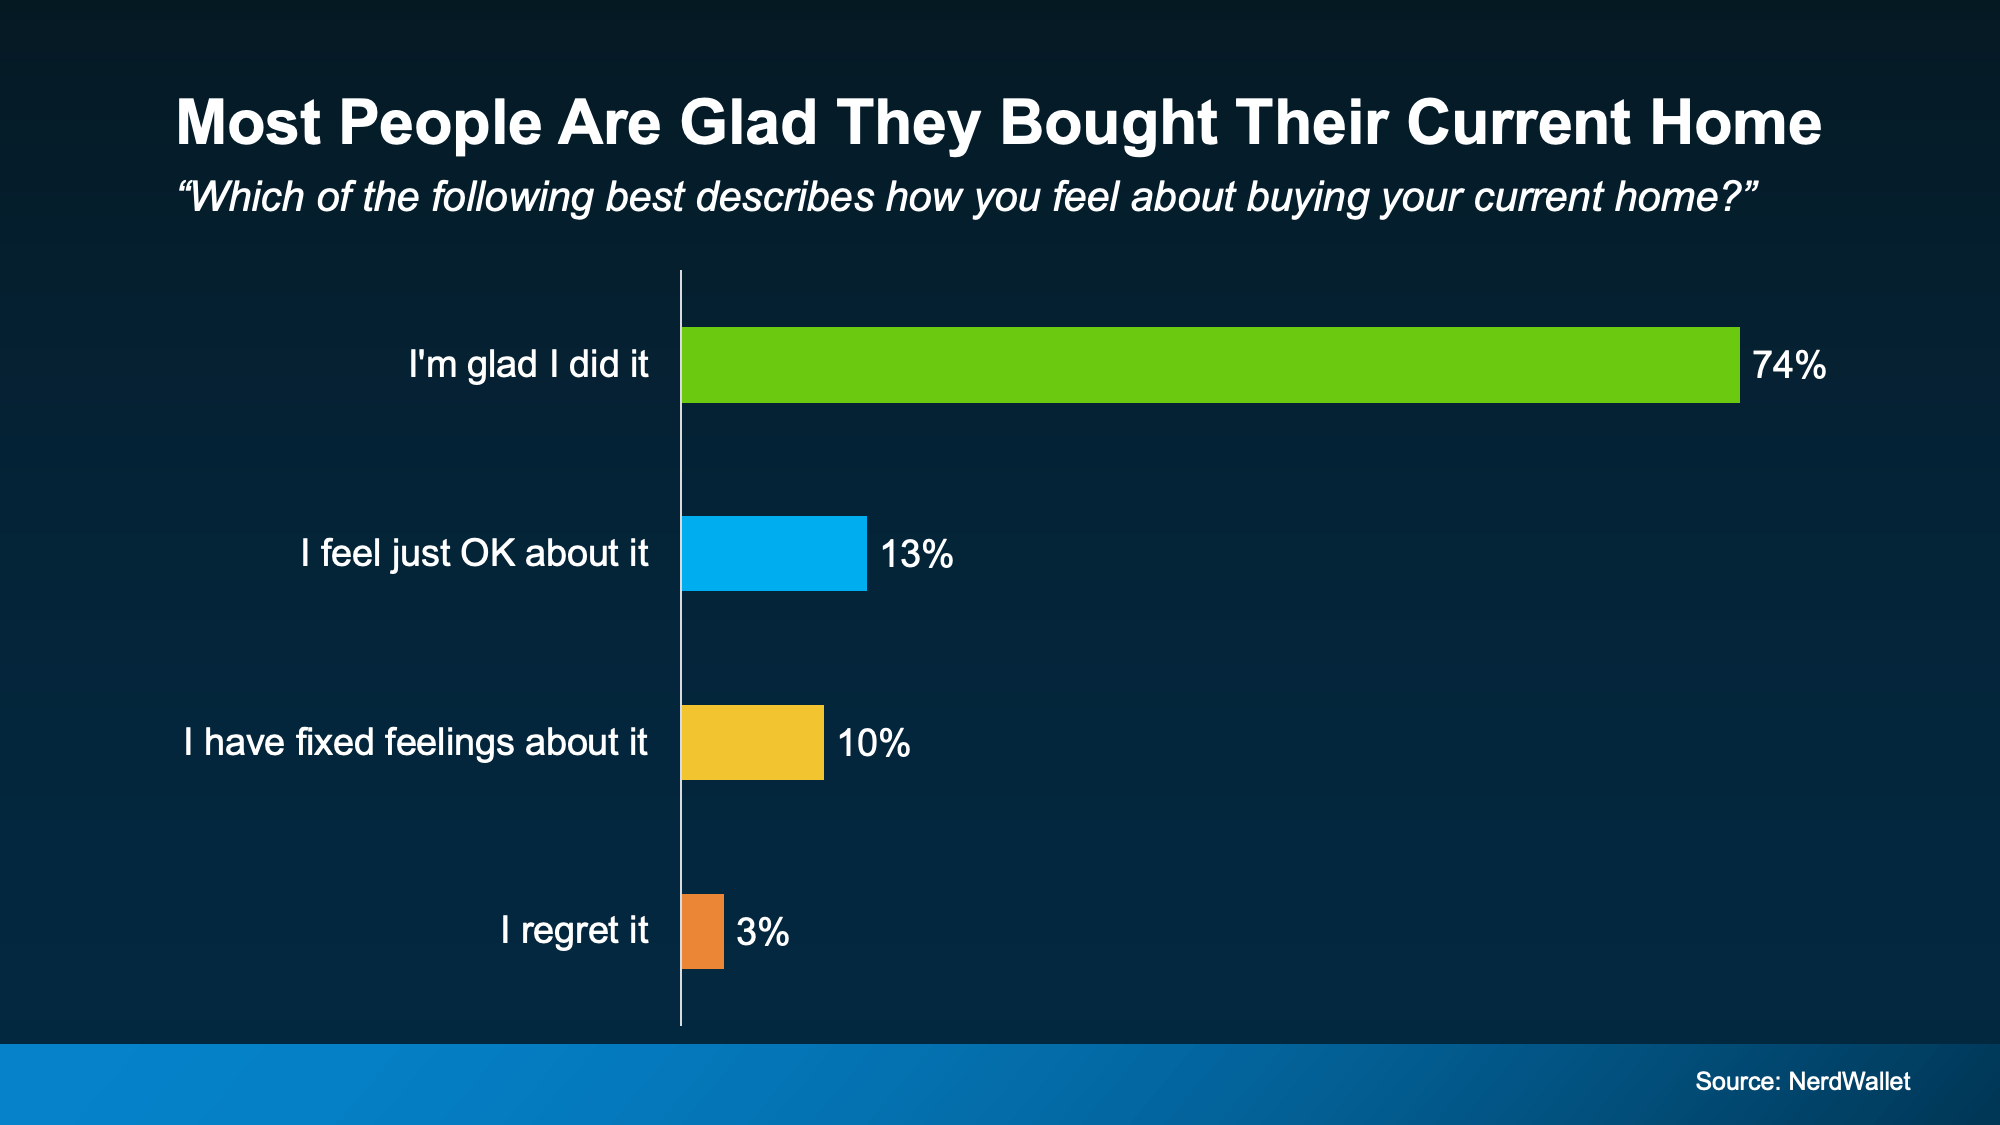
According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:

a graph with text on it

And here’s a big reason why so many people feel it was worth it, even now.

Homeownership Is a Long-Term Play

When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.

A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.

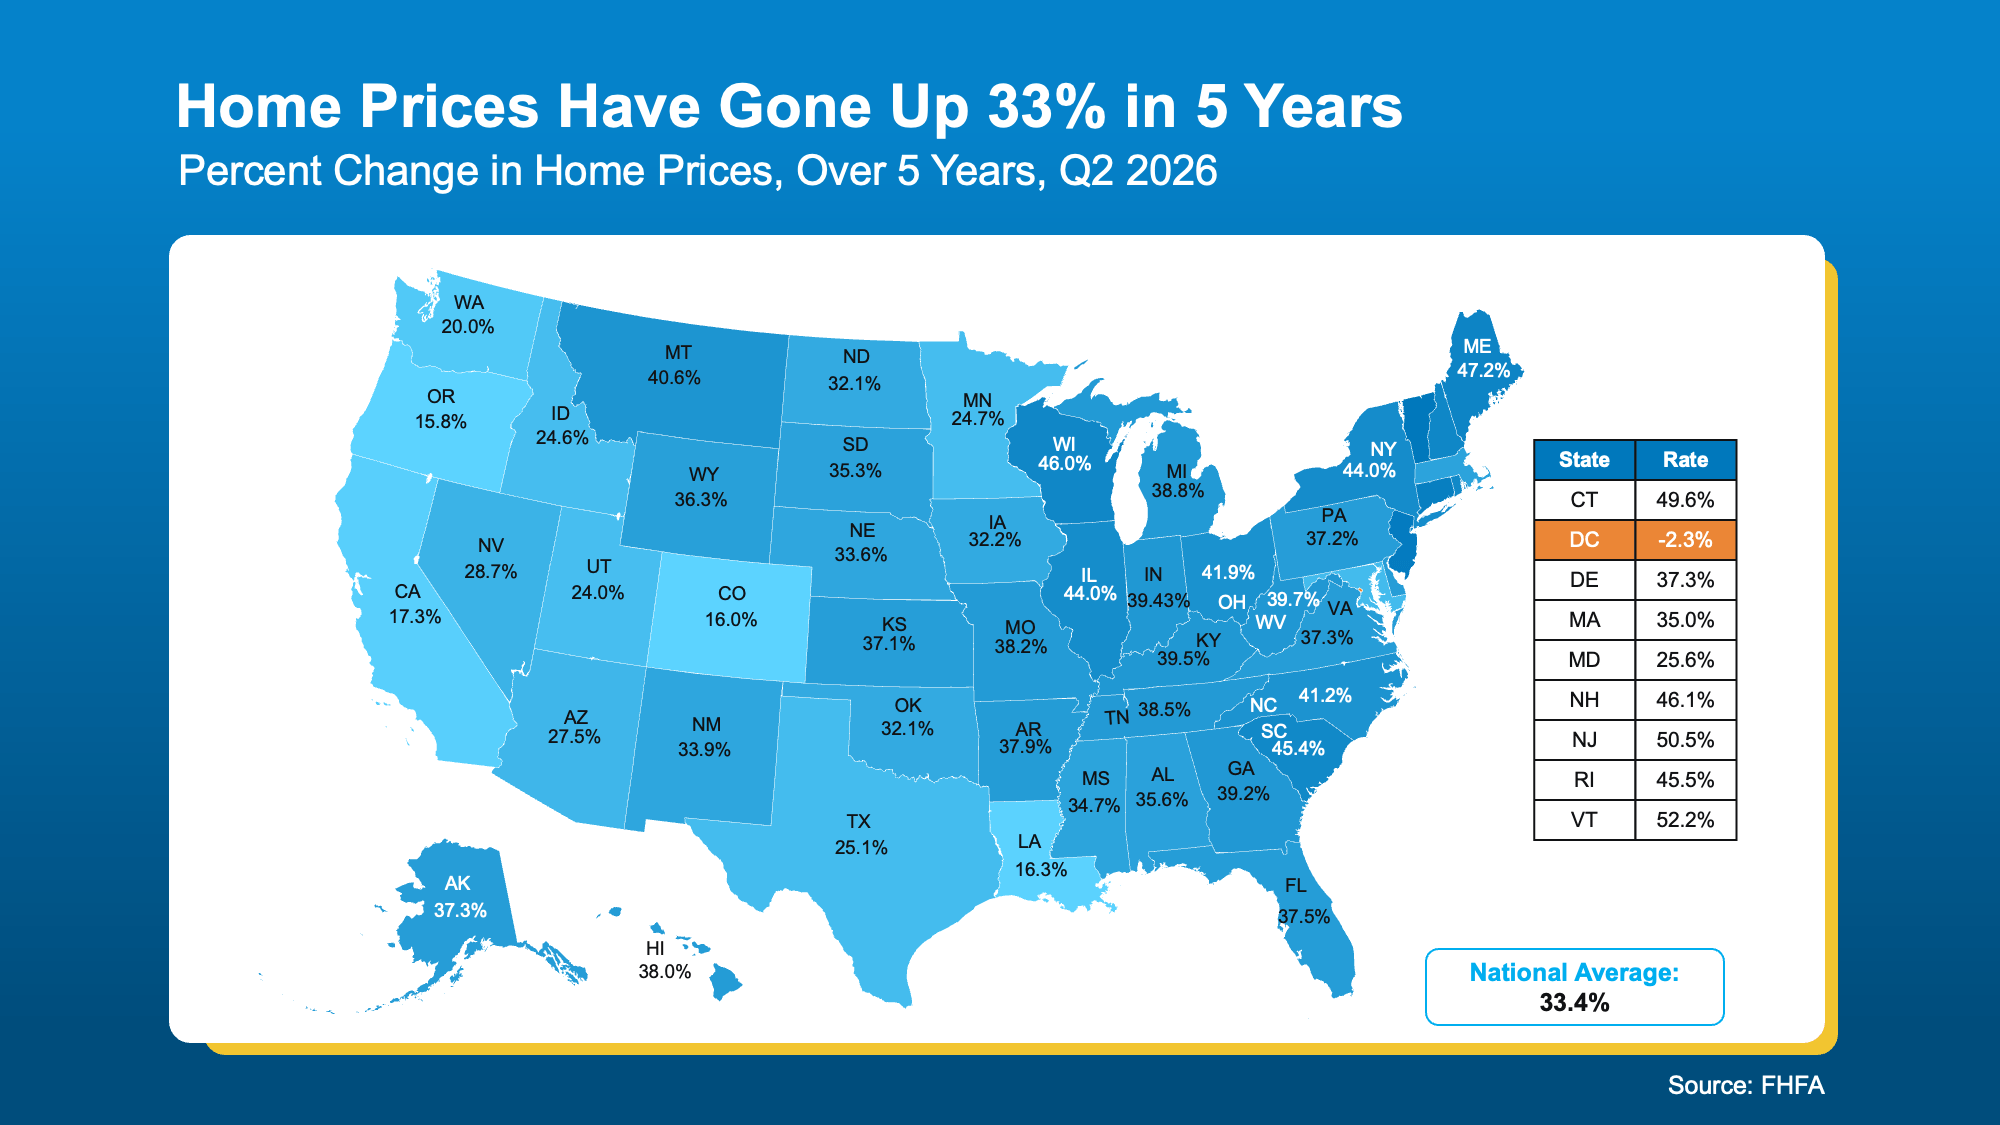
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):

a map of the united states

And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.

That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.

Now, Zoom Out Even Further

The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.

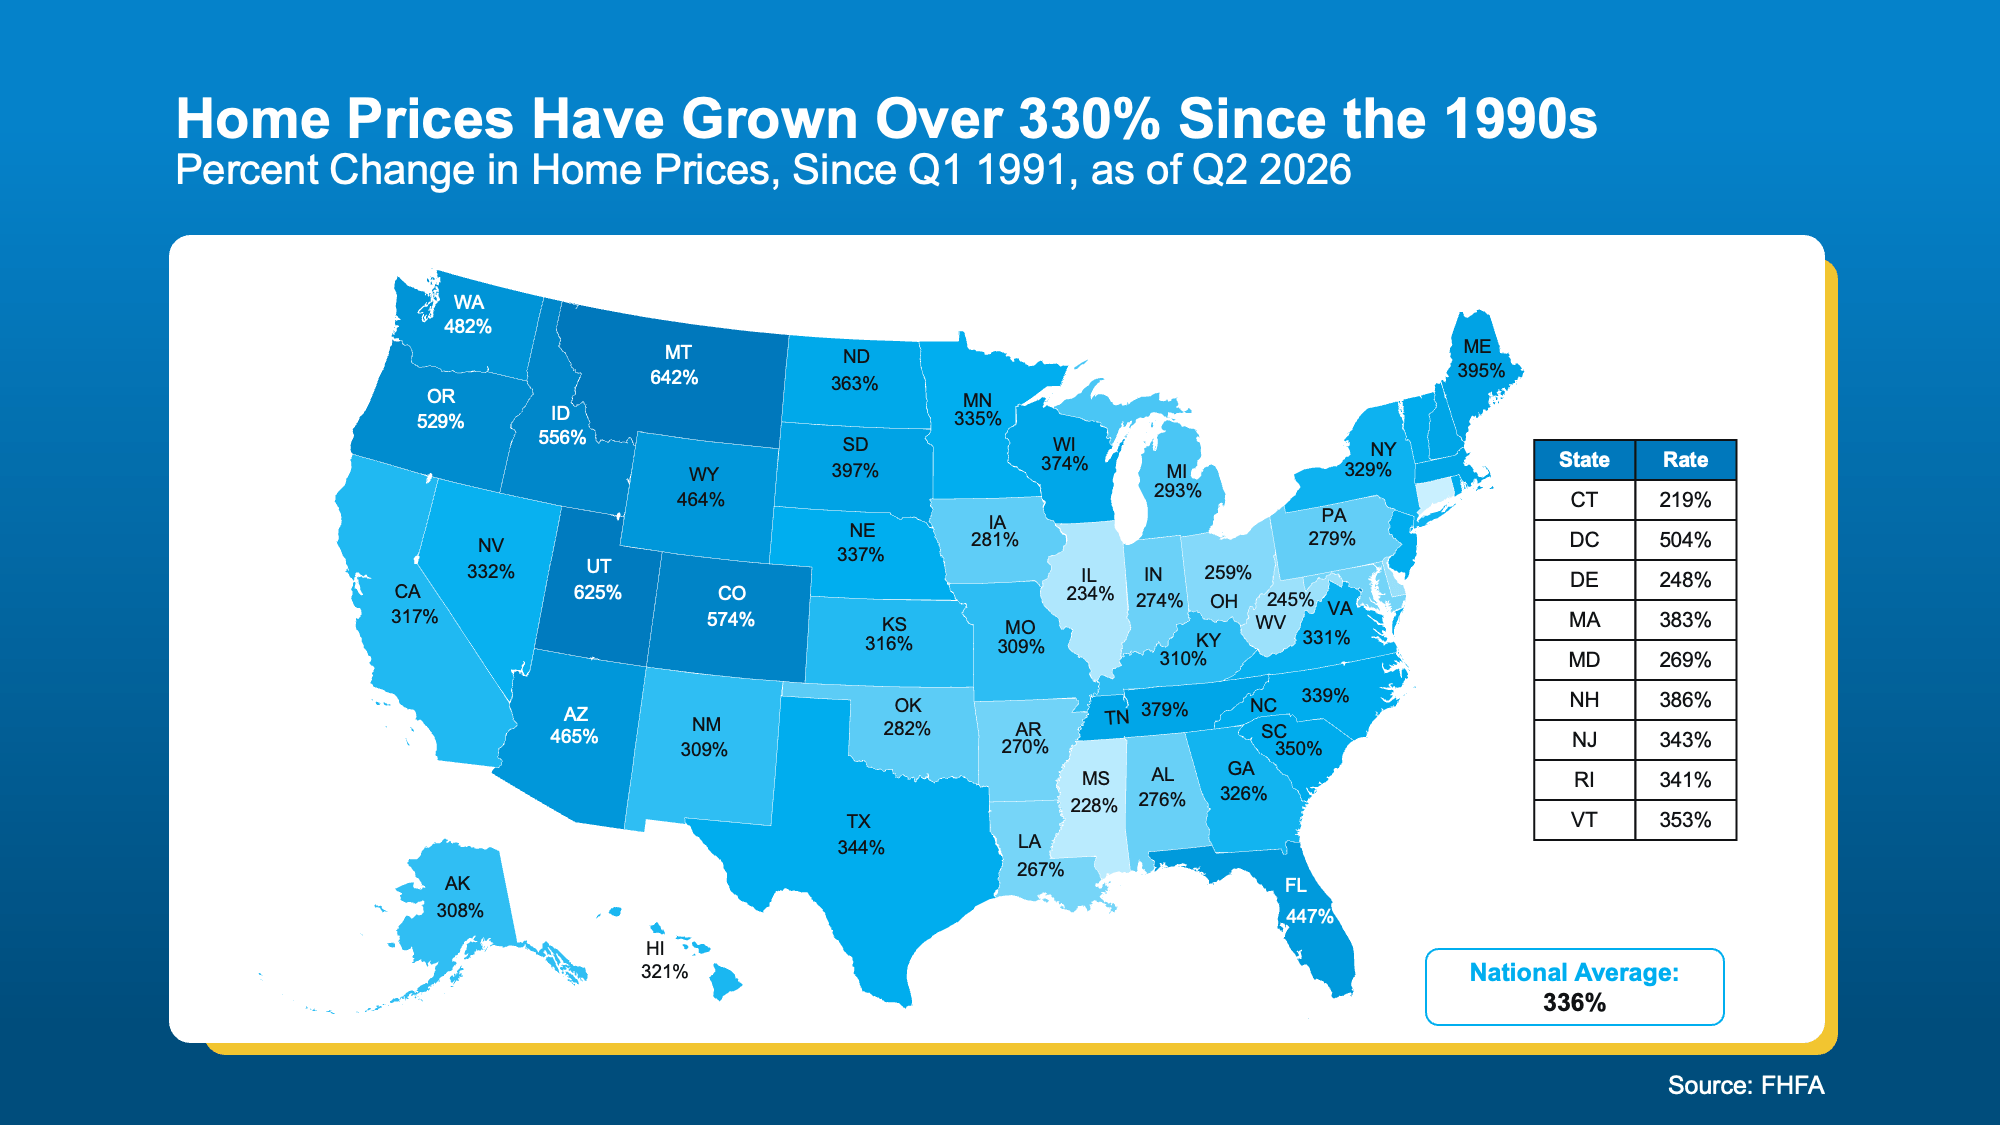
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):

a map of the united states with numbers and a number of states 

That doesn’t mean prices go up every single year. And it doesn’t mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.

What it does show is why trying to perfectly time the market can make you miss the bigger picture. 

Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains: 

“Your home’s equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .

If it’s time to upsize or downsize, you can use that cash for the down payment on your next home.”

Basically, if you can afford to do it, buying a home now could set you up for future moves.

And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.

Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.

Bottom Line

Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.

If you’re wondering whether buying makes sense for you right now, connect with an agent to look at the numbers together – and what owning a home could mean for you in the years ahead.

Renovate or Relocate? What To Know Before You Decide To Age in Place

Renovate or Relocate? What To Know Before You Decide To Age in Place

Renovate or Relocate? What To Know Before You Decide To Age in Place Simplifying The Market

You’ve spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it’s natural to wonder if this is still the place you want to spend it.

Whether you’re leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here’s what to consider before you decide.

What It Can Take To Stay Put

Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier.

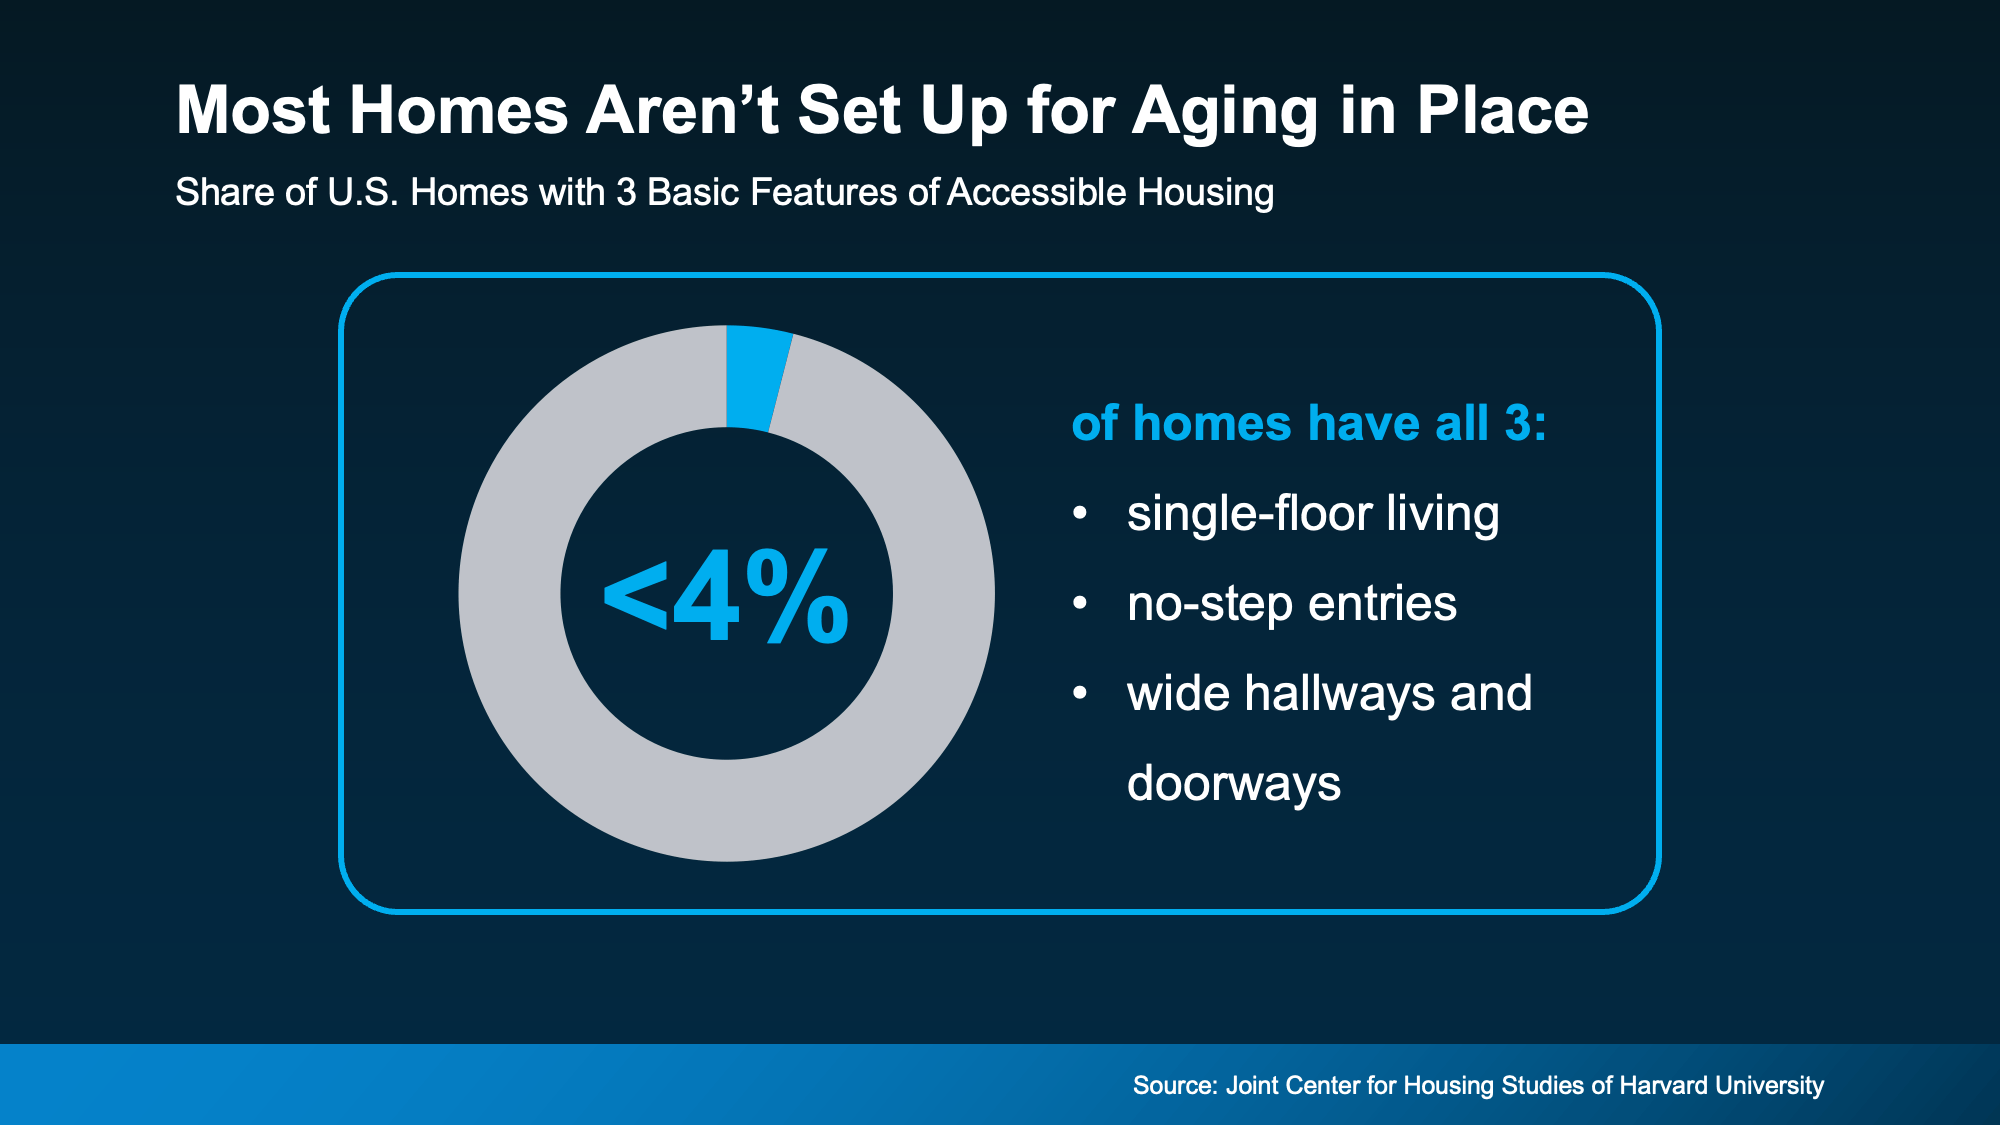
In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below):

a diagram of a pie chart

That means for most homeowners, staying put means doing a remodel.

The National Association of Home Builders (NAHB) reports more than half of remodelers (56%) take on this kind of work. Some of the most common projects are installing grab bars, curb-less showers (walk-in showers with no ledge to step over), and wider doorways.

Now, that’s not to say you can’t go this route. You most certainly can. But if this is how you’re leaning just know you’d be living with contractor noise and dust until the work gets done. Some people don’t want to live in a construction zone. Not to mention, having to manage the contractors and schedules, etc.

Your Equity Could Pay for Your Next Move

If that sounds like something you’d rather avoid, here’s the good news. The money for your next home may already be sitting in your current one. It’s called equity, which is the difference between what your house is worth and what you still owe on it. After years of mortgage payments and rising home values, it adds up. Jess Catorc, Co-Founder of Carry, explains:

“The way home equity builds and is used changes a lot depending on your stage of life. . . . For older homeowners, decades of mortgage payments and home-value growth can turn equity into a financial cushion.“

When you sell, that cushion can go toward a home that’s ready for this stage of life. No demo required. You just get the keys and it’s all there, ready for you. That means less time on projects and more time for living. And one option you may consider if you’re entertaining a move is a 55+ plus community.

Why 55+ Communities Are Worth a Look 

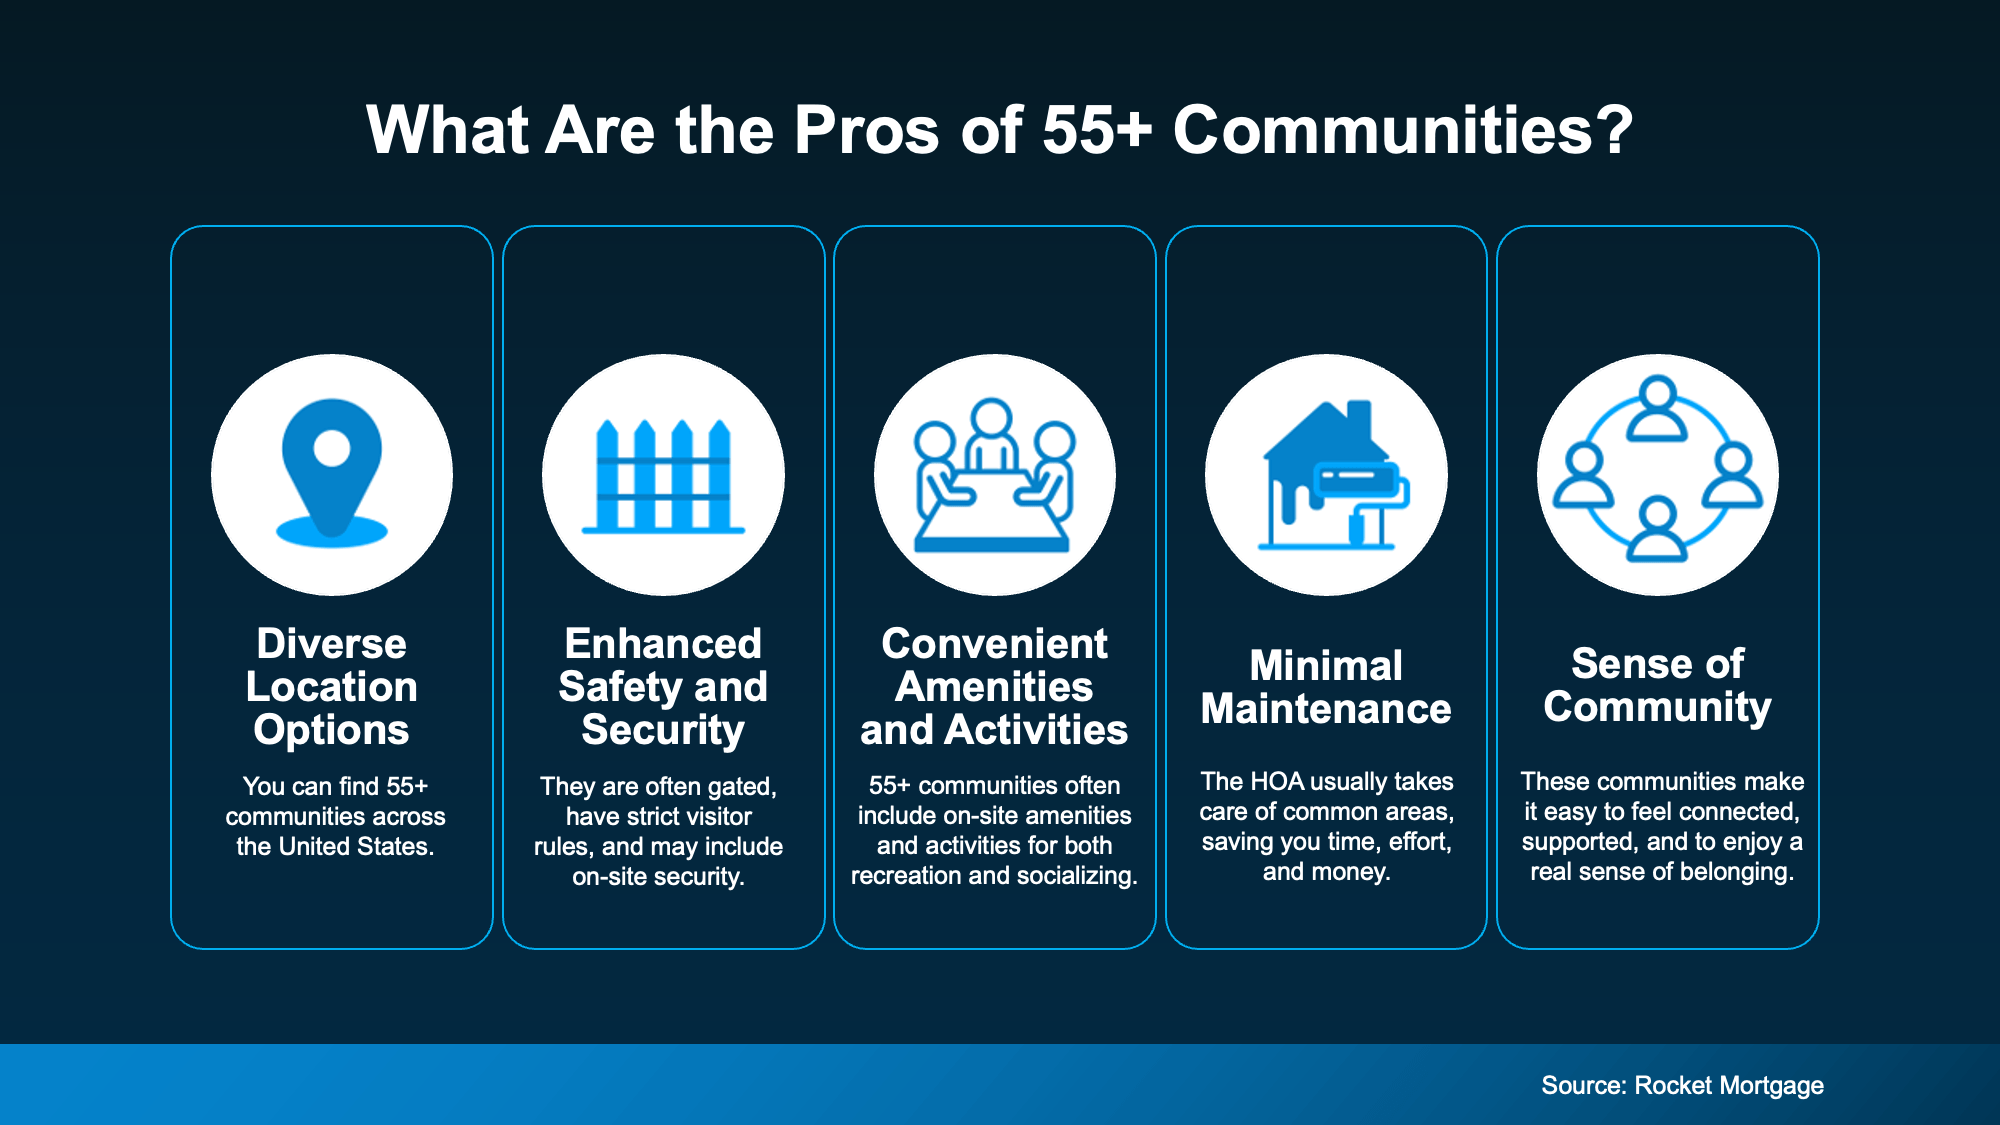
From the homes to the shared spaces to the activity calendar, these communities are planned around this stage of life. And that means everything you need is already rolled into one place. Rocket Mortgage lists some of the biggest perks (see visual below):

a blue and white diagram with white text

Instead of spending time and money to make your house easier to live in, you’d move into a community that’s designed with that in mind from the jump. That frees you up for the good stuff, like a morning walk with a neighbor, a game night down the street, or finally trying the hobby you’ve been putting off.

Bottom Line

Staying and moving can both be good choices. What matters most is finding the place where you’ll feel comfortable and at home for years to come.

A local real estate agent can help you weigh the two by showing you what your house could sell for and what 55+ communities in your area have to offer, so you can decide what feels right for you.

Pin It on Pinterest