Why More Buyers Are Turning To Adjustable-Rate Mortgages Today

Why More Buyers Are Turning To Adjustable-Rate Mortgages Today
Why More Buyers Are Turning To Adjustable-Rate Mortgages Today Simplifying The Market

When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in.

More and more of them are finding it in the adjustable-rate mortgage, or ARM.

The ARM Option  

Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage, your rate stays the same for your whole loan. But with an ARM, your rate is locked for the first few years, then it can move up or down based on market conditions.

Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity. 

Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home. 

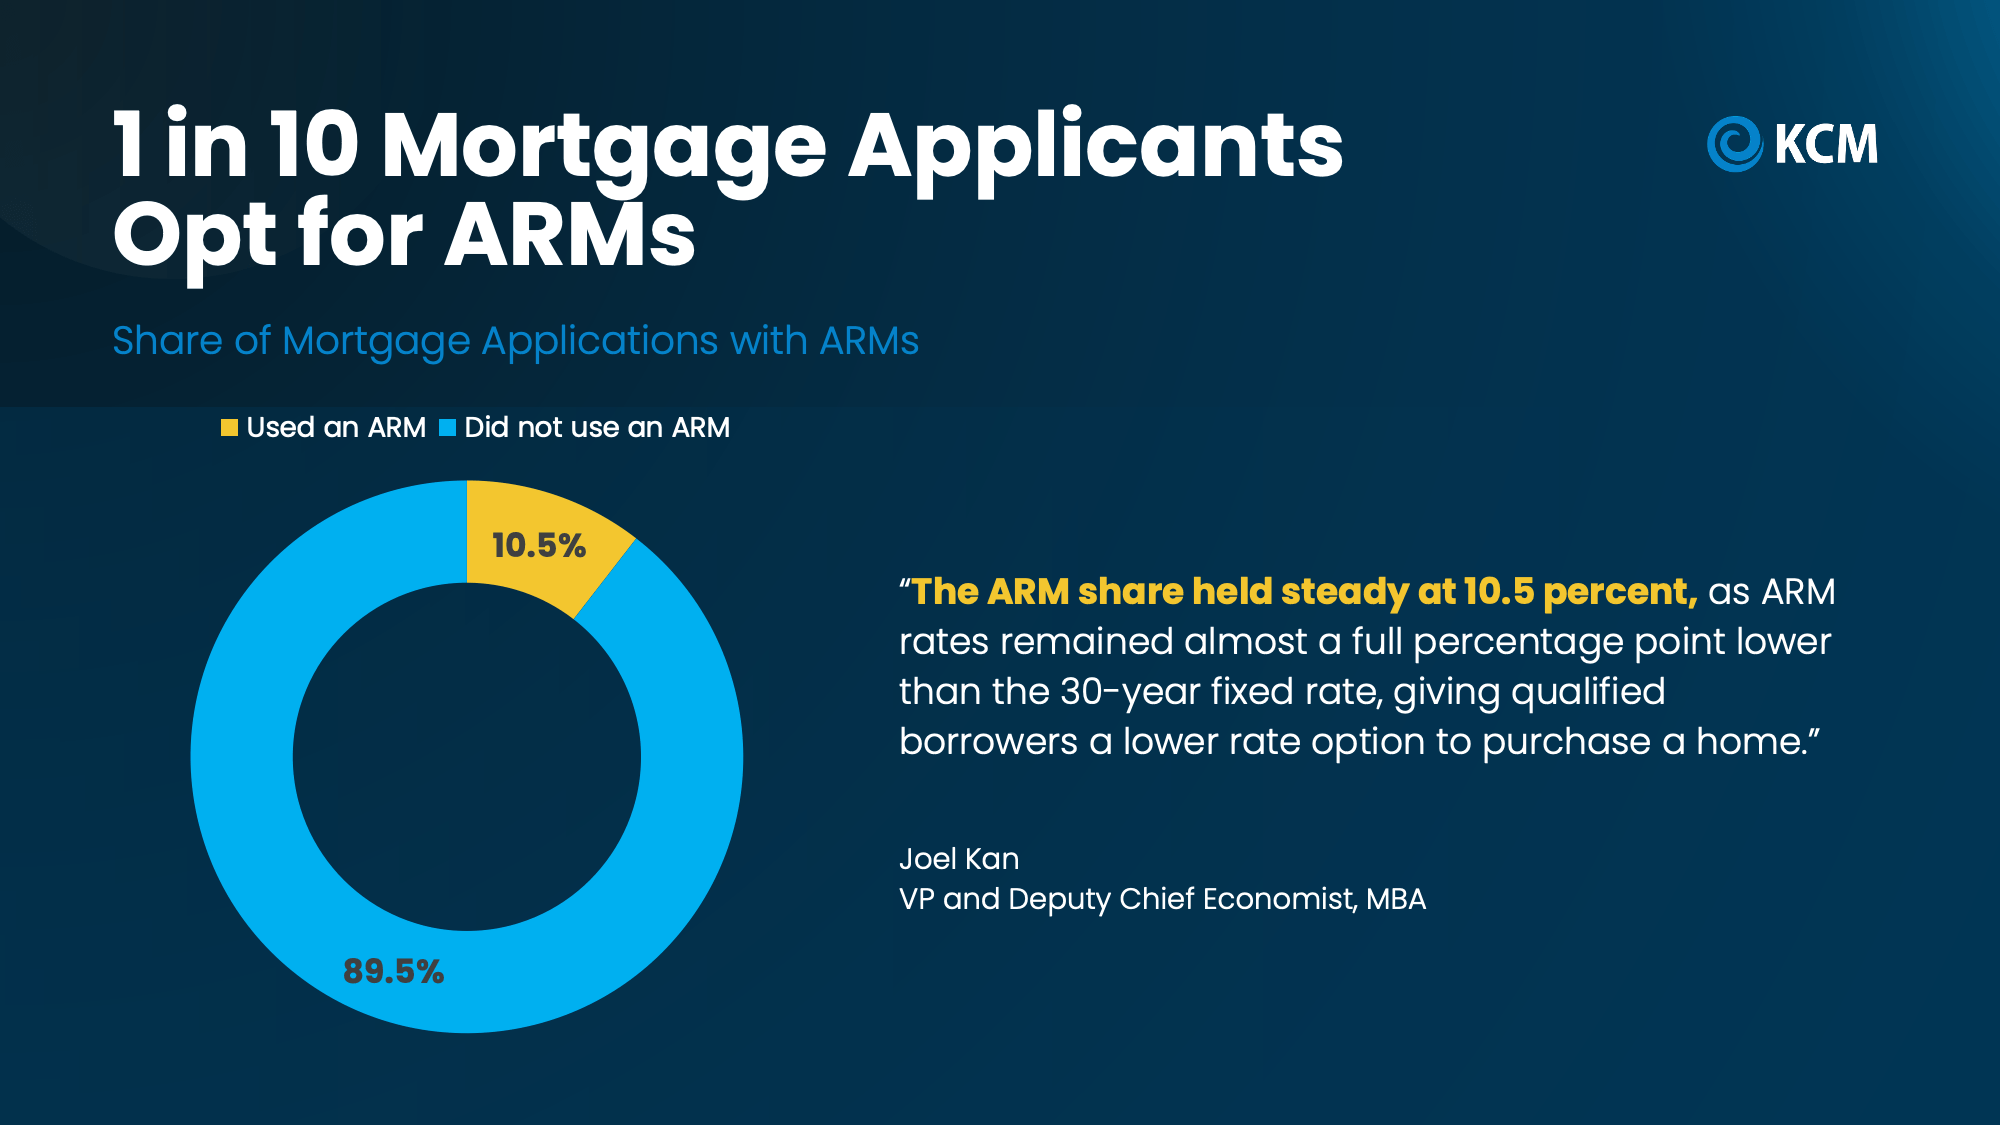
And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below):
a blue pie chart with text

If you think you may want to consider this yourself, here’s what you need to know about how it works.

The 5/1 ARM

An ARM is like a phone or cable plan that has an introductory deal for new customers. You start out at a lower price, and then it adjusts after a specified amount of time. A popular loan is the 5/1 ARM.

The “5” means your introductory rate is locked for the first five years, and the “1” means that the rate can change every year after that. The rate change is called the “reset.” And here’s the really important part.

When your rate resets, your mortgage payment could go up or down. The good news is that most ARMs have caps, which are limits on how much your rate can rise each year and over the life of the loan. But either way, you have to be ready. 

The Upsides and Potential Downsides

To see if this type of loan may be right for you, here are some things to think about and discuss with your loan officer:
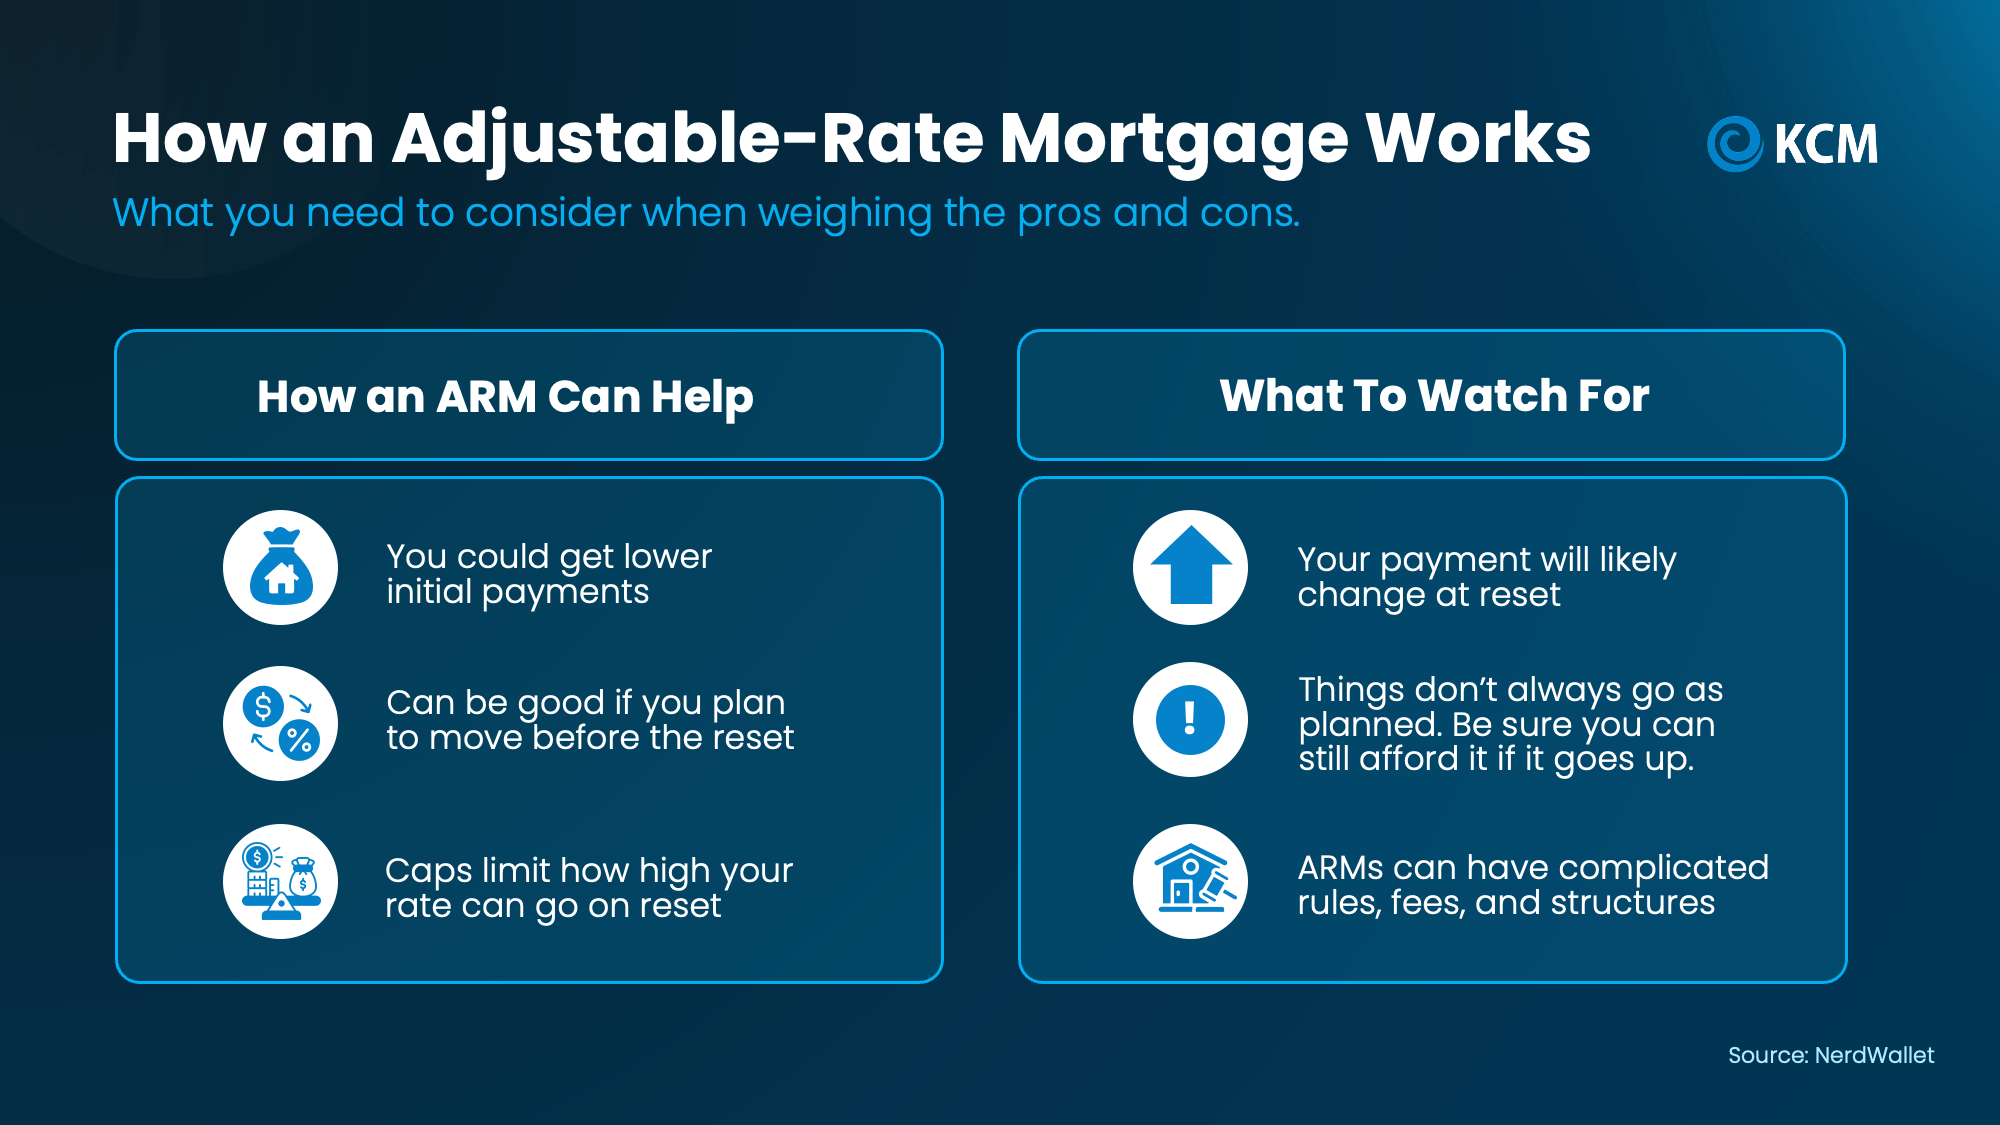
a blue and white rectangular box with white text

Before you decide, ask your lender to work up the numbers and walk you through the different potential scenarios you could run into with an ARM. That way, you go in with your eyes open.

Be Ready for the Reset

And, if you do go with an adjustable-rate mortgage, just know that you’ll have choices when the reset time arrives. You could:

  • Do nothing and keep your loan in place if the new payment still fits your budget.

  • Refinance into a fixed-rate loan with a payment that never changes.

  • Refinance into another ARM with a new lower rate locked for a specified timeframe.

  • Sell your home.

  • Talk to the loan servicer about assistance or modification.

Remember, a refinance is a brand-new loan that you’ll have to qualify for – even if it’s on a home you already own. So, keep tabs on your credit and debt levels and ask your loan officer how major financial moves like job changes and major purchases will affect your mortgage readiness. It’s important to keep your credit and finances in “mortgage shape.”

Today’s ARMs Aren’t Like 2008

One more quick note. ARMs got a bad name after the financial crisis of 2008. Back then, there were some risky loans with small starting payments that later shot way up. Others let people borrow without proving how much money they earned.

But now, there are new laws to protect both borrowers and lenders. The biggest change is the Ability-to-Repay Rule, which says that before a lender makes a home loan, it has to check real paperwork (like pay stubs, W-2 forms, and tax returns) to make sure you can afford it. The lender also has to look at what your payment could be after the reset, not just the low starting payment. 

So, you don’t have to worry that today’s ARMs are the same as the ones we saw back during the crash.

Bottom Line

Today’s market has more options than many people realize. Finding the right one could be as simple as getting more information about tools like ARMs. A trusted lender can run the numbers with you, walk you through the what-ifs, and help you explore the possibilities.

Is an ARM a good option for you? Talk to a loan officer to find out.
Want a More Affordable Home? Don’t Overlook Condos.

Want a More Affordable Home? Don’t Overlook Condos.

Want a More Affordable Home? Don’t Overlook Condos. Simplifying The Market

When you picture buying your first home, chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now.

So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo.

Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door.

Condos Can Cost Less Than You Think

According to a recent study by Zillow: 

“Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home.”

And depending on where you live, the difference can be much bigger. 

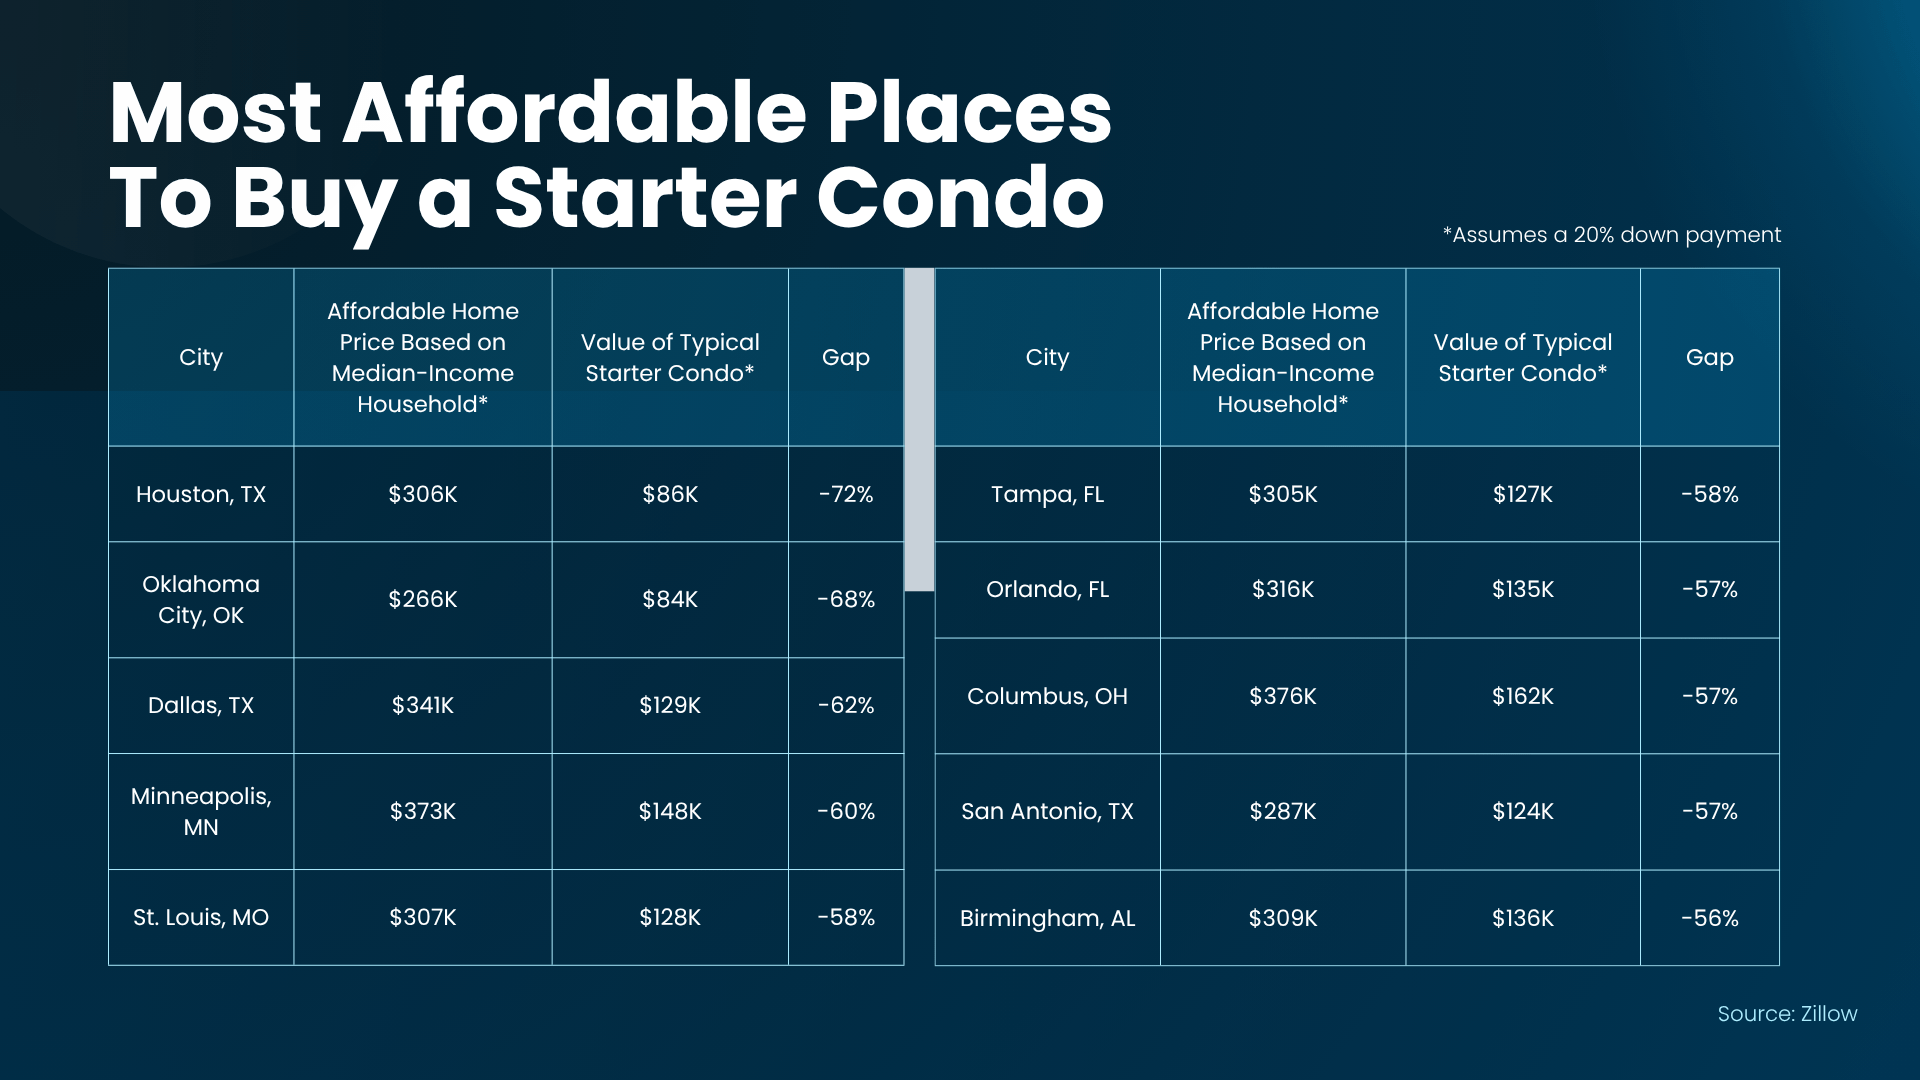
Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research (see chart below).

In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area’s median household income.

a blue and white chart with white text 

Of course, every market is different. But the bigger point is this: if you’ve only been searching for traditional single-family houses, you may be overlooking some of the more affordable options on the market.

And even if your city didn’t make this list, that’s okay. The trend holds true in many places across the country. Here’s why.

A Condo Could Give You a Different Way In

Part of the reason condos can cost less is pretty straightforward. They’re typically smaller. And less square footage can mean a lower purchase price.

So, if you can make do with a bit less space or you’re coming from a smaller apartment now, this can be a great way in. Plus, on the upside, you won’t have to buy a ton of furniture to fill out a bigger house. You can get a potentially lower price up front and spend less once you move in because you’ll need less new stuff to fill that empty space.

And more buyers are making that trade off on space to offset the current affordability challenges. Ali Wolf, Chief Economist for New Home Source, explains:

“In addition to favoring smaller floor plans, more consumers are showing a willingness to live in an attached home. This shift is not driven by a preference for shared walls, but by a pursuit of value.”

That’s really the heart of it. Looking at condos isn’t necessarily about wanting less. It’s about finding another way to make your move happen with the budget you have.

Don’t Rule Out an Option That Could Work

If you’ve been struggling to find a house you like at a price you can comfortably afford, talk to your agent about adding condos to your search.

You may find something in a neighborhood you thought was outside your budget. You could get access to amenities you wouldn’t otherwise have. And you may be able to become a homeowner sooner rather than waiting for the numbers on a single-family house to work.

While there are trade-offs like shared walls, less outdoor space, and an HOA fee to factor into your monthly budget, maybe that’s worth it if you finally get your own set of keys.

Plus, a lot of the times, a condo community comes with great amenities like pools, gyms, and the condo association handles at least some of the maintenance. Which is closer to what you’re used to from your apartment – it could make the transition to homeowner not just more affordable, but that much easier too.

Bottom Line

The first home you buy doesn’t have to be a single-family house. If affordability has been holding you back, talk to a local agent about expanding your search and see whether a condo could fit the price point you’re looking for.

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home Simplifying The Market

With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. 

Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…

Most people who already made that leap would do it again.

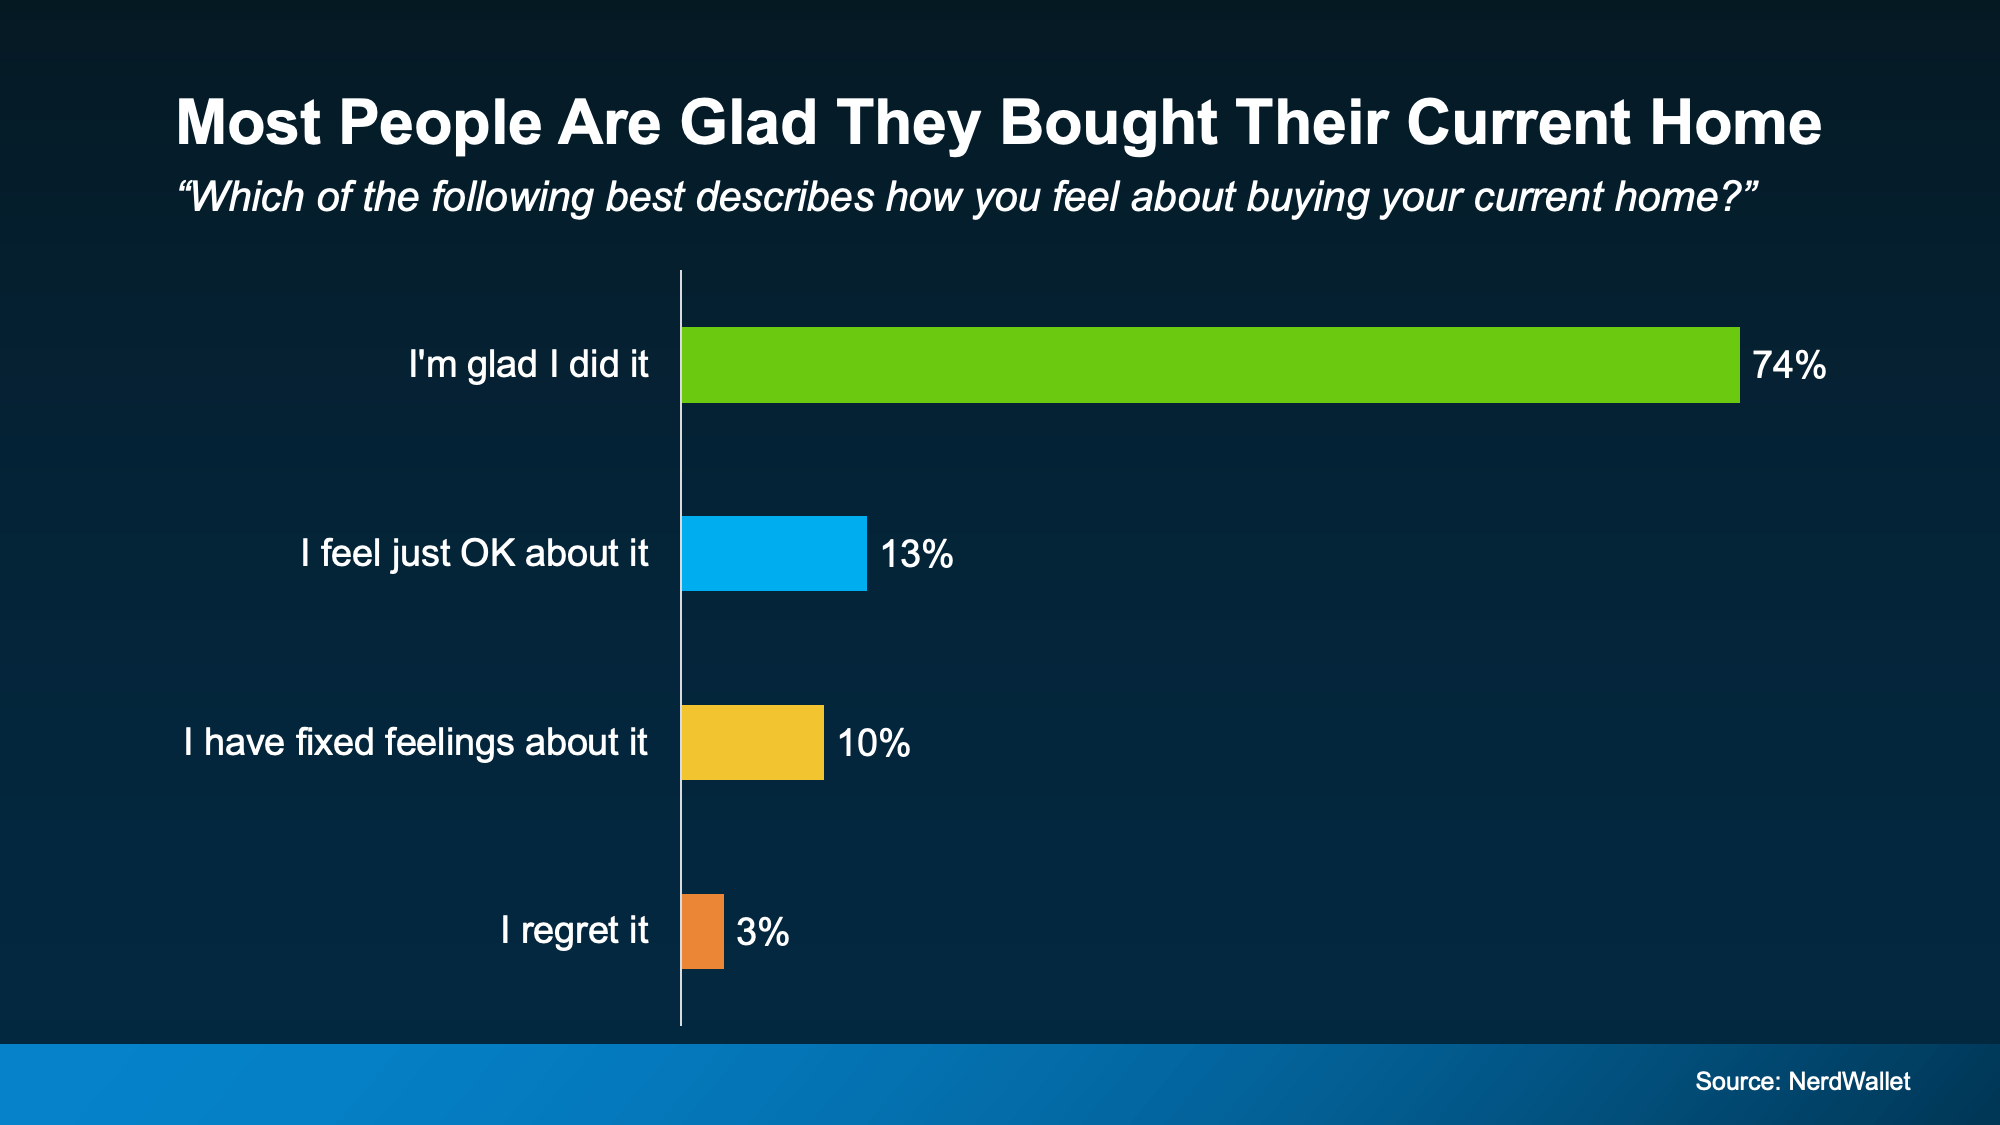
According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:

a graph with text on it

And here’s a big reason why so many people feel it was worth it, even now.

Homeownership Is a Long-Term Play

When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.

A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.

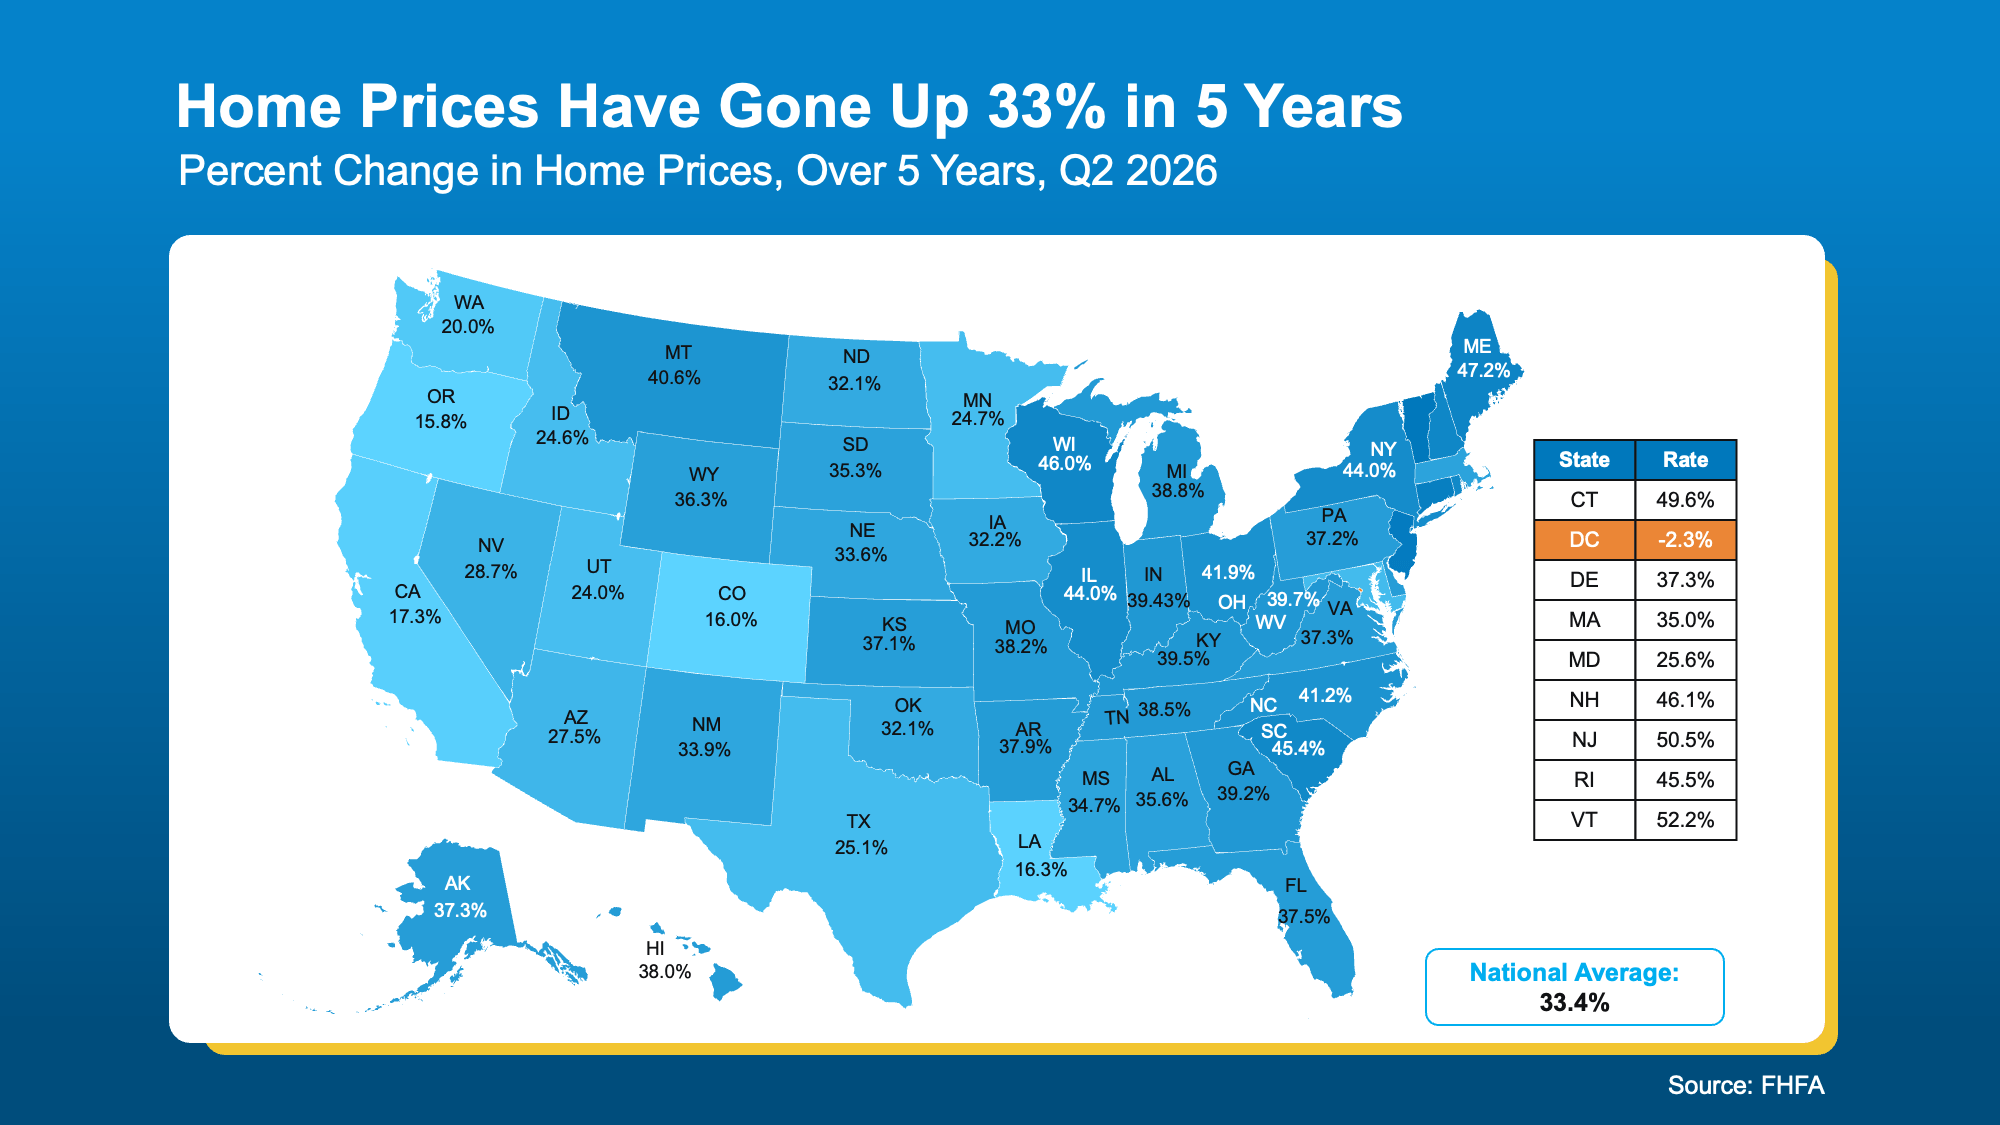
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):

a map of the united states

And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.

That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.

Now, Zoom Out Even Further

The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.

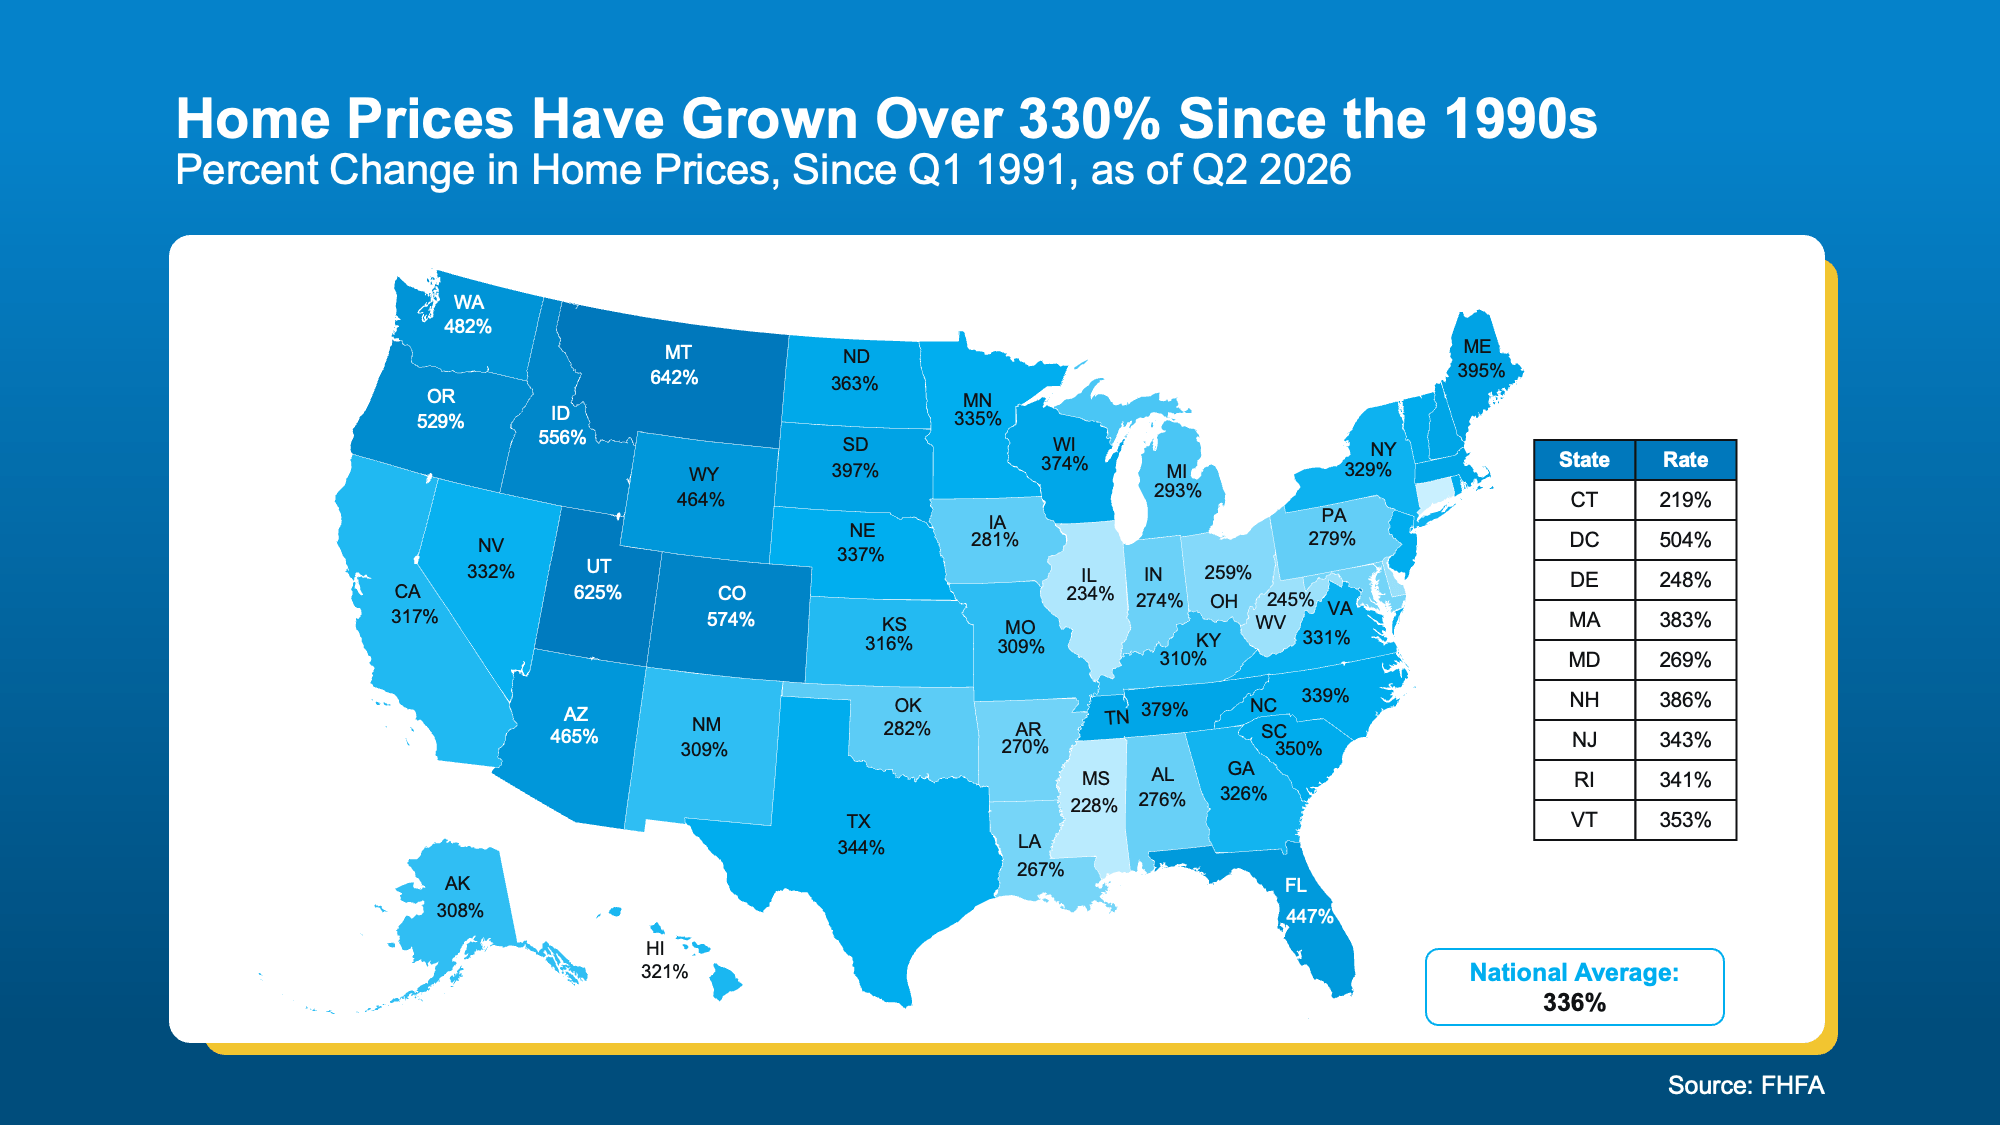
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):

a map of the united states with numbers and a number of states 

That doesn’t mean prices go up every single year. And it doesn’t mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.

What it does show is why trying to perfectly time the market can make you miss the bigger picture. 

Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains: 

“Your home’s equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .

If it’s time to upsize or downsize, you can use that cash for the down payment on your next home.”

Basically, if you can afford to do it, buying a home now could set you up for future moves.

And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.

Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.

Bottom Line

Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.

If you’re wondering whether buying makes sense for you right now, connect with an agent to look at the numbers together – and what owning a home could mean for you in the years ahead.

Myth vs. Reality: Does the Fed Control Mortgage Rates?

Myth vs. Reality: Does the Fed Control Mortgage Rates?

Myth vs. Reality: Does the Fed Control Mortgage Rates? Simplifying The Market

You’ve probably heard the Federal Reserve (the Fed) is raising rates again. And if you’re planning to buy or sell a house, you may be wondering what that means for you.

With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.

So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.

Why the Fed Is Raising Rates

It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.

So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.

  • MYTH: The Fed controls mortgage rates.

  • REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.

As NerdWallet explains:

“The Federal Reserve influences mortgage rates, but doesn’t set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve’s monetary policy is a factor, too . . .”

Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.

Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.

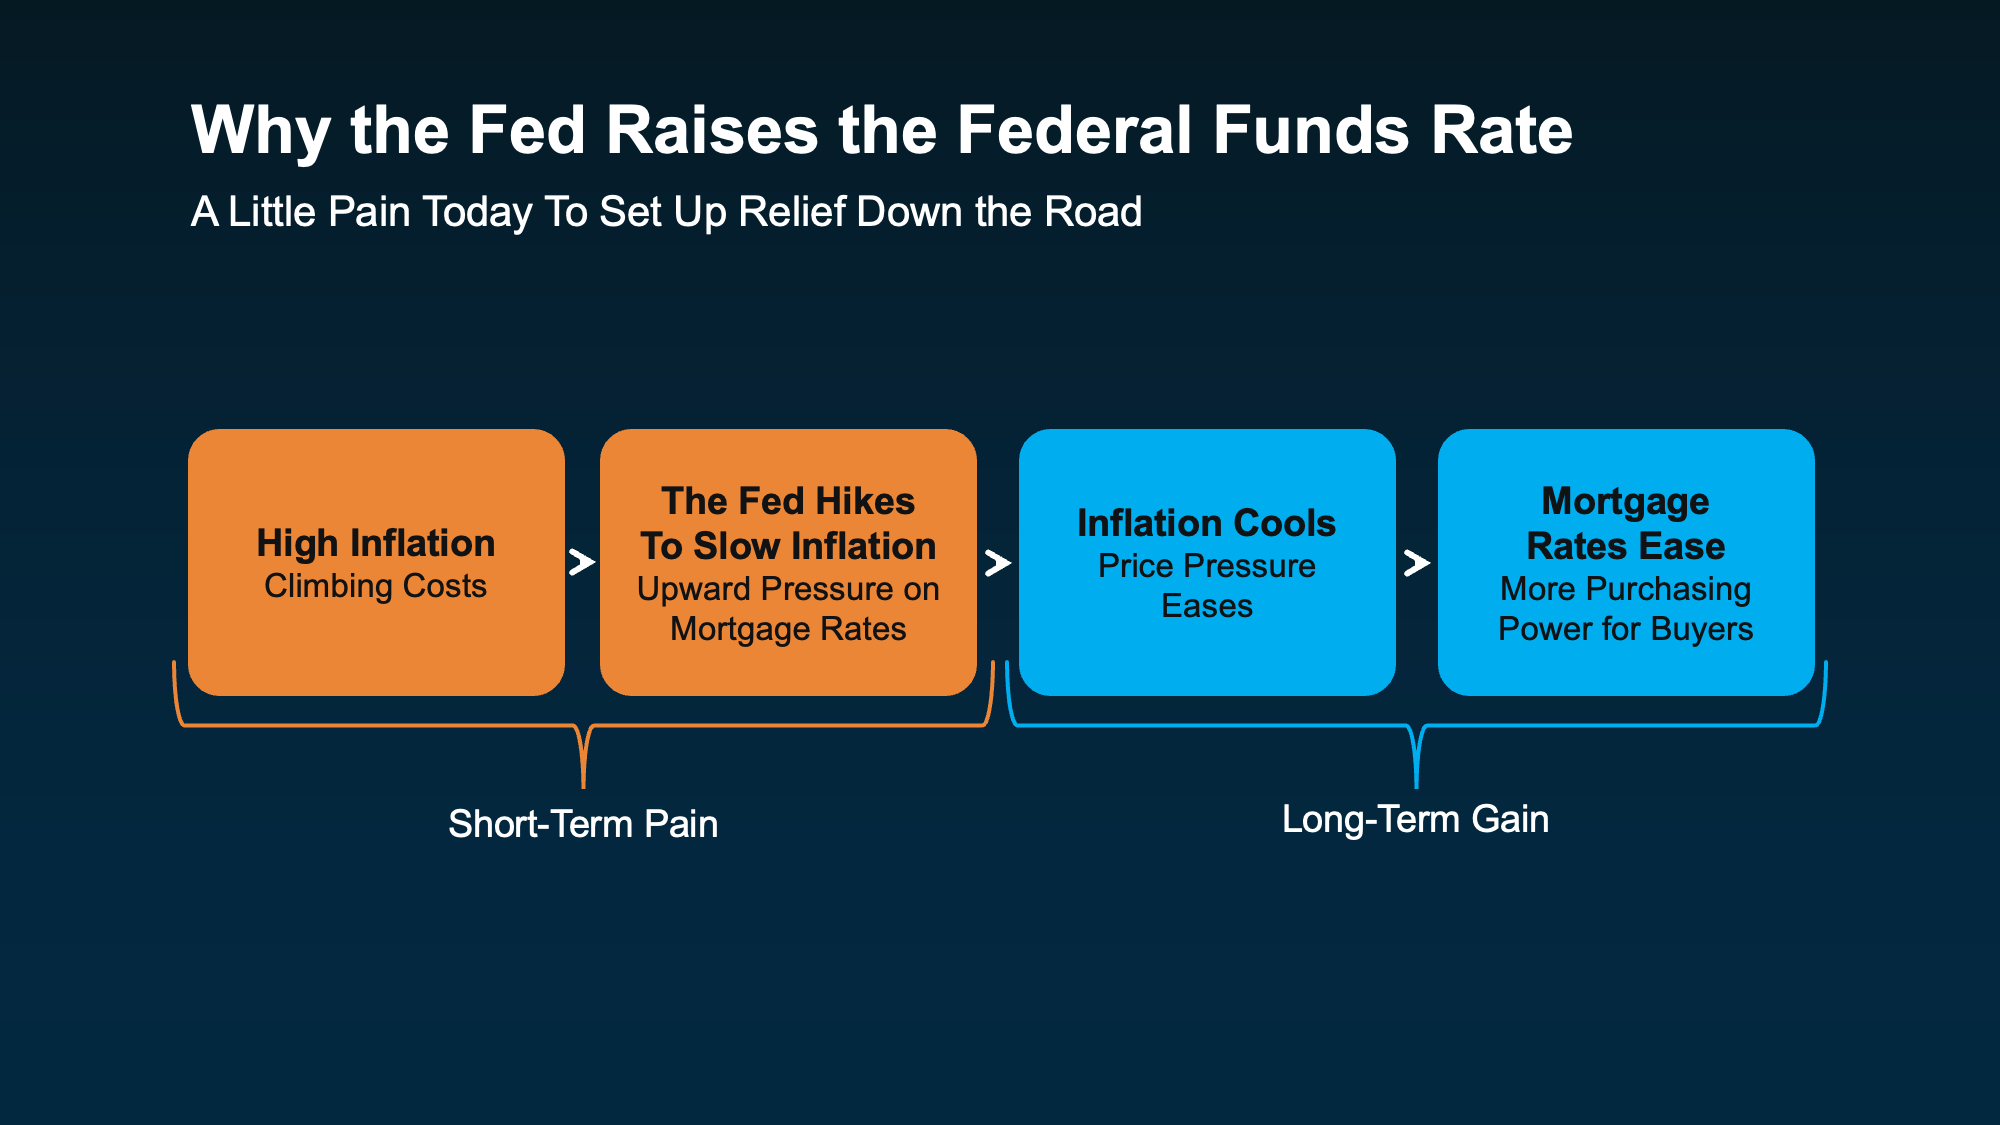
What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):

a diagram of a federal funds rate

Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.

There’s a Strong Possibility the Fed Will Hike Again This Year

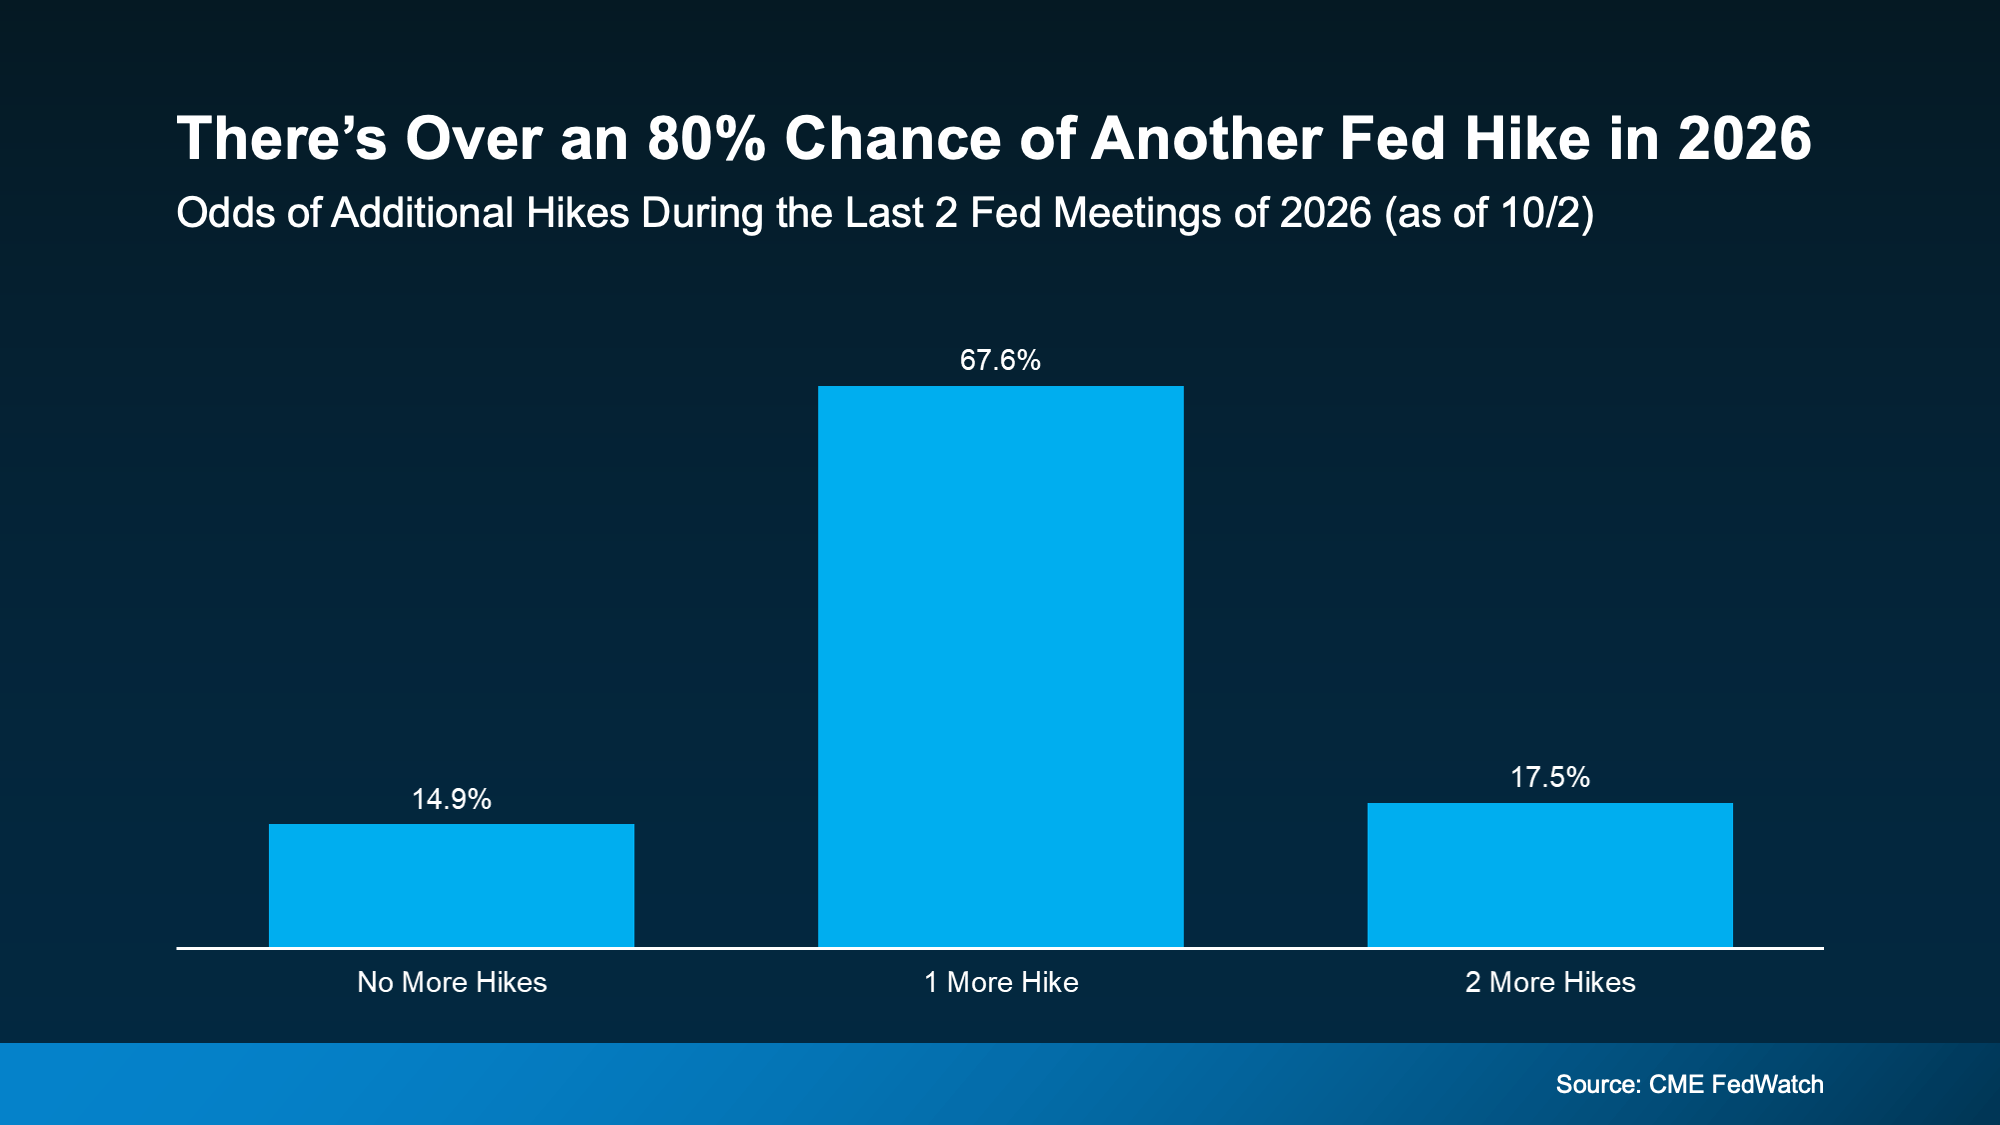
According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):

a graph of hikers with blue squares

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:

“Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control.“

And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:

  • PCE inflation dropped to 3.4%, down from 3.7% in July.

  • Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.

That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.

How To Make Your Move Work Right Now

While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.

  • If you’re buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you’re under contract, lock your rate so a jump before closing doesn’t raise your payment.

  • If you’re selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today’s buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.

Bottom Line

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today’s rates.

Two Moves That Can Get You Into Your First Home Sooner

Two Moves That Can Get You Into Your First Home Sooner

Two Moves That Can Get You Into Your First Home Sooner Simplifying The Market

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.

But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.

How Long Buying Really Takes

First, one quick definition. “Breaking even” is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

“Buyers should think about not just when they can afford to buy, but how long they’d need to stay before owning makes more financial sense than renting.“

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.

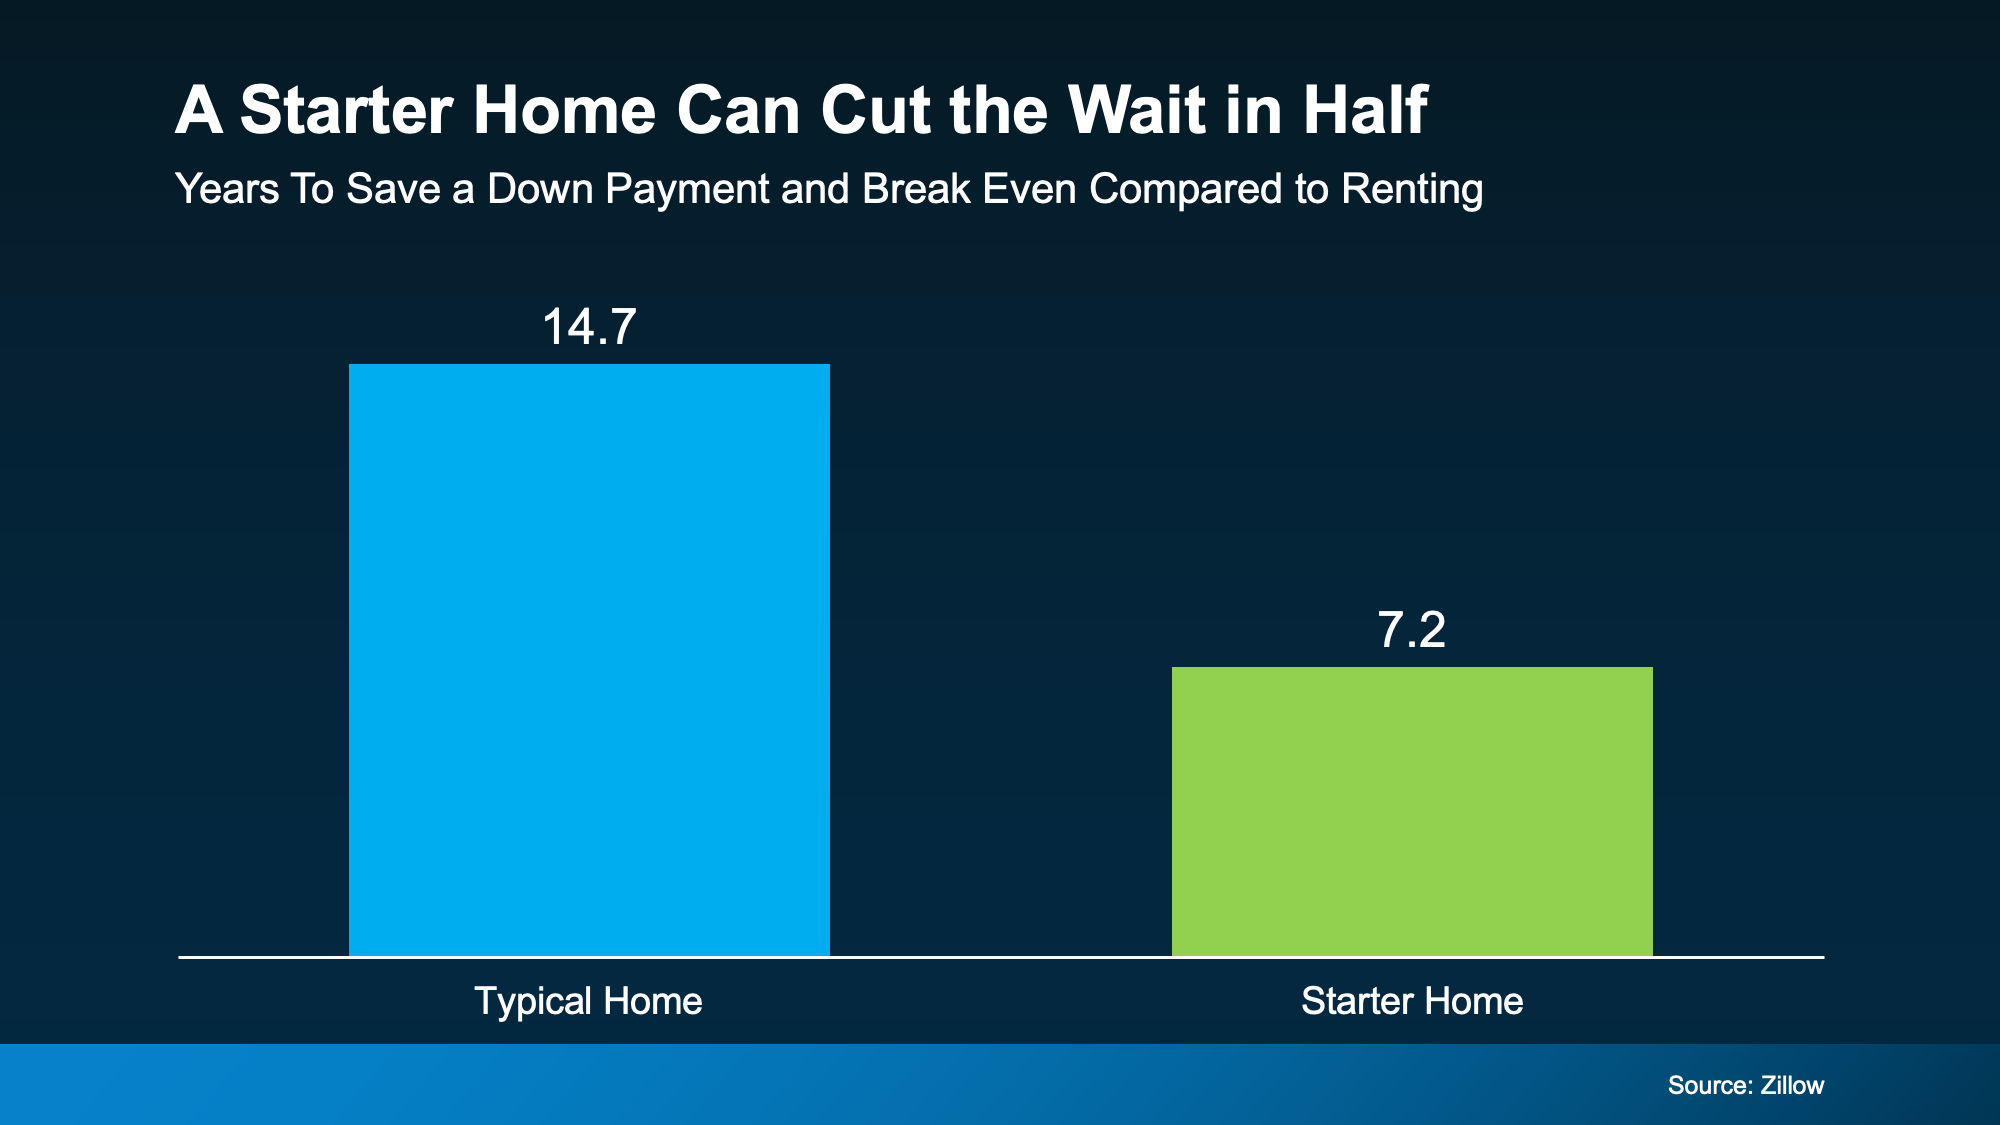
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that’s just under 15 years. But that math relies on two assumptions: that you’re buying a mid-priced home, and that you’re putting 20% down. 

Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. 

A Starter Home Can Get You There Twice as Fast

A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. 

Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.

Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):

a graph of a number of squares

That works out to about 4.6 years to save and 2.6 years to break even. It won’t erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.

You Usually Don’t Need To Put 20% Down

You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. 

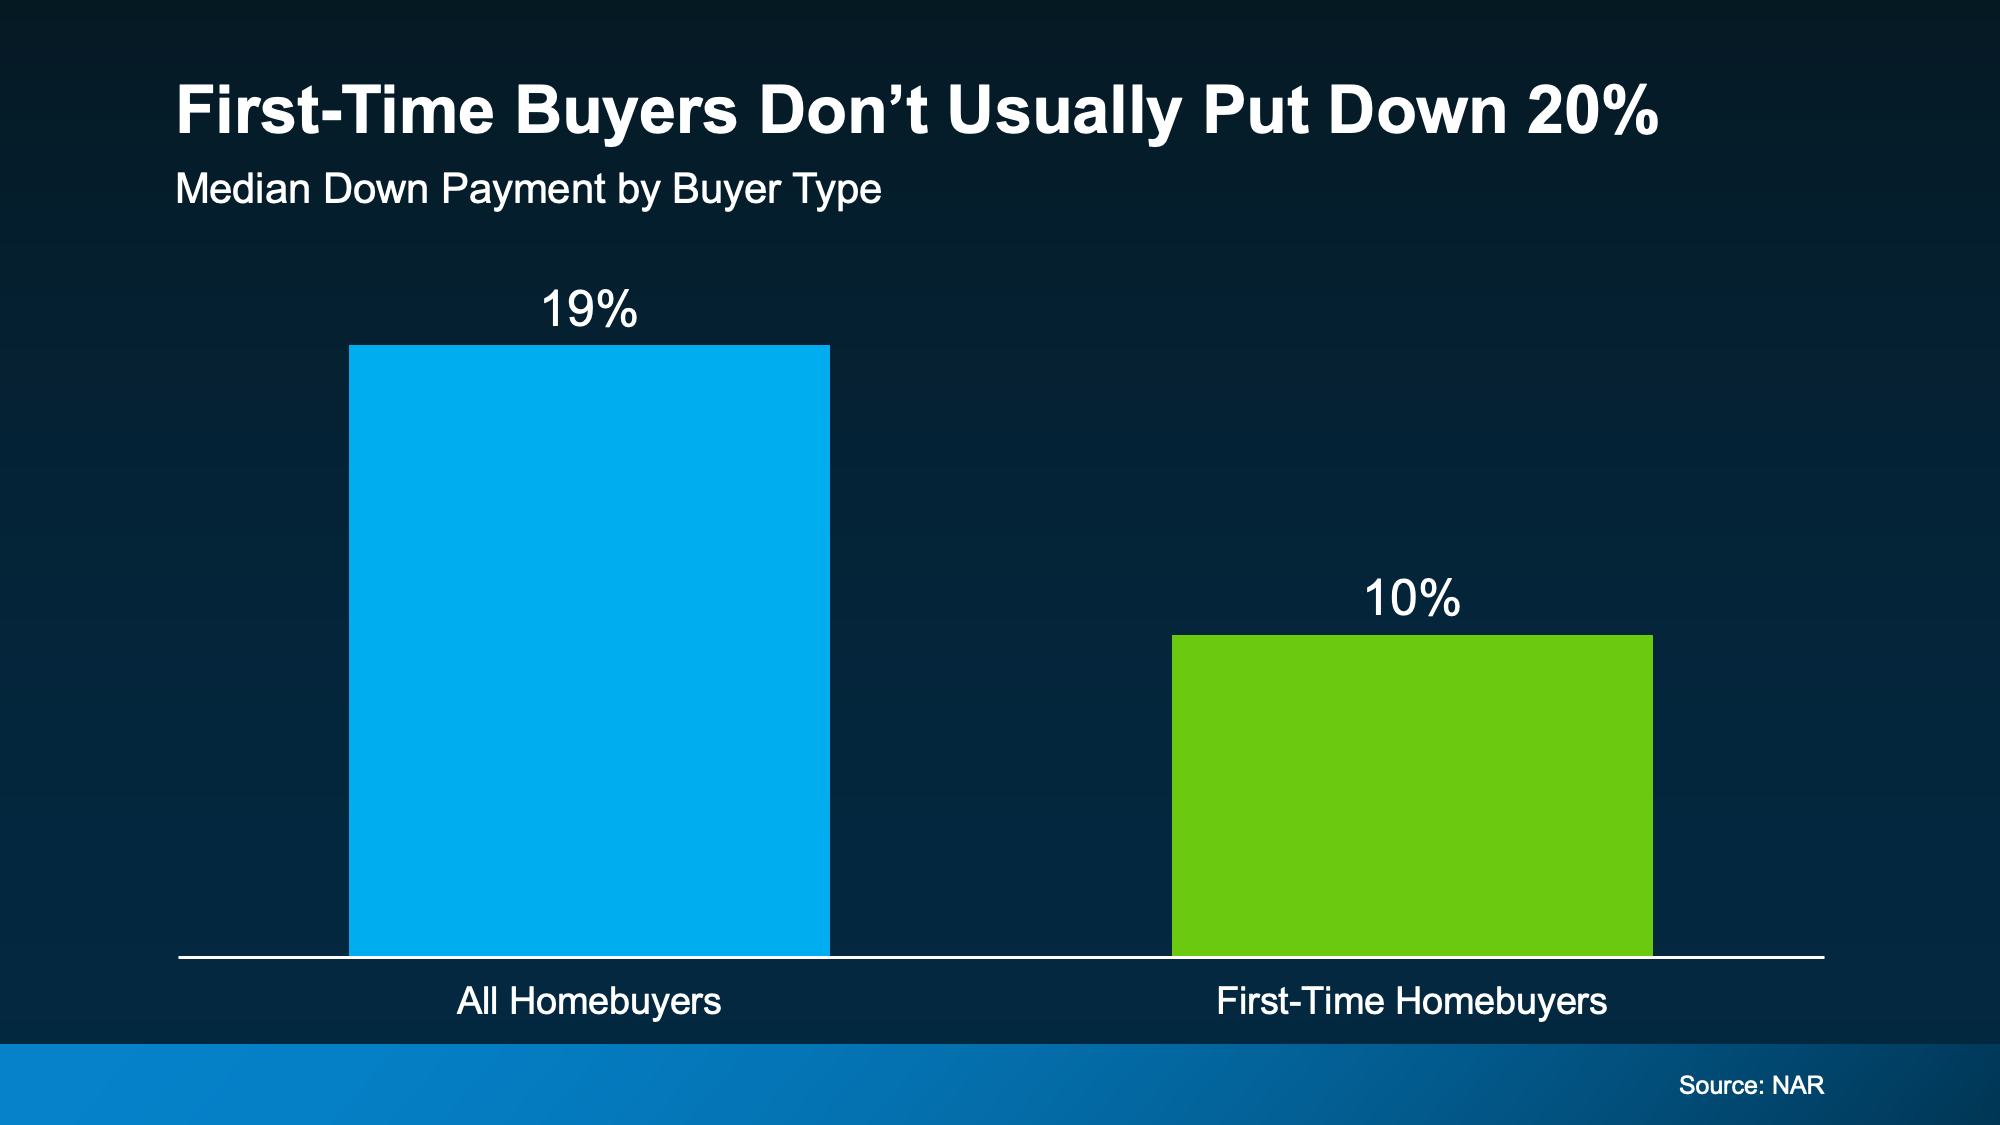
Most first-time buyers don’t put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):

a graph of a sales report

And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.

There’s help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

“Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase.”

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.

Bottom Line

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in your area could fit your budget? A local real estate agent can show you.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get. Simplifying The Market

You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember… 

That’s not necessarily the number you’d get. 

It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. 

What Determines Your Real Rate? 

Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. 

That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:

  • Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.

  • Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.

  • The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. 

  • The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. 

Even after you find a home you love, other things can have an impact too. For example:

  • A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.

  • Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. 

There’s a lot that can ultimately have an impact on your actual rate. 

Your First Step? Getting Pre-Approved.

If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. 

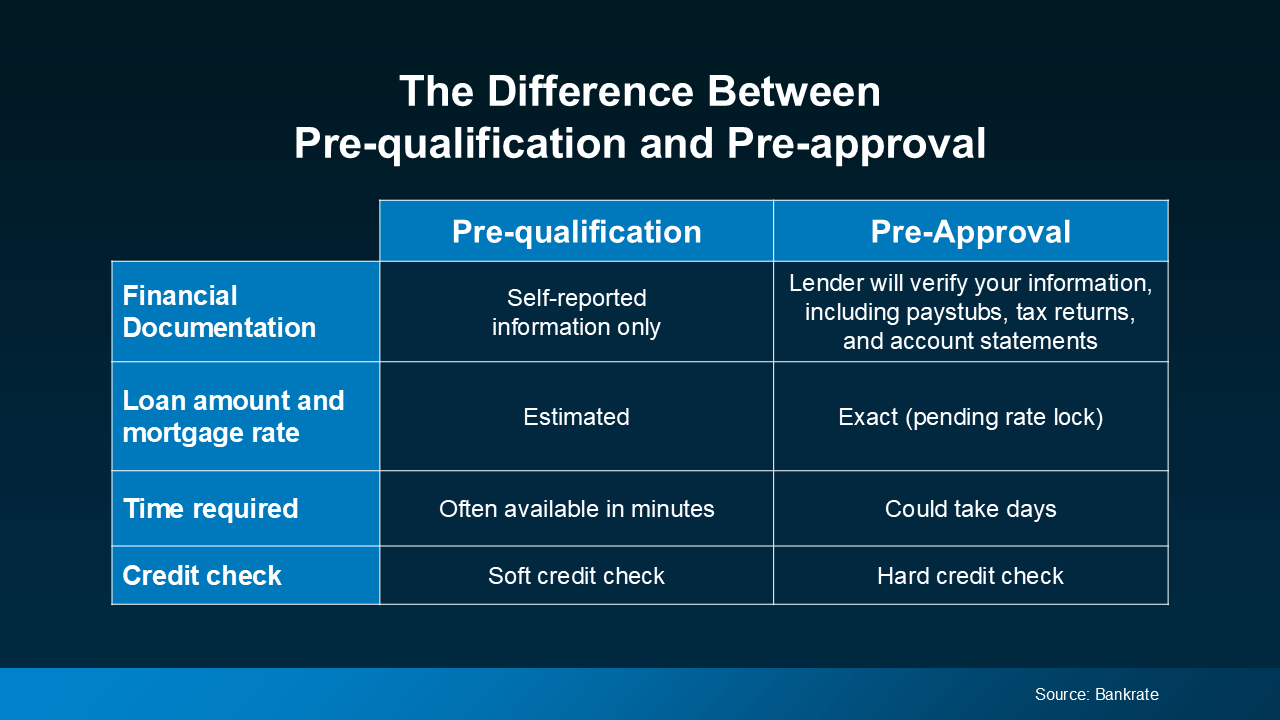
Your lender may recommend a pre-qualification and pre-approval:

  • Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. 

  • On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. 

Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:

a blue and white chart with white text

How To Get Ready for the Conversation

Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: 

  • What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? 

  • Will I get any tax advantages by buying a home – and what are they? 

  • What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?

  • How will rate changes in either direction affect me?

Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.  

Bottom Line

Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. 

With the right help, you can find out what your real rate is – and where it can take you.

Pin It on Pinterest