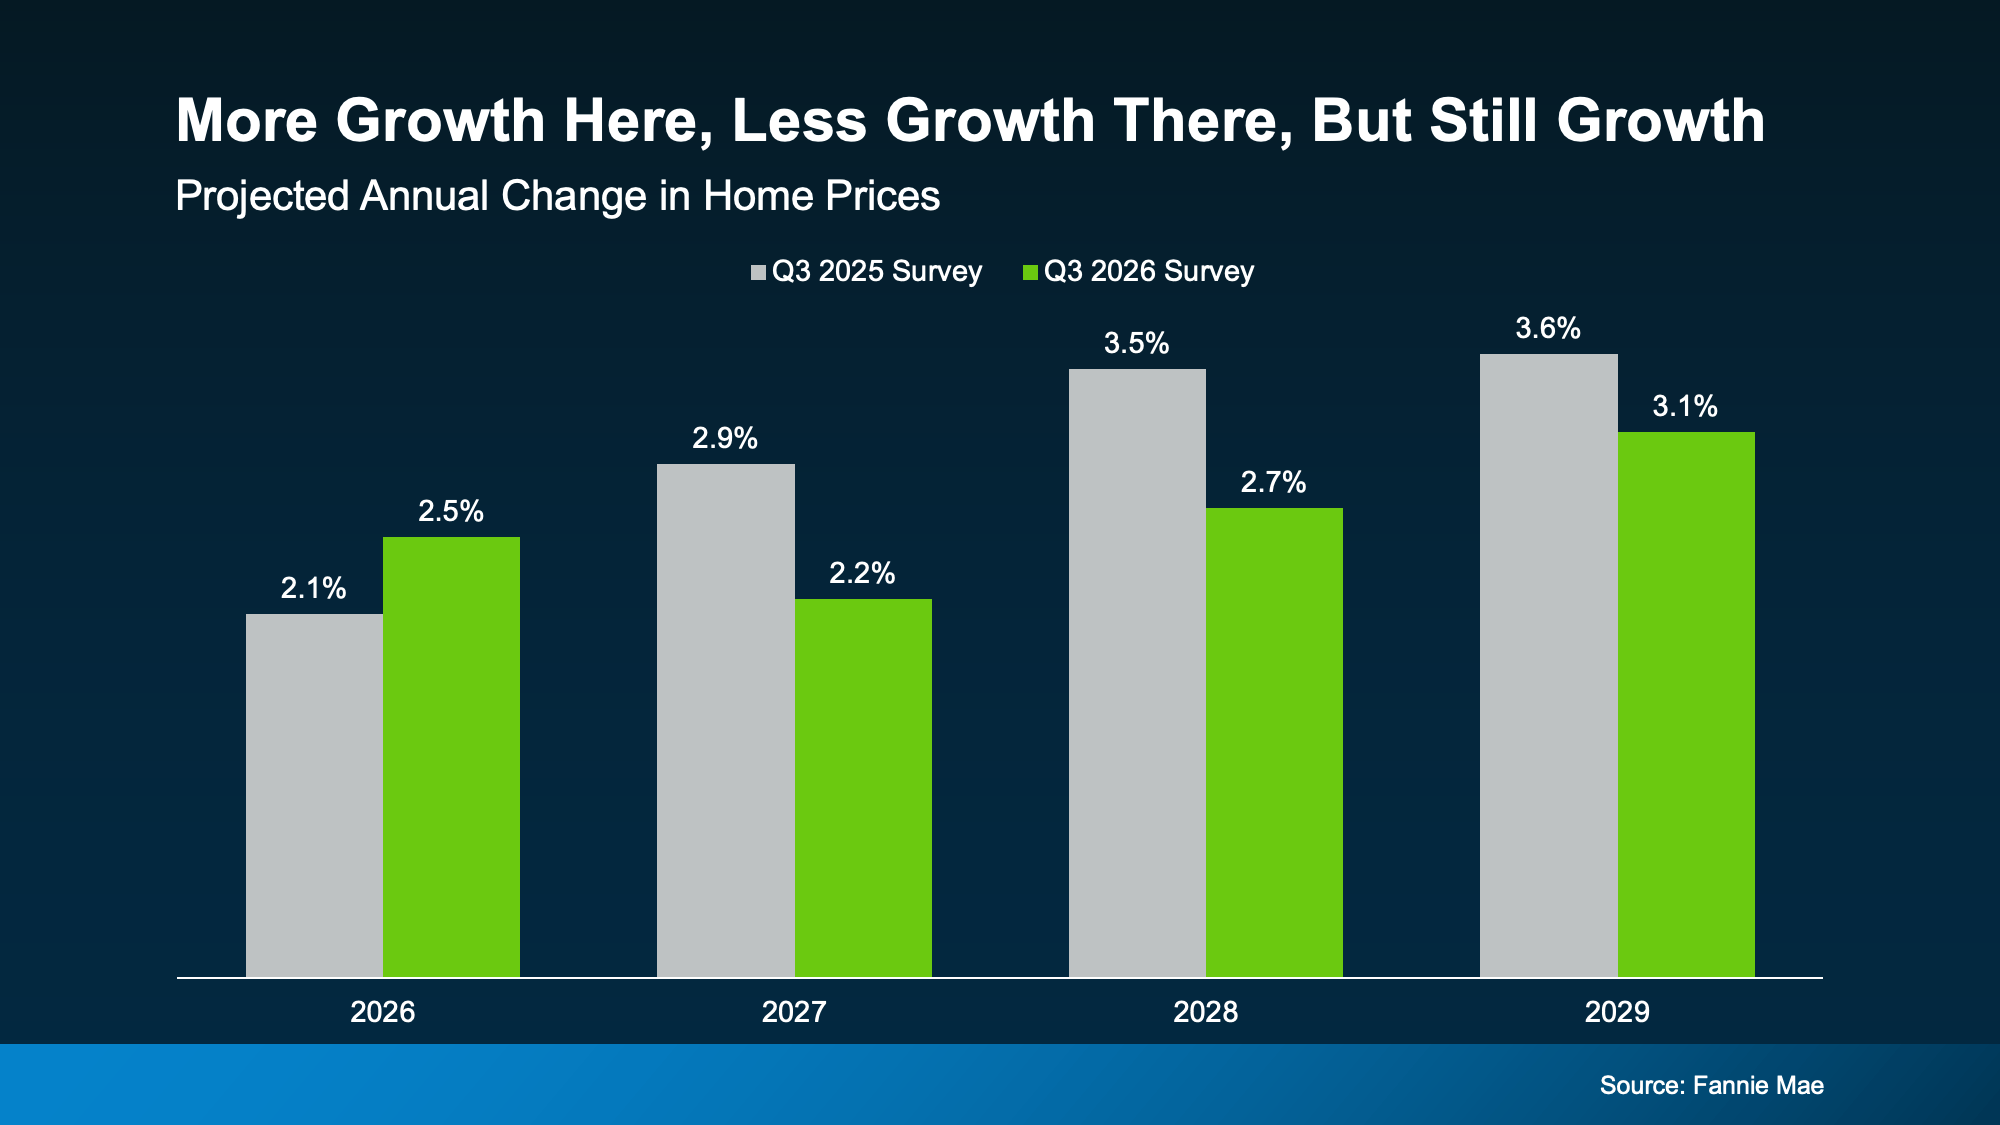
The Housing Market Is on Solid Ground, Even with More Foreclosures

The Housing Market Is on Solid Ground, Even with More Foreclosures
The Housing Market Is on Solid Ground, Even with More Foreclosures Simplifying The Market

It’s been nearly two decades since the 2008 housing crash, but the word “foreclosure” can still make people uneasy. And if you’re planning a move, you may be wondering if more foreclosures will flood the market with homes for sale – especially if you’ve seen the headlines lately.

Buyers may be hoping for a rush of bargains. Sellers may be bracing for more competition. The latest data points to neither, and knowing why can help you plan your next move with confidence.

A Modest Rise from a Low Starting Point

Completed foreclosures are up 33% from last year, according to ATTOM. That sounds like a big leap, but context helps.

Even with that increase, foreclosures are still about 26% below where they were in the first half of 2020.

Zoom out further, and today’s activity is a small fraction of what the market saw during the 2008 crash. Lenders completed about 28,000 foreclosures in the first half of 2026, according to ATTOM. Compare that to the crash years in red, when lenders often completed more than 200,000 in the span of a few months (see graph below):
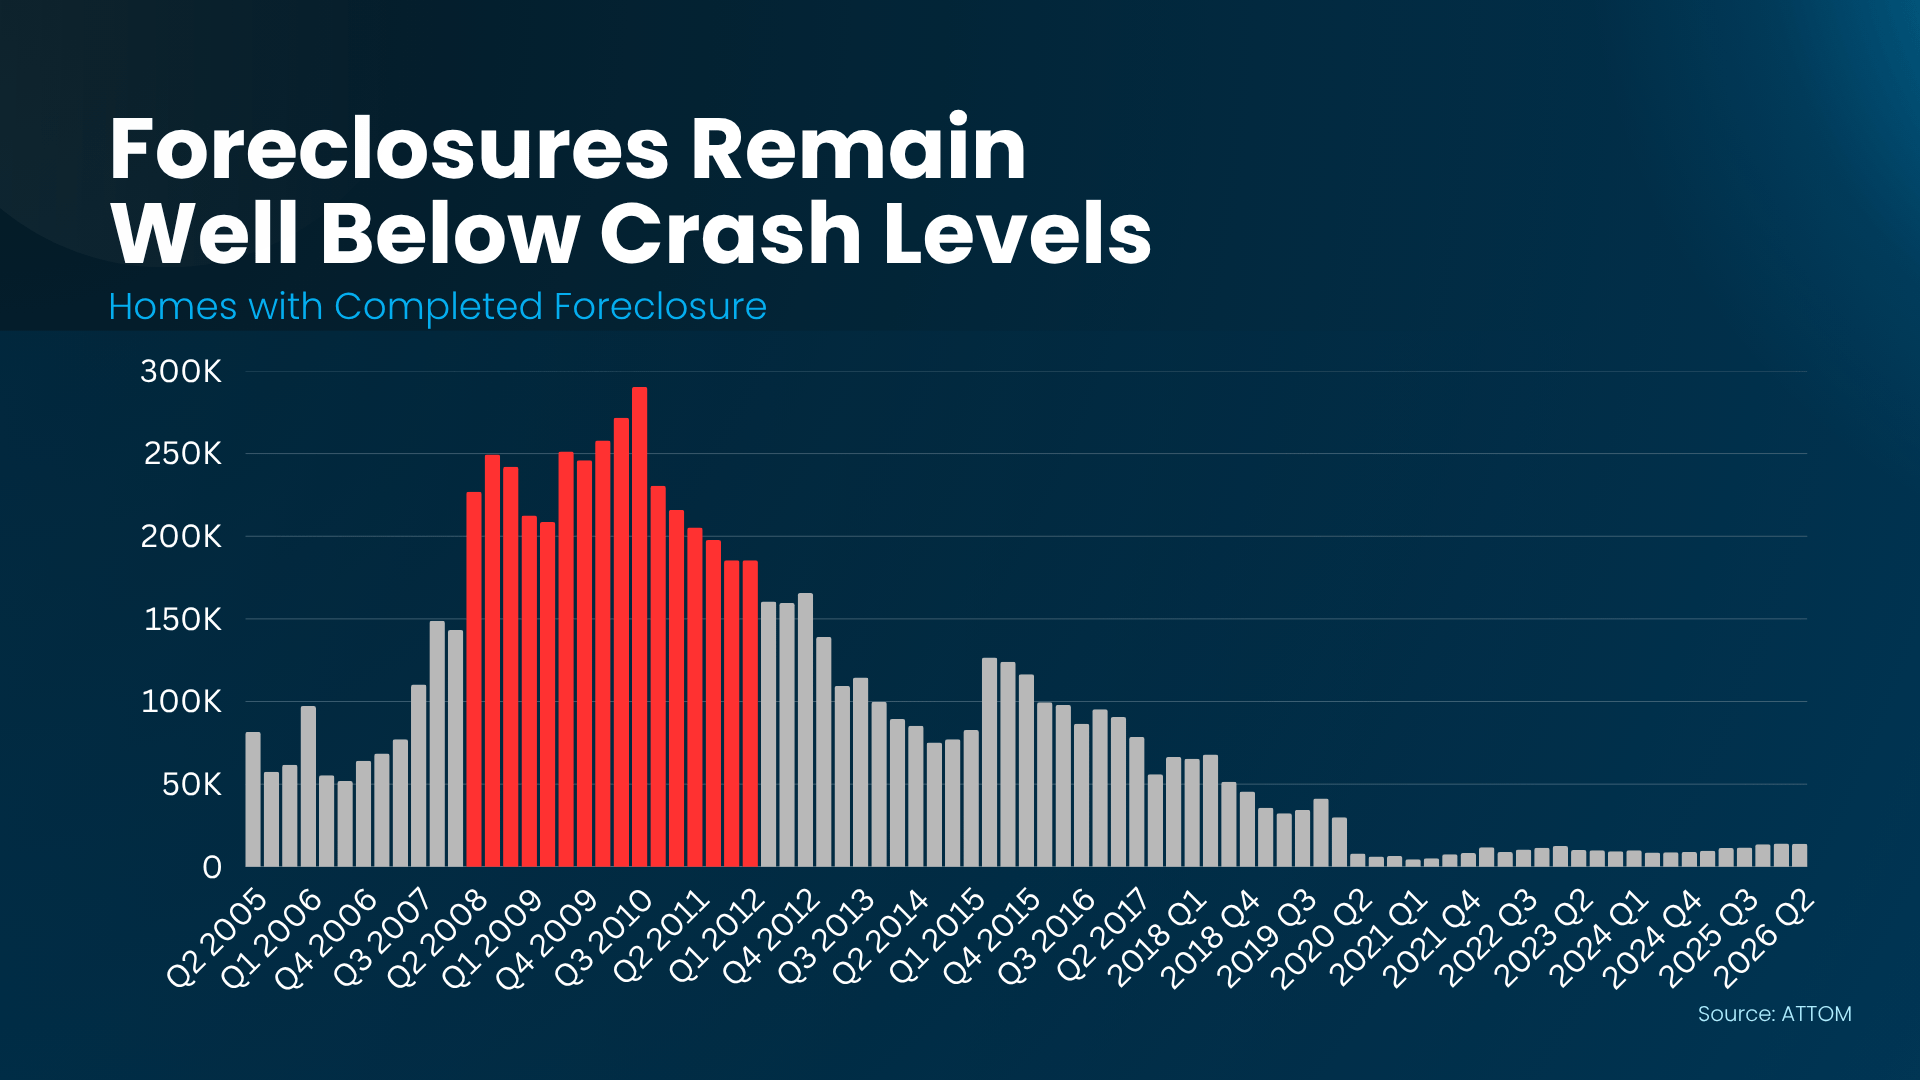
a graph of a crash

Experts say today’s numbers reflect a housing market that’s still in good shape. As Rob Barber, CEO at ATTOM, explains:

“While some homeowners are still facing financial challenges, overall foreclosure volumes remain well below historical norms and the broader housing market continues to demonstrate resilience.”

And here’s why we can absorb the slight uptick in foreclosures we are seeing. 

Homes for Sale Are Back in a Balanced Range

During the crash, a lot of homeowners either lost their homes to foreclosure or were forced to sell, which left the market overwhelmed with houses for sale. That isn’t happening now.

One way to see this is through months’ supply, which measures how long it would take to sell every home on the market at the current pace. Four to six months is considered balanced.

Right now, it’s about 4.8 months, according to the National Association of Realtors (NAR). That’s pretty well-balanced, and less than half of where it peaked around the last crash (see graph below):
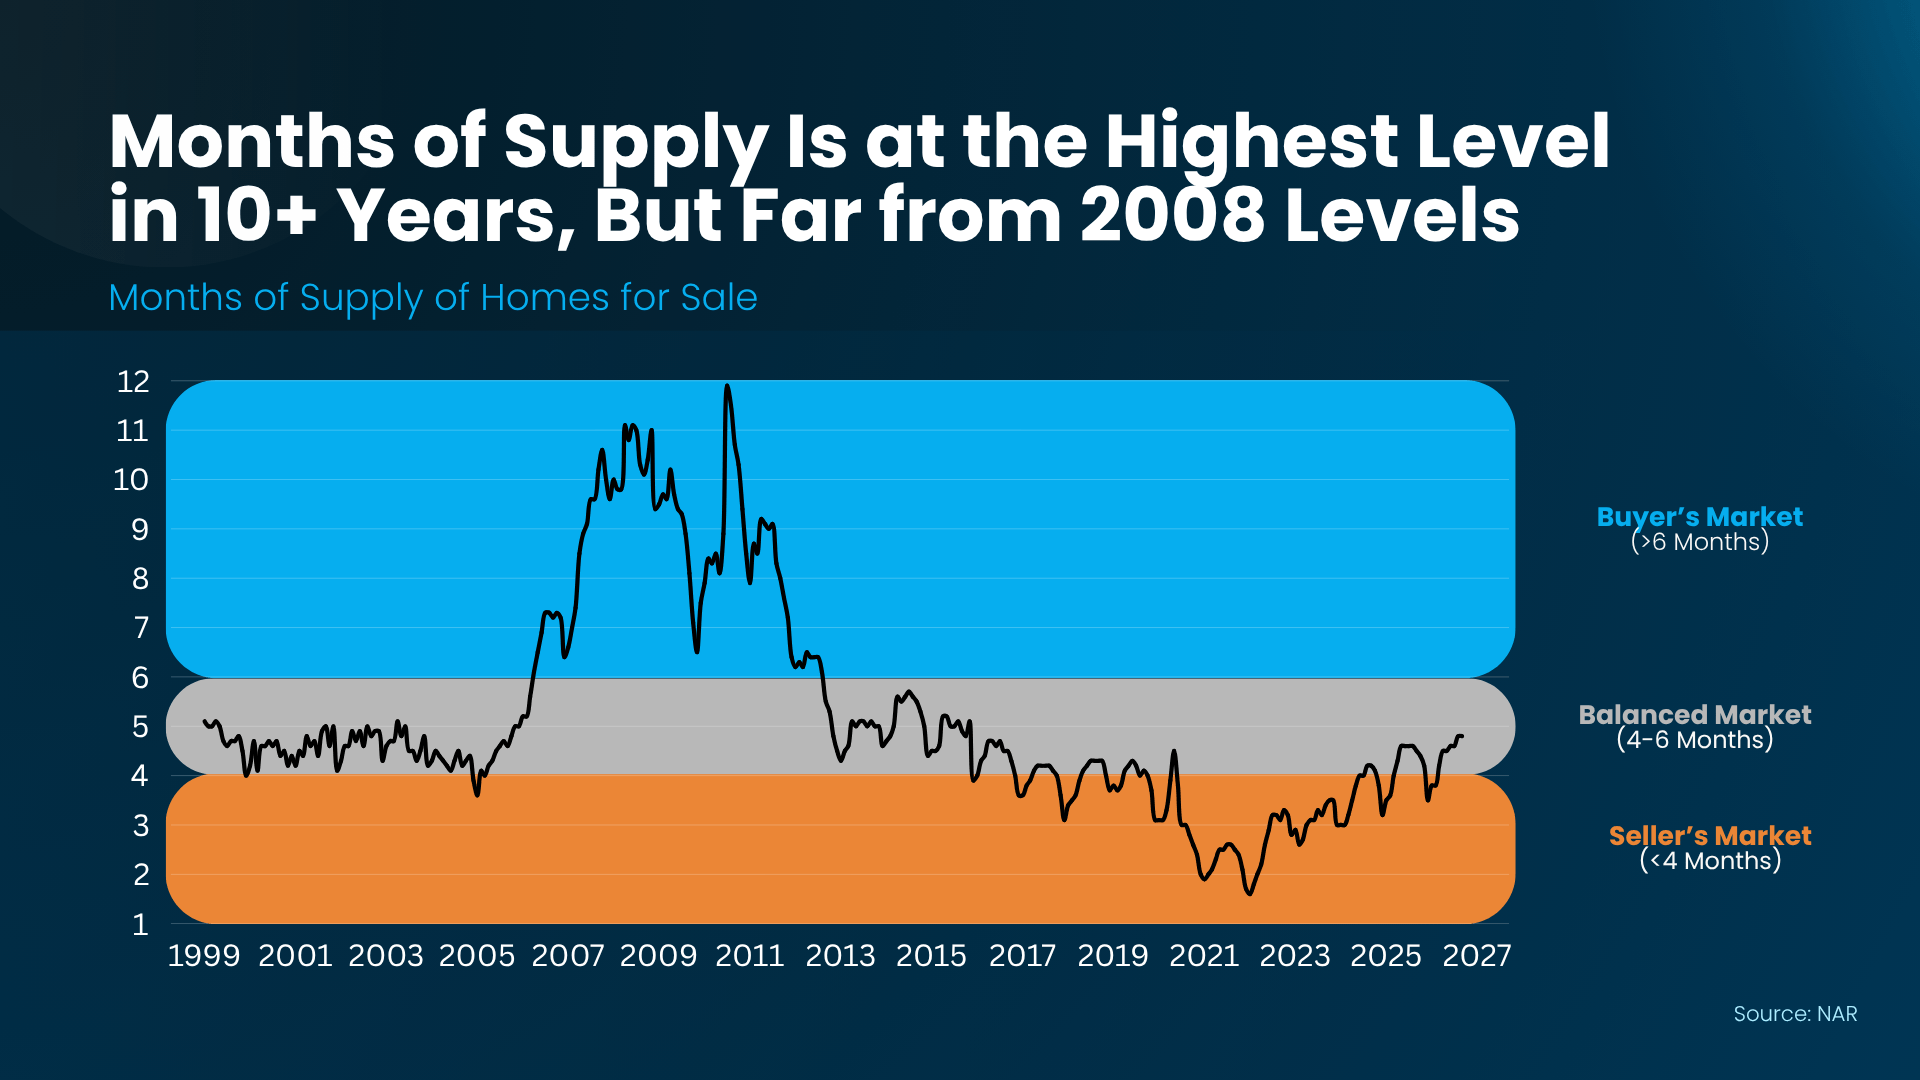
a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

If foreclosures were really surging, you’d see it in the number of homes for sale. As Logan Mohtashami, Lead Analyst at HousingWire, explains:

“. . . a surge of actual foreclosures in 2026 would have easily put the inventory data much higher in 2026.”

Equity Gives Today’s Homeowners Options

Equity is a big reason there’s no surge of distressed sales. Data from the Census Bureau and ATTOM shows nearly two in three homeowners have paid off their mortgage or have more than 50% equity. And Cotality says the average homeowner has about $310,000 in equity.

If a homeowner with equity hits a rough patch, they can usually sell their house, pay off the loan, and walk away with money in their pocket instead of facing foreclosure. That’s an option many people didn’t have during the crash. According to HousingWire, nearly one in four homes were underwater back in 2010.

Being underwater means owing more on your mortgage than your home is worth, which makes selling a lot harder. Today, just 2% of homeowners are considered seriously underwater (see graph below):
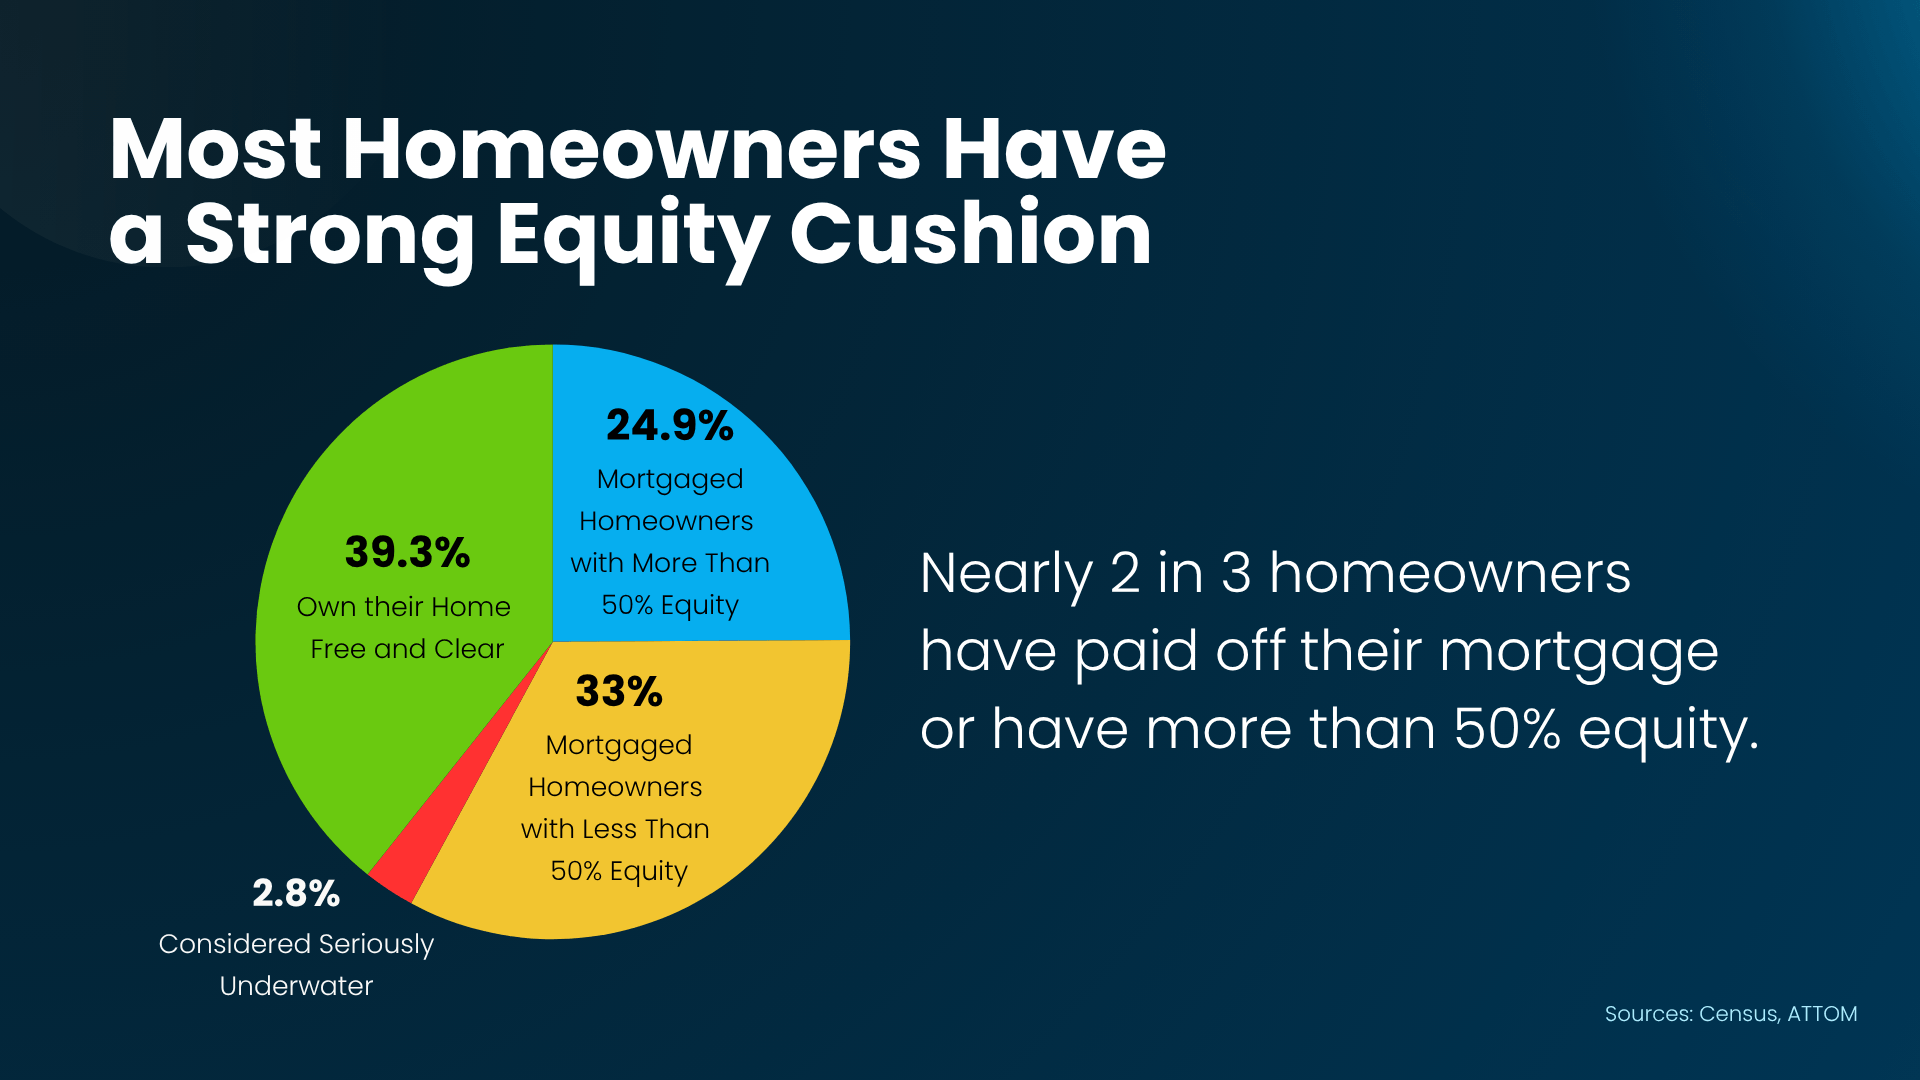
a pie chart with text on it
Not every homeowner has that kind of equity, but most do, and that’s what puts a ceiling on how high foreclosures can go.

Bottom Line

If rising foreclosures have you questioning where the housing market is headed, the data says it’s in good shape. The supply of homes for sale is balanced, and most homeowners have plenty of equity.

Have questions about what you’re seeing online, your local market, or about how much equity you have? Talk to a local real estate agent.
Who’s Buying Homes with Cash Right Now?

Who’s Buying Homes with Cash Right Now?

Who’s Buying Homes with Cash Right Now? Simplifying The Market

Ryan Serhant, CEO of SERHANT, says there isn’t just 1 housing market right now. There are really 4: cash buyers, buyers who need a mortgage, homeowners with low mortgage rates, and builders.

Today, let’s zoom in on the 1st group – cash buyers.

According to the National Association of Realtors (NAR), 27% of homes sold in September were bought with all cash. That’s more than 1 in 4 buyers. And that’s a pretty big number, especially when so many people are struggling with affordability.

So where is all that cash coming from? When you hear a number like that, it’s easy to picture wealthy investors buying up houses left and right. But that’s not necessarily the case. Some of those cash buyers are actually homeowners who’ve built up enough equity to buy their next home outright.

Here’s what you should know about who’s paying cash and what that really means for the market.

Who’s Paying Cash?

Cash buyers tend to fall into a few groups, according to NAR:

  • Homeowners who sold a house and are using that money to buy their next one

  • People buying a 2nd home

  • Investors

So, it’s not all those big investors social media talks about. That 1st group may include people a lot more like you. Here’s how. According to Cotality, the average homeowner with a mortgage has about $310,000 in equity.

That’s a big deal right now. Many homeowners feel stuck because they don’t want to give up the low mortgage rate they have today. But once they learn they may have enough equity to move and pay cash for their next home, today’s rates don’t matter nearly as much. Because buying in all cash means…

  • No monthly mortgage payment

  • No need to borrow at today’s mortgage rates

  • No loan approval process, so you may be able to close faster

And even if the equity won’t cover the whole purchase, putting more of it toward the next home means borrowing less. That can mean a smaller monthly payment, too.

But cash buyers like this are more common in some places than others. And how big of a segment of your local market this is, is going to depend on where you live.

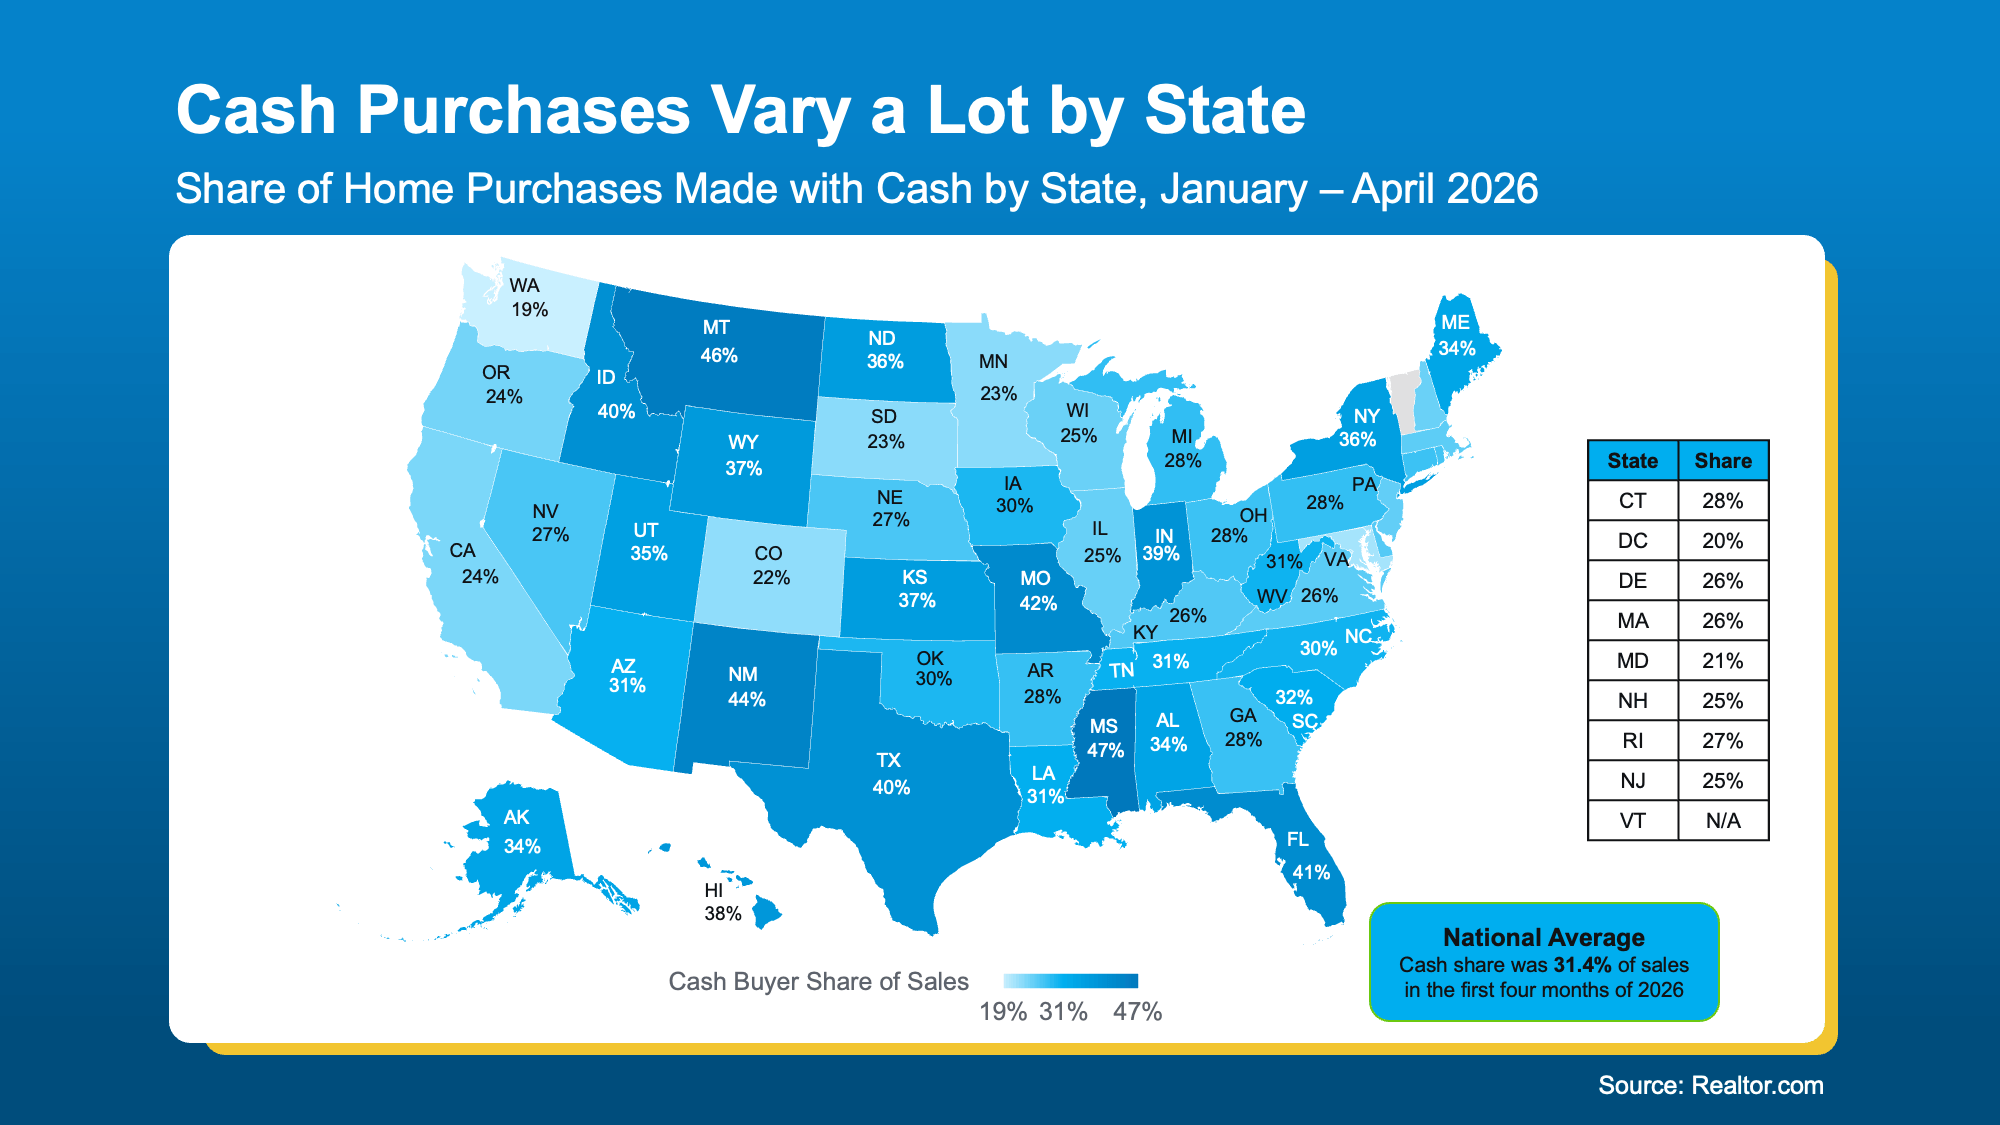
For example, Realtor.com data shows cash buyers made up almost 47% of sales in Mississippi and 46% in Montana earlier this year (see map below).

Where does your state fall?

a map of the united states

According to Realtor.com, the states with the most cash buyers reflect “a mix of affordability, wealth and buyer demographics.” Think places with lower home prices, or lots of retirees and 2nd-home buyers.

So, depending on where you live, you may see a lot more (or a lot fewer) cash buyers than the national number suggests. An agent who knows your area can tell you who’s actually buying near you.

Most Buyers Are Still Using a Mortgage

And if all of this has you thinking everyone’s paying cash, they’re not. If you’re planning to buy and need a mortgage, you’re actually in the majority.

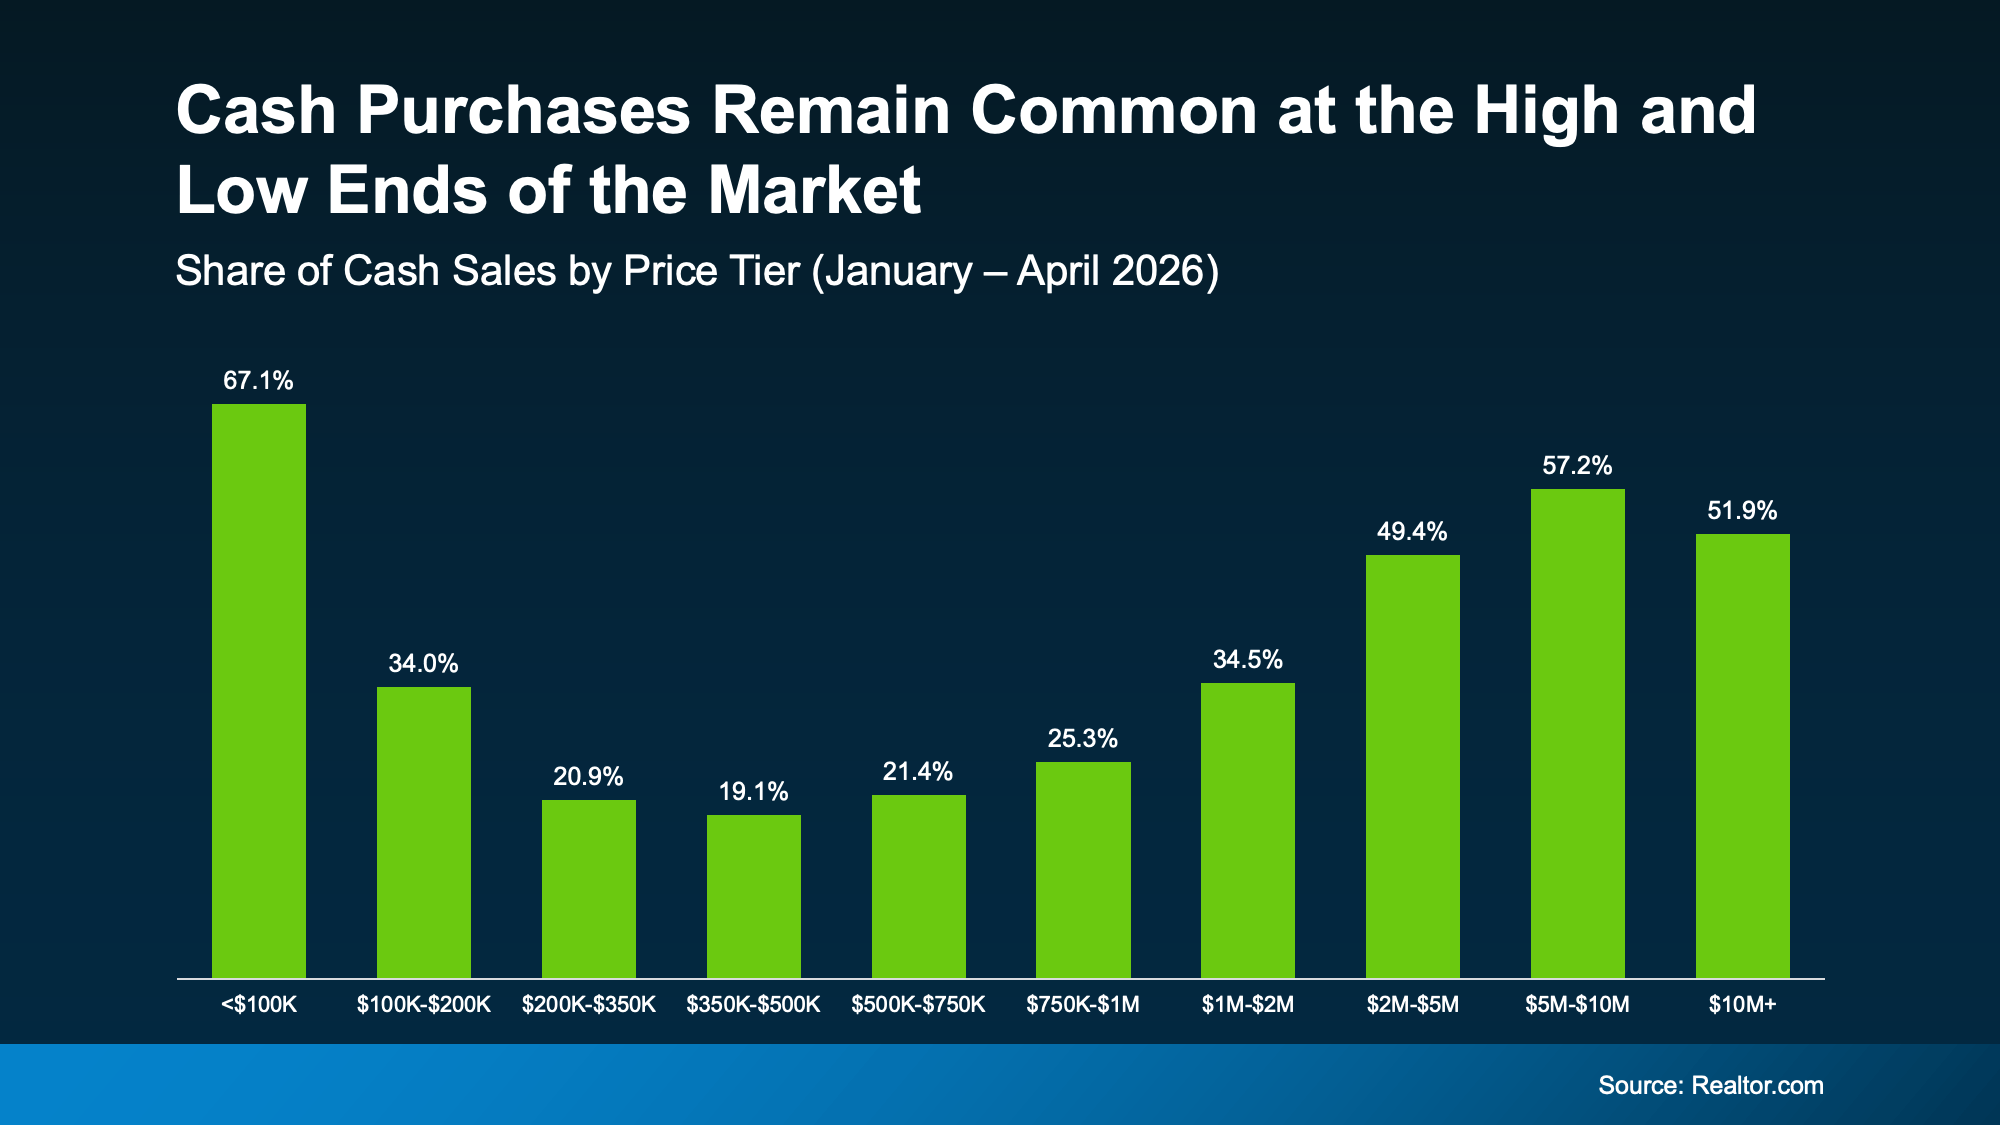
Based on NAR’s numbers, nearly 3 out of 4 home purchases still involve financing. And for homes priced between $200,000 and $750,000, only about 1 in 5 sold for cash, according to Realtor.com (see graph below):

a graph of green bars

That means most people buying in that price range are financing their purchase, too. So, there’s no need to assume you’re at a disadvantage just because you’re using a loan.

Cash Buyers and Your Move

So, what does all this mean for you? Maybe more than you think.

If you already own a house, you may have enough equity to make your next move more affordable than you realize. And if you’re buying with a mortgage, remember, you’re in good company. Most buyers are financing their purchases, too.

The takeaway? Don’t make assumptions about what’s possible based on how other people are buying homes. What really matters is your equity, your budget, and what’s happening in your local market.

Bottom Line

Cash buyers are a meaningful part of today’s market, but they aren’t the whole market.

Whether you’re hoping to put your equity to work or you’re buying with a mortgage, a local real estate agent can help you see how much equity you have, who’s buying in your area, and what that means for your next move.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In. Simplifying The Market

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.

So, what do the forecasts actually say?

Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.

What the Newest Numbers Actually Say

The panel’s latest forecast has prices climbing every single year through at least 2030.

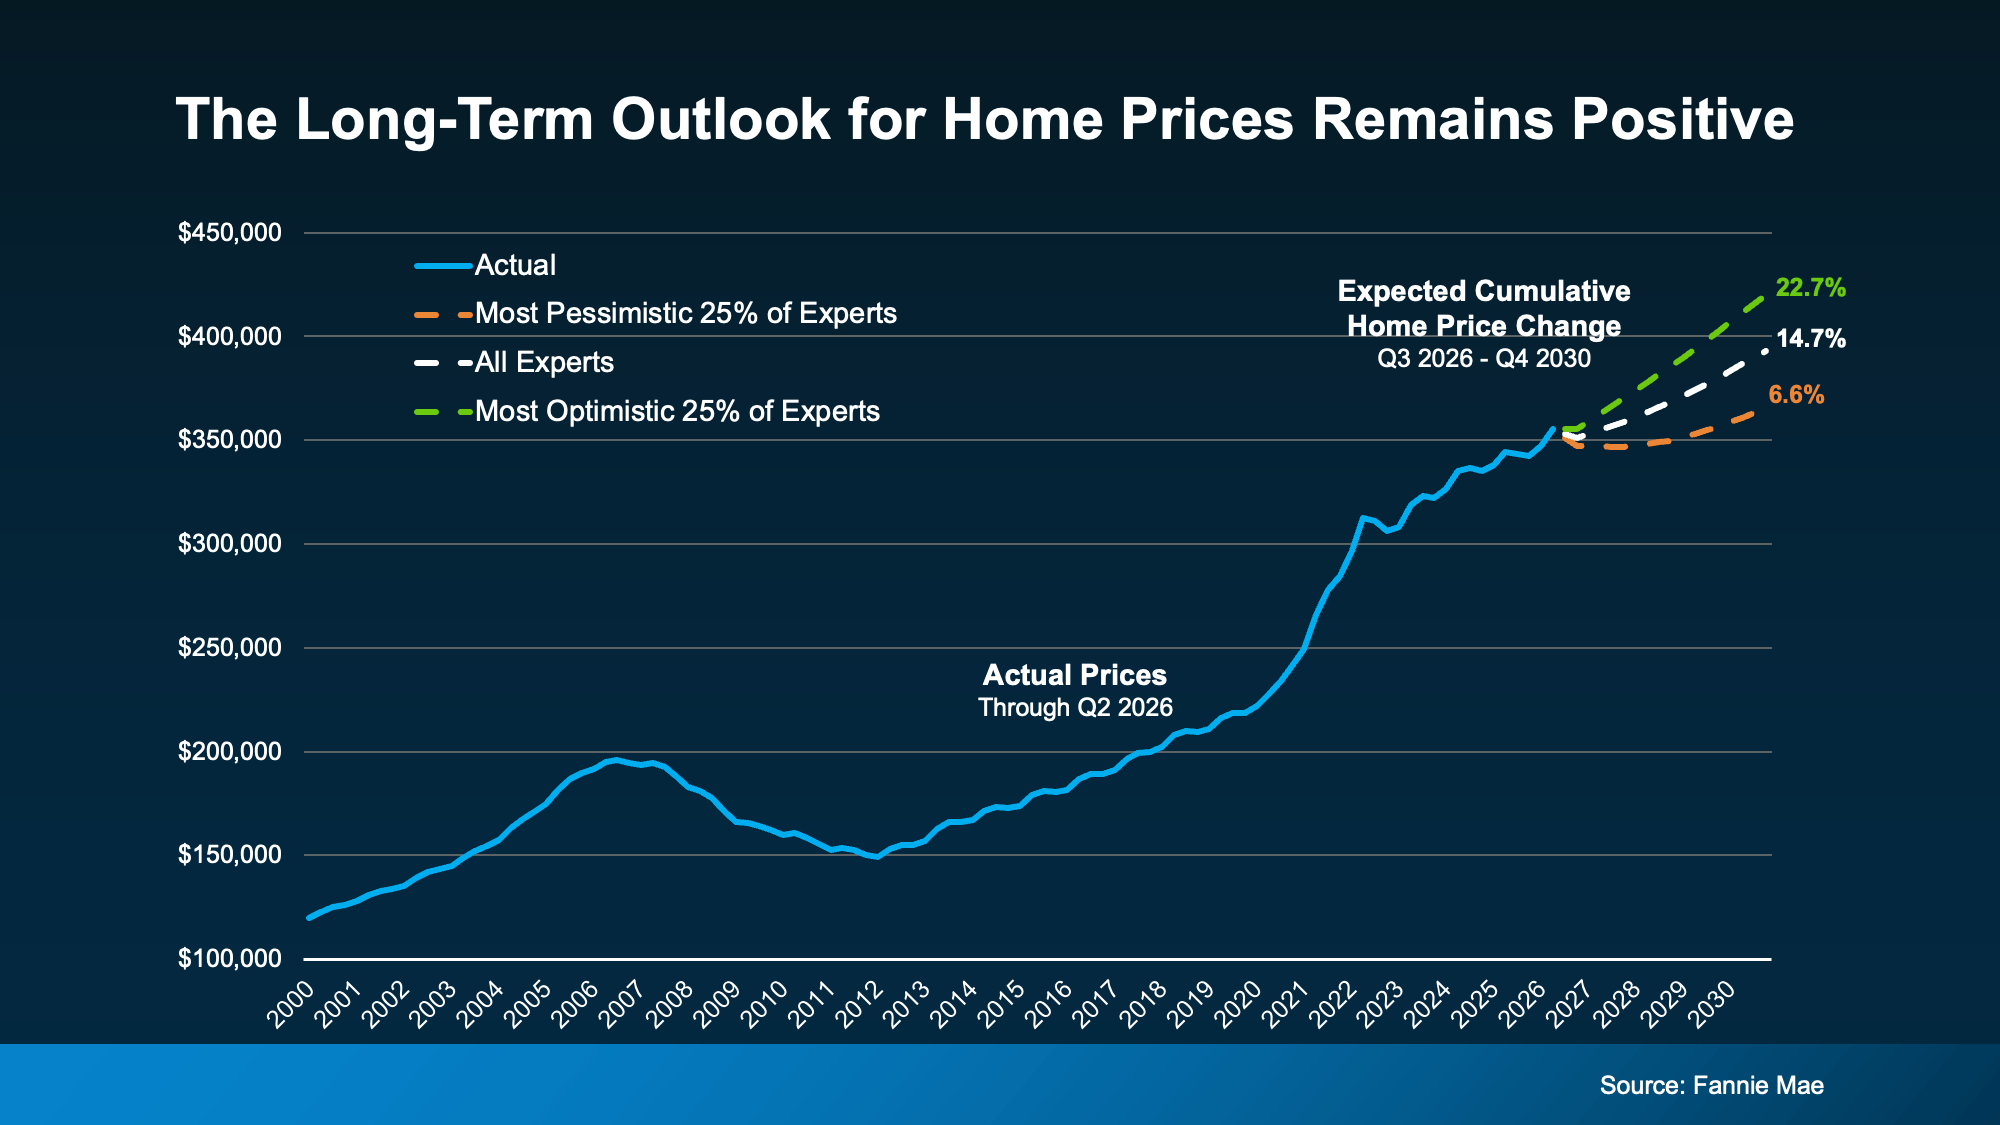
The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):

a graph showing the price of a home

The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.

One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.

How This Quarter Compares to the Past

Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.

A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):

a graph of growth in a graph

Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.

But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.

A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.

A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.

What It Means for Your Next Move

Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.

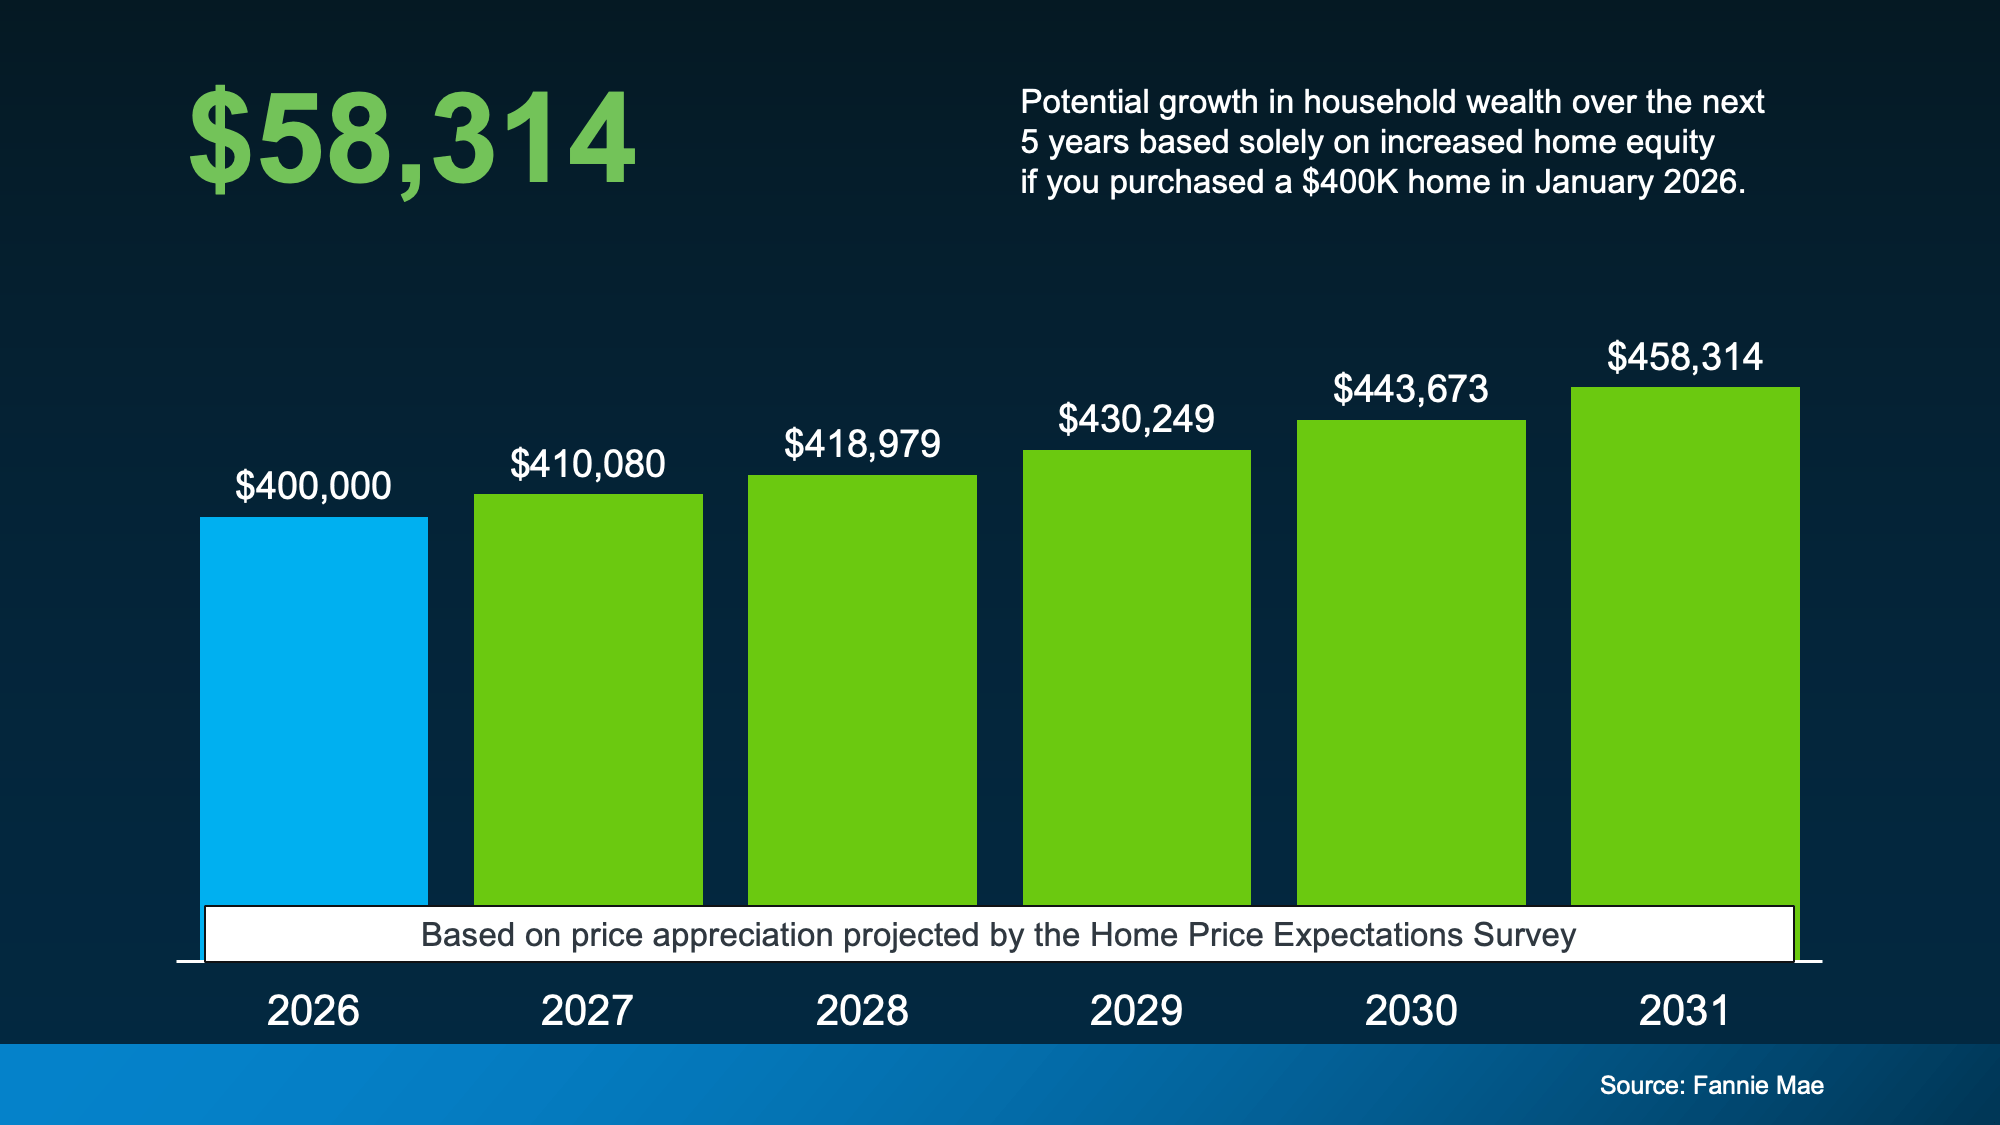
Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):

a graph of growth in a number of green squares

That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.

Bottom Line

Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

One Number Could Change Everything About Your Next Move

One Number Could Change Everything About Your Next Move

One Number Could Change Everything About Your Next Move Simplifying The Market

When’s the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor’s house sold for. What yours is actually worth right now.

For a lot of homeowners, it’s been years. And if you’ve been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.

Your House May Be Worth More Than You Think

Home values have climbed significantly over the past 5-10 years. And even though today’s market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.

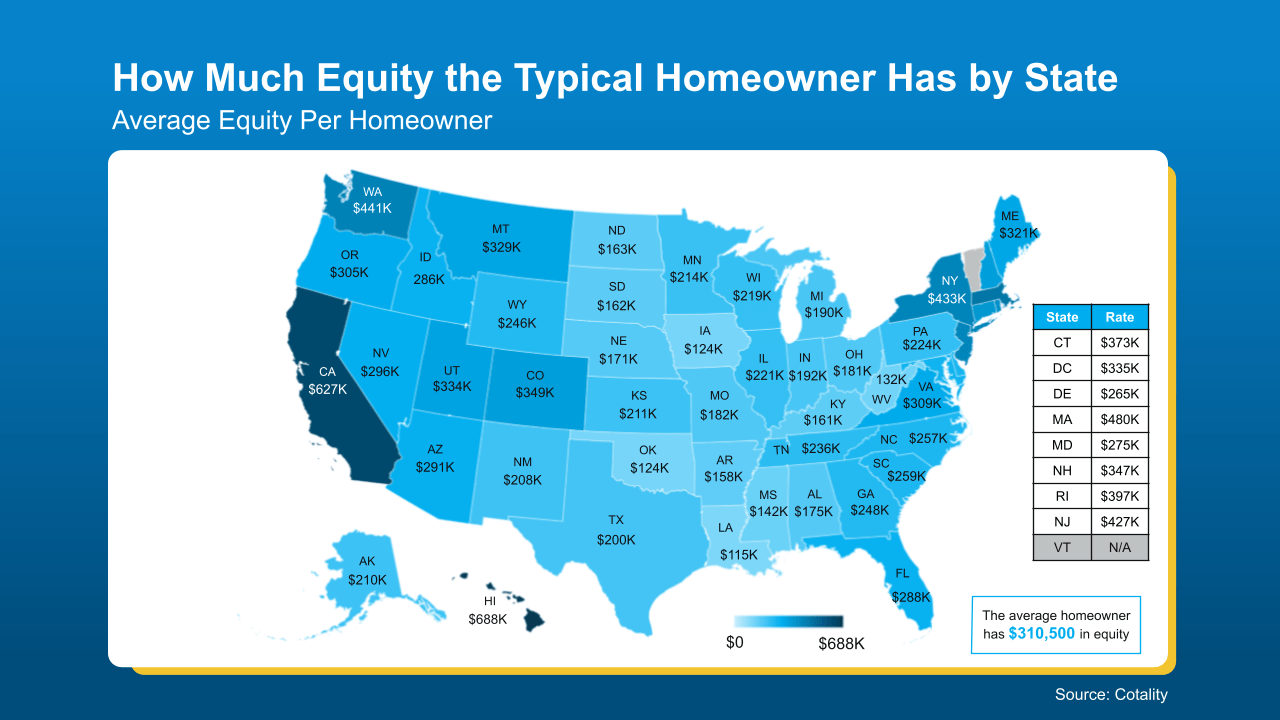
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That’s not a small number. It’s six figures.

And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):

a map of the united statesEven though every local market is different, the question you should be asking right now is the same: How much equity have you built up?
Because if you don’t know that number, you’re missing out.

This Could Be the Missing Piece in Your Move

Most people assume that because prices are higher and rates aren’t at 3% anymore, moving just isn’t realistic right now, especially if they already have an ultra-low rate. And that’s understandable – those are real factors.

But they’re not the only factors.

When you have that much equity in your house, you’re not starting from scratch. You’re not scraping together a down payment or hoping the numbers work. You’re walking into your next move with more of an advantage than you think. And that changes the math. 

What Your Equity Can Do for You

Maybe you’ve outgrown your current house or you’re ready to downsize… The equity you’ve built could help bridge the gap between where you are today and where you want to be next.

Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you’ve built, it could help you:

  • Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today’s rates, borrowing less can make a big difference in what you pay every month. 

  • Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July. 

  • Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.

Your equity doesn’t erase the challenges of the current market. But it does mean you’re walking into your next move with a lot more power and flexibility than you think.

That’s why the value of your home isn’t something you should have to wonder about. 

If you’re even thinking about a move – or if you’re just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.

Because once you see the number, maybe it’s not about whether you can afford to move – it’s about what kind of move makes sense for you.

Bottom Line

If it’s been a while since you’ve gotten a professional look at your home’s value, it’s time to change that. 

Reach out to a local real estate agent for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you’ve likely built, and what that could mean for your next move.

You may have six figures of equity without even realizing it. And that’s enough to change everything about your next move.

The House That Started It All Could Kickstart What’s Next

The House That Started It All Could Kickstart What’s Next

The House That Started It All Could Kickstart What's Next Simplifying The Market

Remember how exciting it was to buy your first place? It felt like crossing a long-awaited finish line. It gave you a place to build your life. Maybe it’s where you lived when you got married. Or where you welcomed a child or a pet into the family.

But that was just the beginning.

For most people, your first house was never meant to be your forever home. It’s a stepping stone for what comes next.

And if your life looks different today than it did when you got the keys, you’re not stuck. Moving may be more realistic than you think.

Starter Home Inventory Is Still Relatively Low

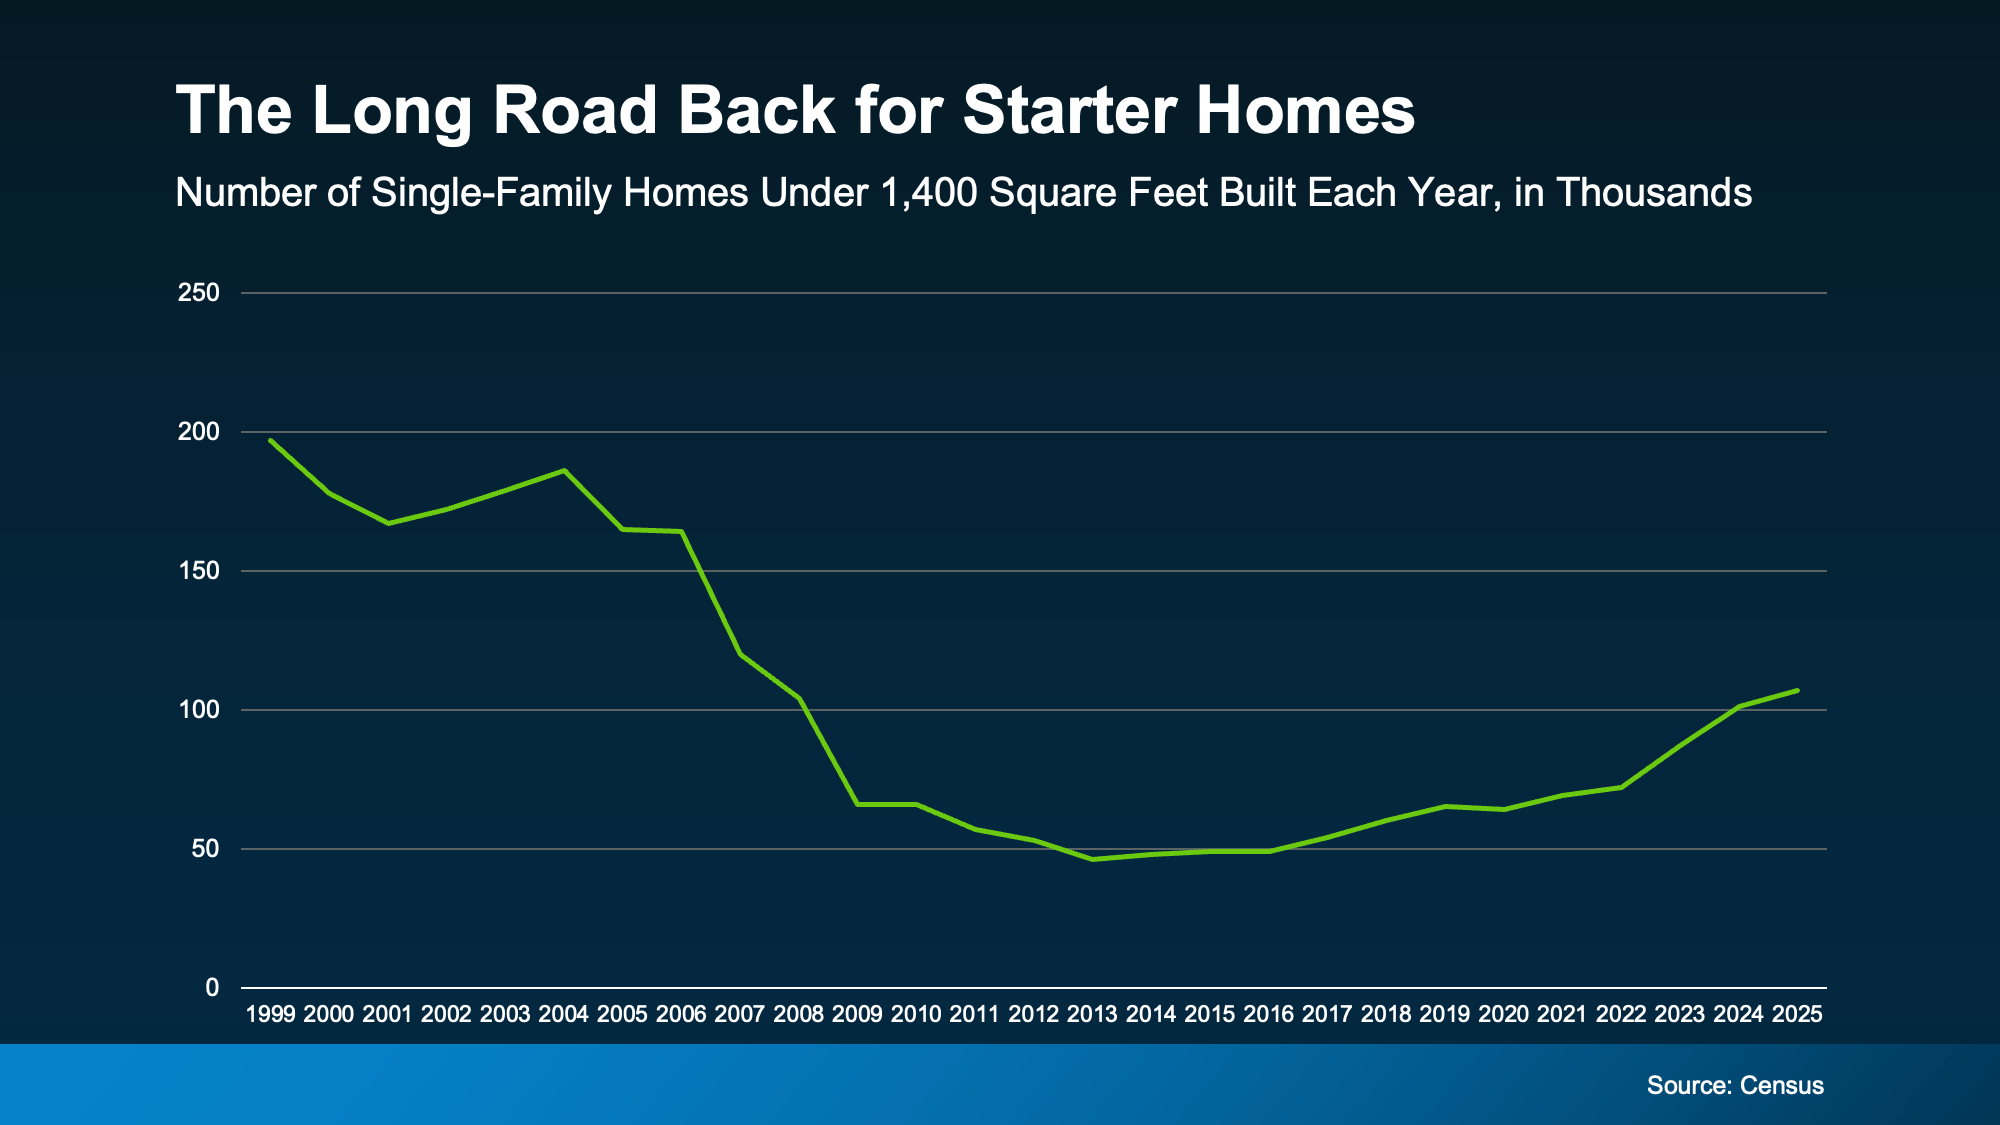
If you’ve been wondering whether now is the right time to move up, here’s something worth knowing. Starter homes remain one of the hardest types of homes to find. And that’s good news if you’re thinking about selling your first place.

Historically, we haven’t been building enough homes for first-time buyers. And even though homebuilders have shifted more attention toward smaller, entry-level homes lately, the Census shows there’s a long way to go to re-build supply (see graph below):

a graph showing a growing trend

That means your current house is in demand – and that’s a dream scenario for sellers. But that’s only half the story. You also need somewhere to go.

There Are More Move-Up Homes on the Market

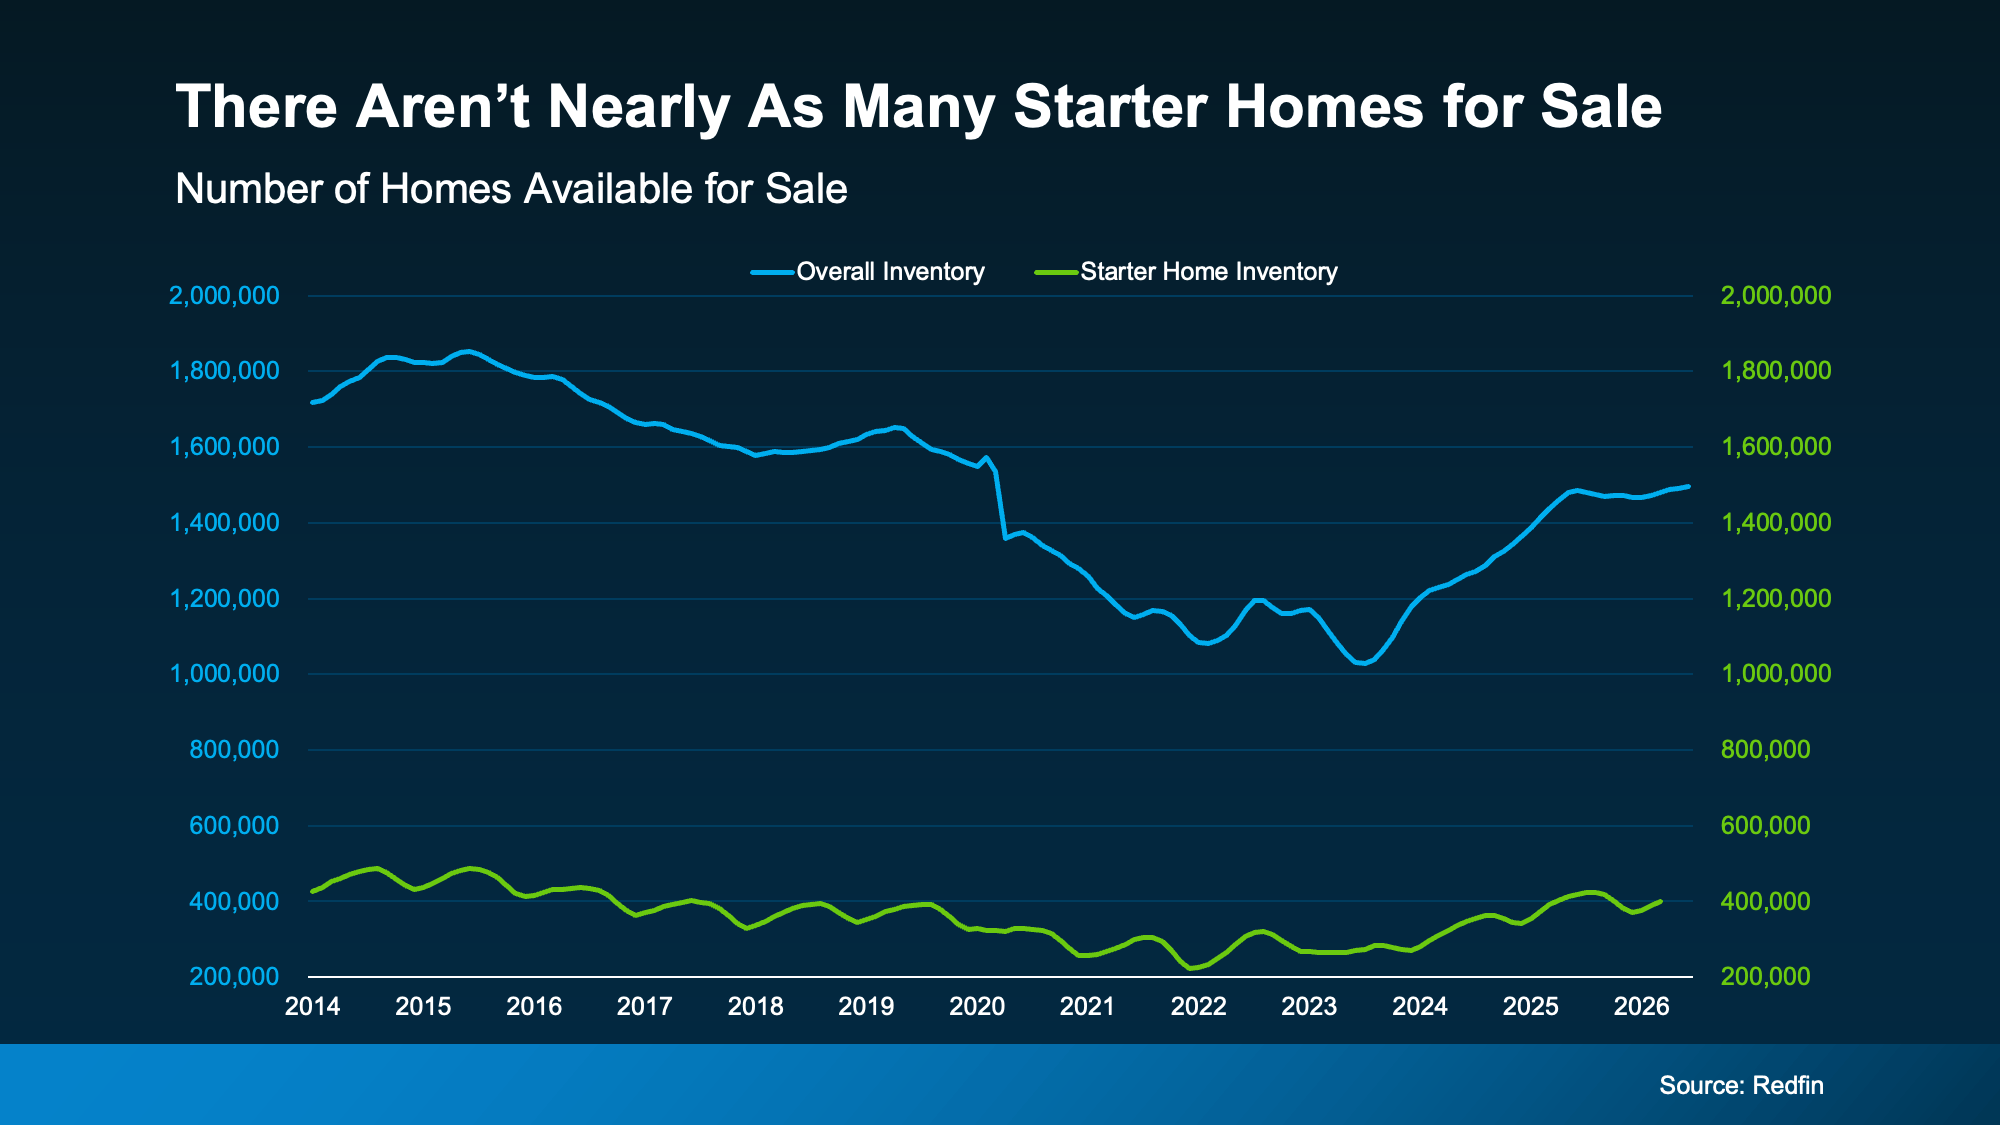
Here’s where this gets interesting. While the supply of starter homes remains tight (the green line), data from Redfin shows that the number of homes for sale has been climbing overall (the blue line):

a graph of sales and prices

As Nadia Evangelou, Principal Economist and Director of Real Estate Research at the National Association of Realtors (NAR), explains:

“Too much of the inventory available today remains concentrated at higher price points, leaving a shortage of options for entry-level and middle-income buyers.”

That means you may have more choices for your move up than you’d expect. Whether you’re hoping for another bedroom, a home office, a bigger backyard, or simply more room for this next stage of life, today’s market may finally be giving you the chance to find it.

At the same time, your current house may be exactly what someone else has been looking for because homes like yours are still in short supply. That’s a unique advantage for move-up buyers. And it could help you sell for a stronger price. As Zillow says:

“Starter home value appreciation has outpaced other types of homes nationally, mostly because they’re so in demand.”

Your Biggest Advantage May Be Your Equity

Here’s the cherry on top. There’s one more thing your first home has been doing behind the scenes, and that’s building equity. Every mortgage payment you’ve made and every year your home’s value has grown has quietly increased your ownership stake in your house.

According to Cotality, the average homeowner with a mortgage has $295k in equity built up. While your number may be different, once you sell, it could become the down payment on your next home or help reduce the amount you need to borrow at today’s rates.

Put it all together and your move up becomes a lot more realistic than you think:

  • The house you’re selling is in demand.

  • The house you’re buying may be easier to find.

  • And the equity you’ve built can help bridge the gap between the two.

Your first home did exactly what it was supposed to do. It gave you a place to start.

Now, it may be the thing that helps you take the next step.

Bottom Line

Your first home was never meant to be your forever home. It was meant to help you build a life and build the financial foundation for whatever came next.

If your current home no longer fits the life you’re living today, connect with an agent. You may be closer to your next chapter than you realize.

The Housing Market Is Stronger Than You Think

The Housing Market Is Stronger Than You Think

The Housing Market Is Stronger Than You Think Simplifying The Market

You’ve probably heard plenty of doom and gloom about the housing market lately. High rates. Stretched budgets. Headlines that make buying or selling sound like a terrible idea. But the data tells a very different story. 

This isn’t 2020 or 2021. It was never going to be. Those were the “unicorn years” – historic low mortgage rates, bidding wars on everything, homes flying off the market in days. That kind of market was a once-in-a-generation anomaly, not a baseline. So, when people compare today to that, of course it looks rough.

But compared to almost any other housing market in modern history? This one is holding up remarkably well.

Homeowners Are Sitting on a Mountain of Equity

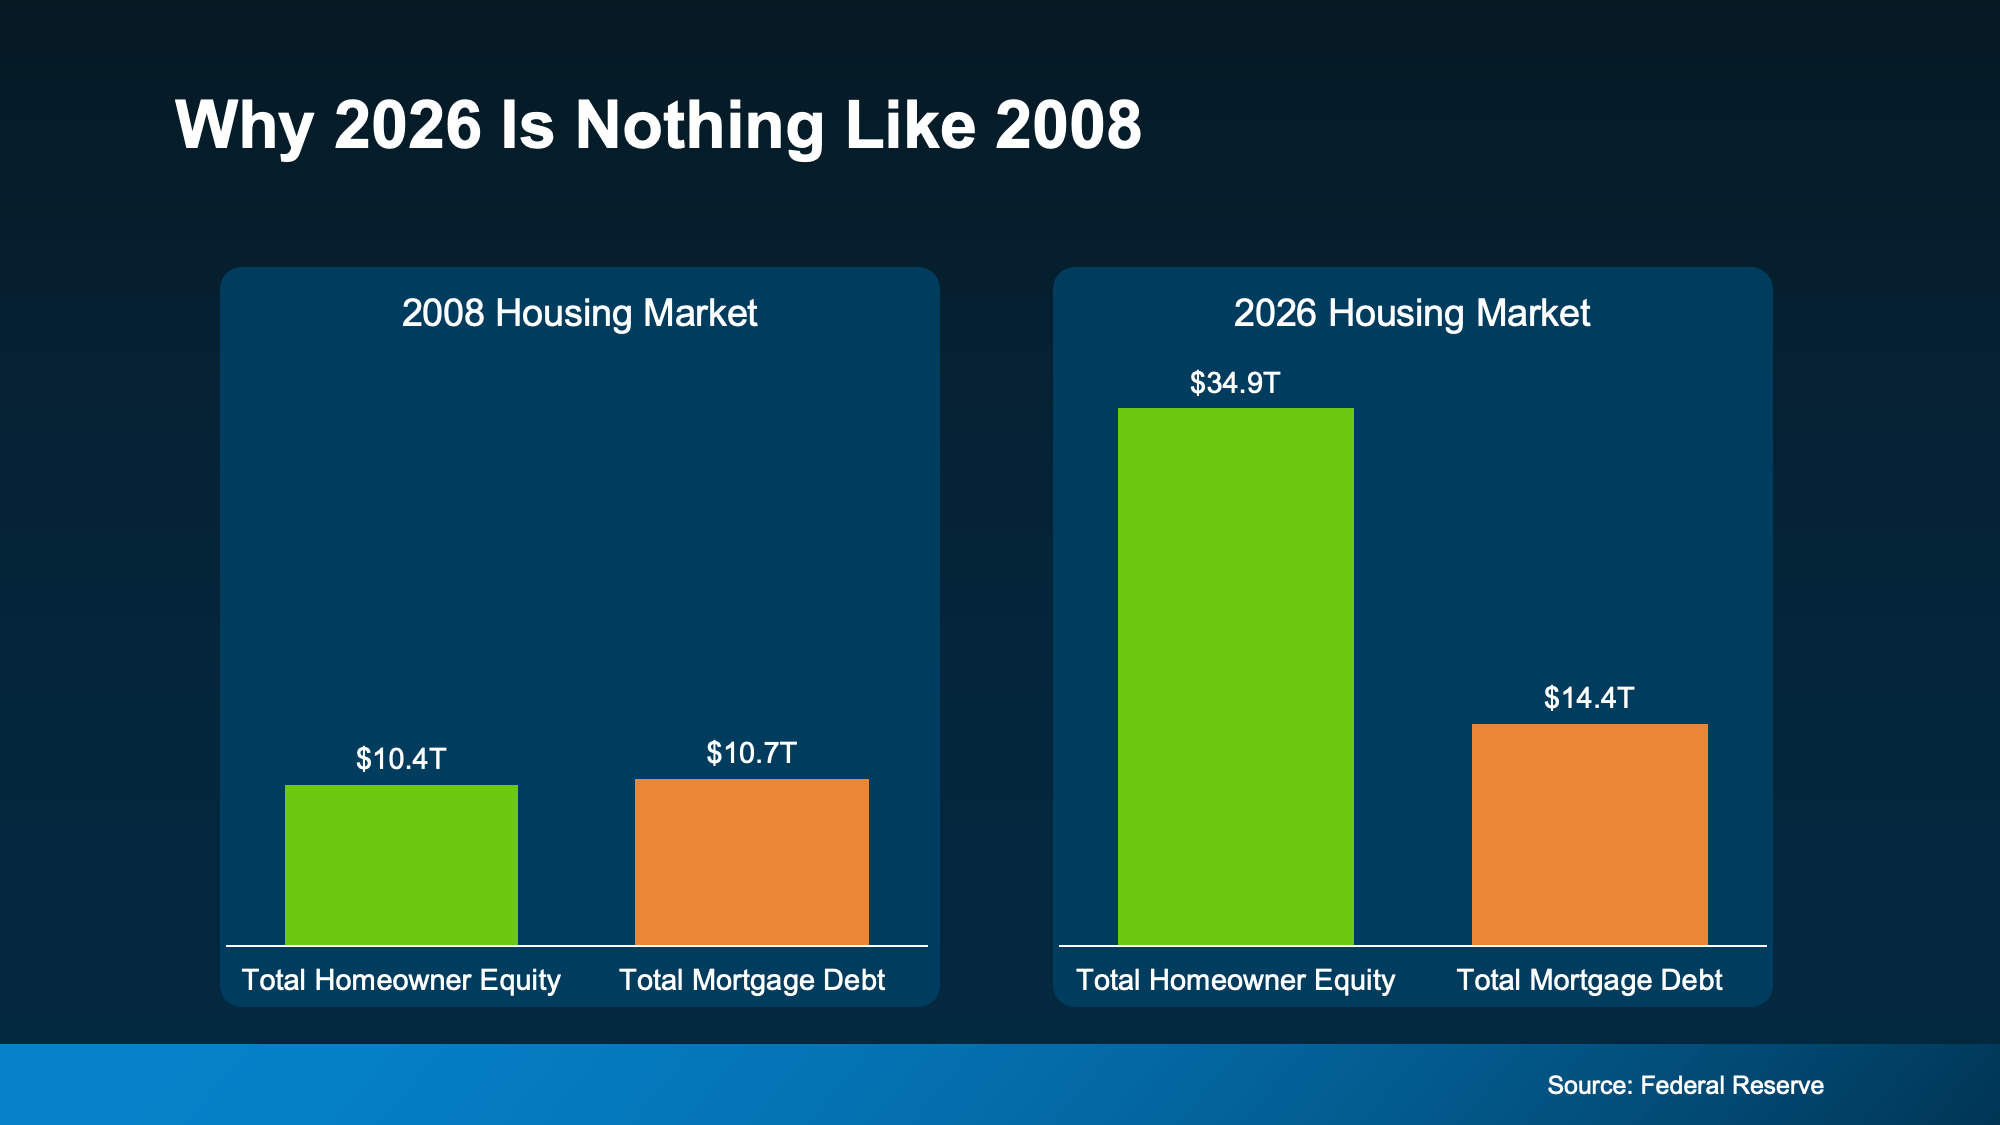
One of the biggest reasons this market hasn’t cracked is the financial strength of the American homeowner. According to Federal Reserve data, homeowner equity and mortgage debt were nearly identical in 2008. That means, if someone hit a rough patch, they had almost nothing to fall back on. That’s what made that crash so bad.

Today? Total homeowner equity across the country sits at $35 trillion – dwarfing total mortgage debt (see graph below):

a graph of a marketThat gap means most homeowners aren’t stretched thin or one bad month away from trouble. They own a meaningful chunk of their home and that gives them options. If they needed to sell, many could because they have a cushion. And that cushion grows over time.
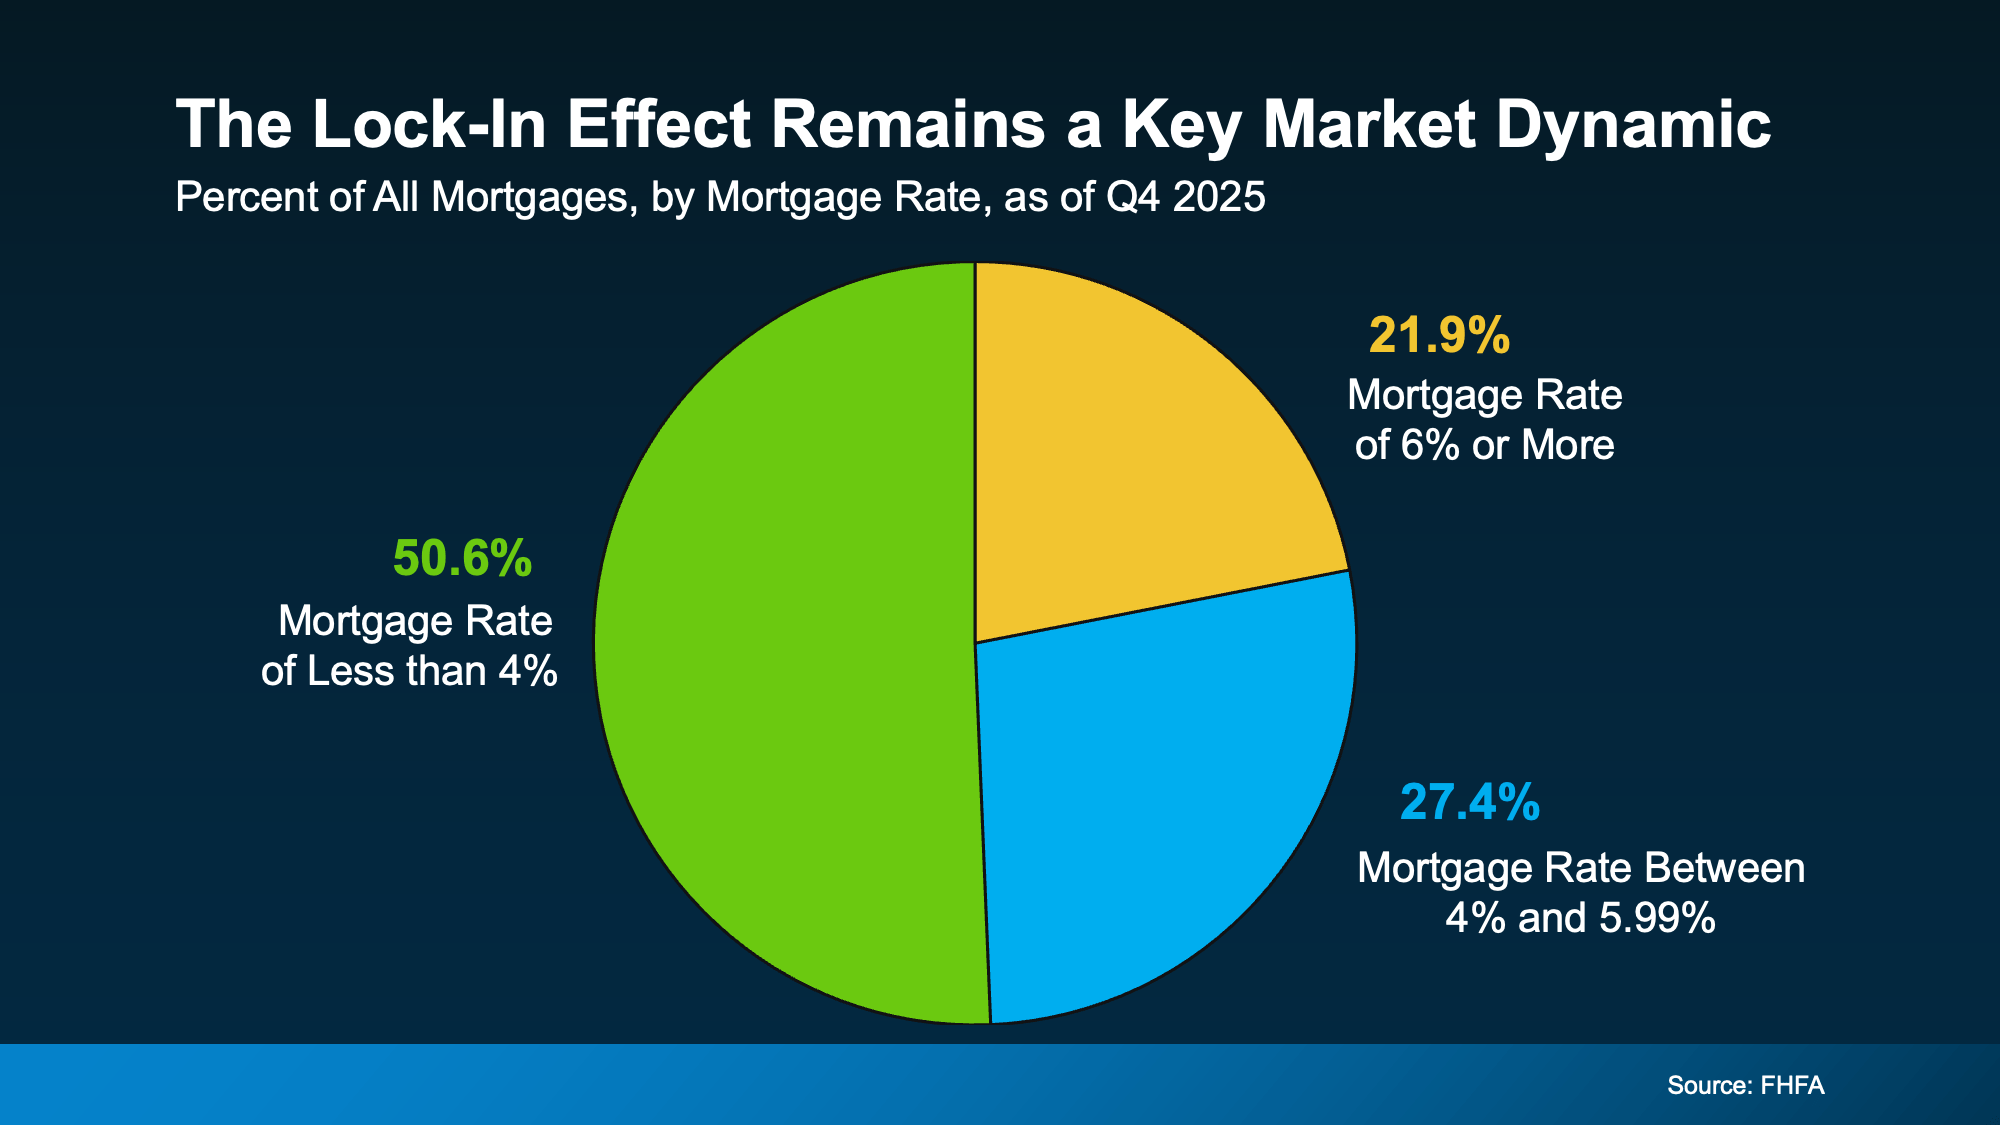
  • Realtor.com found that homeowners who’ve been in their home just 5 years have built up around $180,000 in equity on average. Stick around 6-10 years, and that jumps to over $340,000.

  • Data from ATTOM and the Census shows two-thirds of homeowners either own their home outright or have more than 50% equity.

That’s not a fragile market. That’s a population of homeowners who are financially positioned to sell, to stay, or to make their next move from a place of strength rather than pressure.

Low Rates and Low Foreclosures

At the same time, Federal Housing Finance Agency (FHFA) data shows more than half of all active mortgages still carry a rate below 4% (see graph below): 

a chart with text on itThat’s a big reason inventory stays tight. Those homeowners aren’t in a rush to trade their rate for a higher one. They’re sitting comfortably in a strong financial position, not scrambling.
That comfort shows up in the foreclosure numbers, too. Despite a slight recent uptick, foreclosure volumes remain dramatically below historical norms, according to ATTOM. Homeowners aren’t losing their homes in droves. They have equity, they have breathing room, and most have options that keep them out of financial distress.

Prices Are Stabilizing, Not Crashing

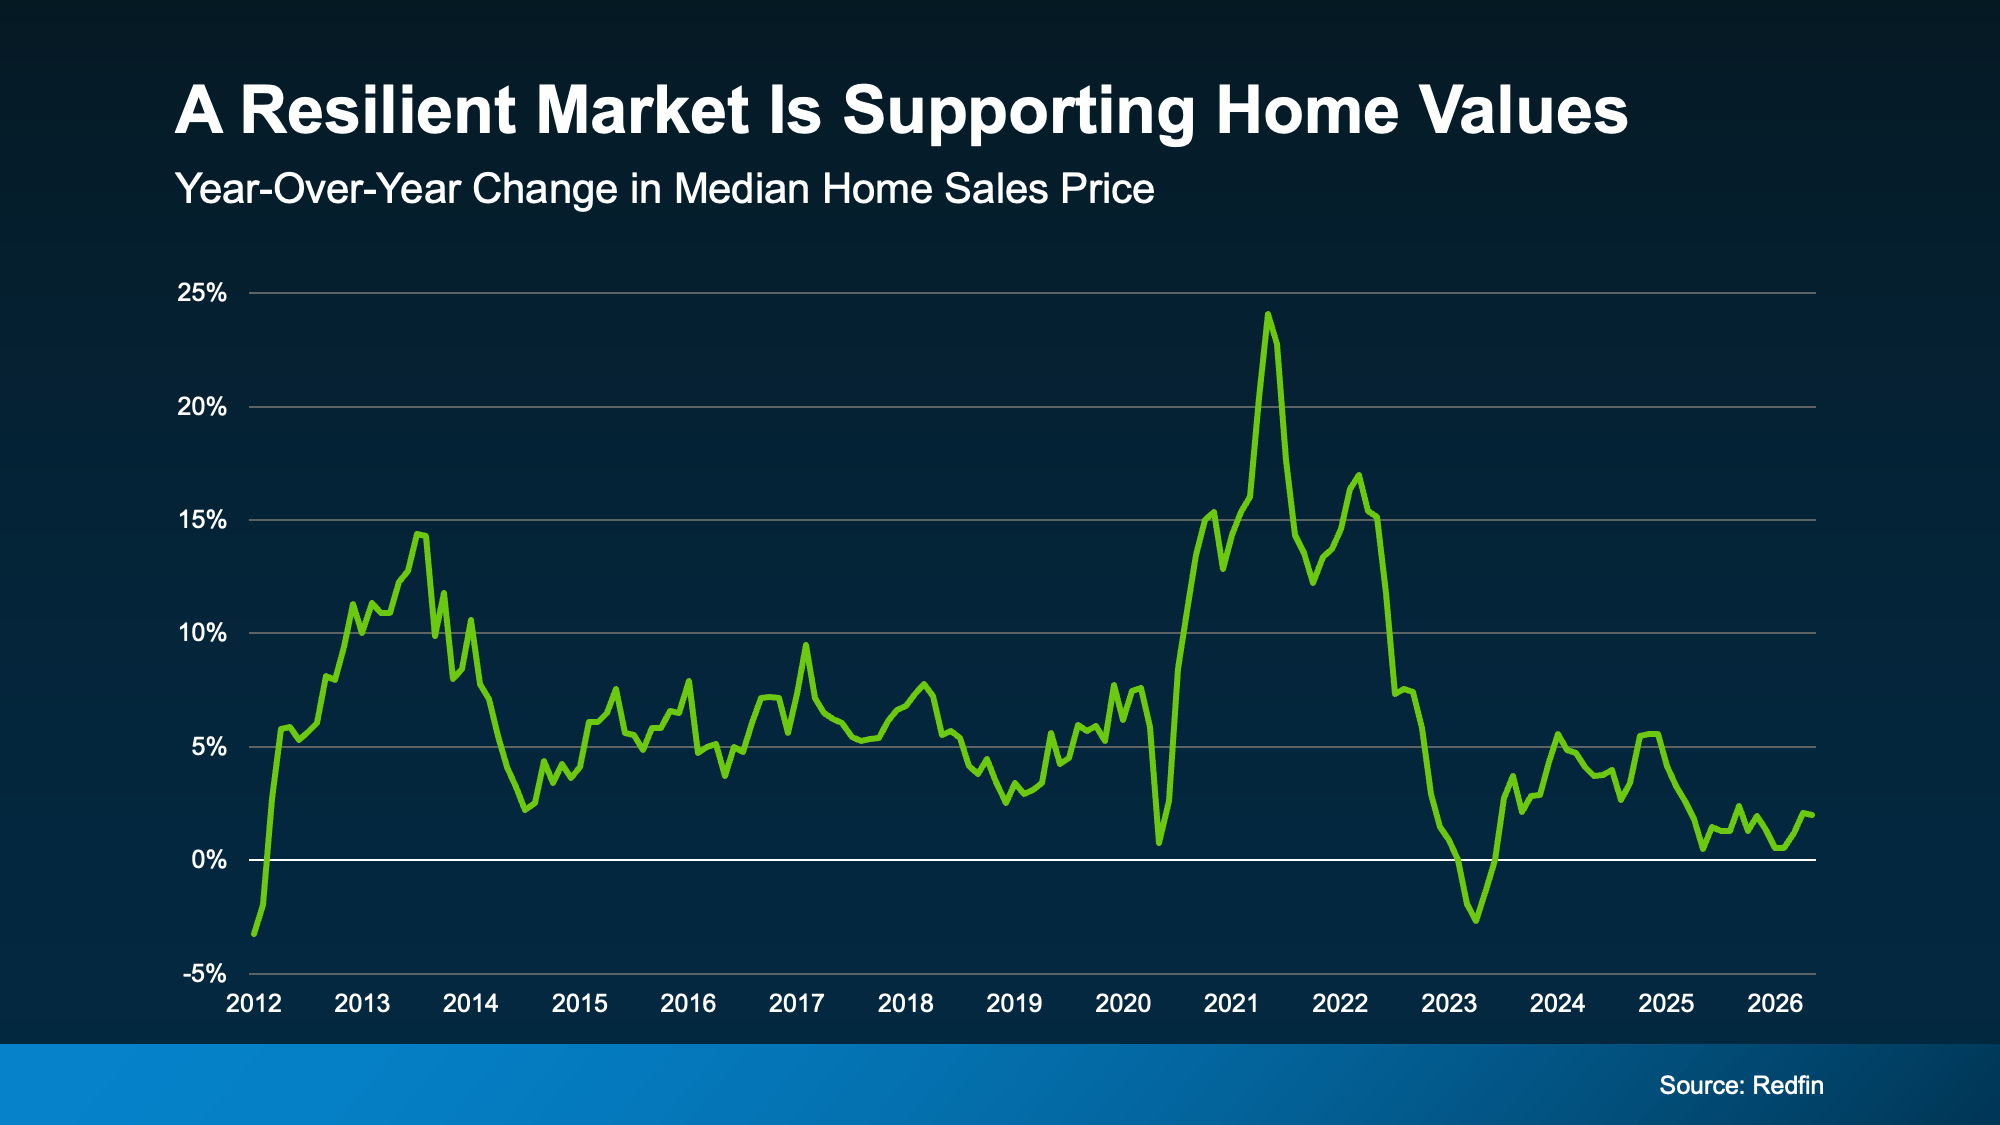
Here’s another point on the resilience of the market. Redfin research shows home prices are still rising, but the pace has slowed, now closer to 2% year-over-year nationally (see graph below):

a graph of a line graphThat slowdown is good news, as Daryl Fairweather, Chief Economist at Redfin, explains:
“We’re in the middle of a long-term housing market correction, not a housing market crash. After the pandemic-era frenzy sent prices soaring and inventory to historic lows, the market needed a reset.”

Bottom Line

This market isn’t broken, and waiting for a crash that isn’t coming has a cost. Every month spent on the sidelines is a month someone else is building equity, locking in a price, or getting ahead of what most experts expect to be a housing surge once broader economic conditions settle.

Whether you’re thinking about buying or selling, a local real estate agent can help you figure out what this market means for your specific situation and what your next move could look like.

Pin It on Pinterest