The Housing Market Is Stronger Than You Think

The Housing Market Is Stronger Than You Think
The Housing Market Is Stronger Than You Think Simplifying The Market

You’ve probably heard plenty of doom and gloom about the housing market lately. High rates. Stretched budgets. Headlines that make buying or selling sound like a terrible idea. But the data tells a very different story. 

This isn’t 2020 or 2021. It was never going to be. Those were the “unicorn years” – historic low mortgage rates, bidding wars on everything, homes flying off the market in days. That kind of market was a once-in-a-generation anomaly, not a baseline. So, when people compare today to that, of course it looks rough.

But compared to almost any other housing market in modern history? This one is holding up remarkably well.

Homeowners Are Sitting on a Mountain of Equity

One of the biggest reasons this market hasn’t cracked is the financial strength of the American homeowner. According to Federal Reserve data, homeowner equity and mortgage debt were nearly identical in 2008. That means, if someone hit a rough patch, they had almost nothing to fall back on. That’s what made that crash so bad.

Today? Total homeowner equity across the country sits at $35 trillion – dwarfing total mortgage debt (see graph below):
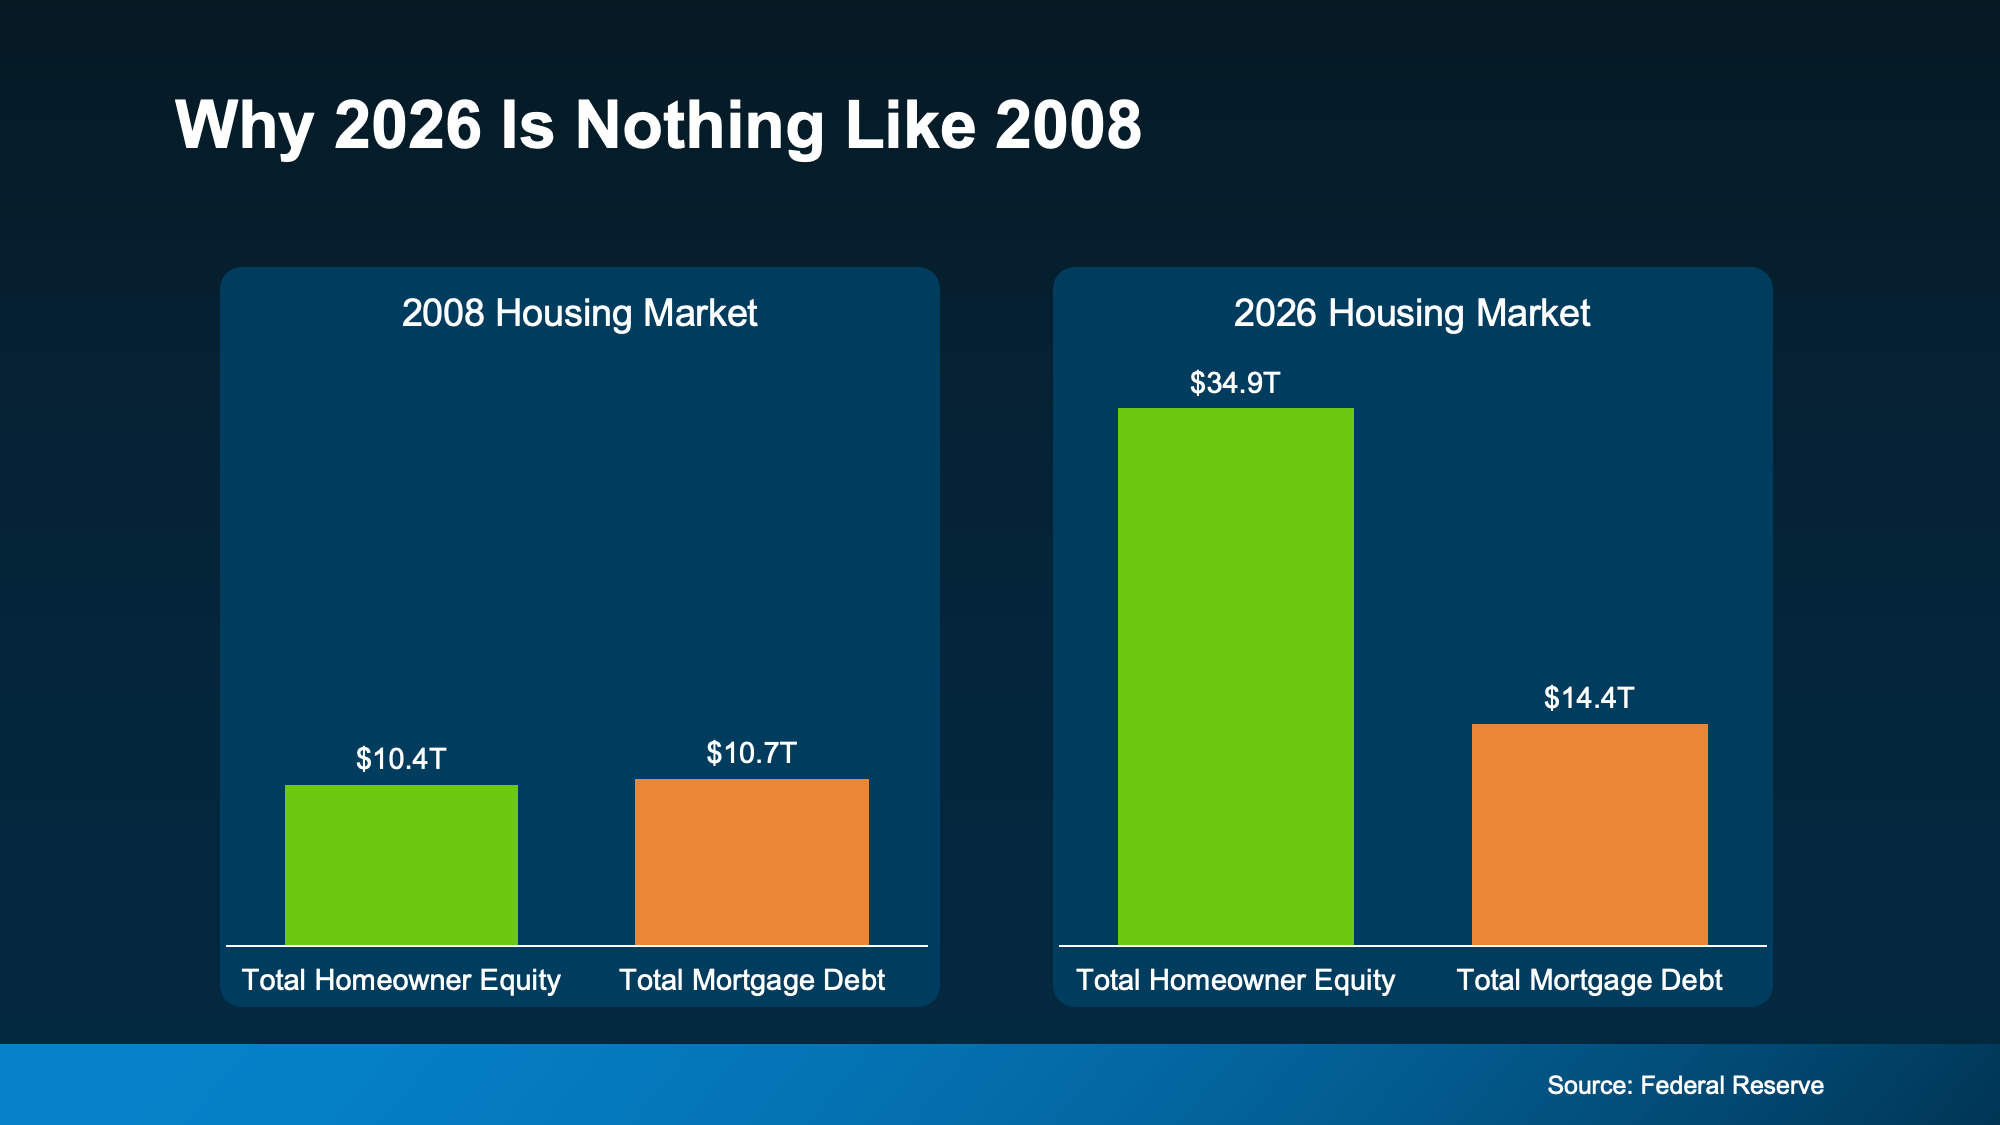
a graph of a marketThat gap means most homeowners aren’t stretched thin or one bad month away from trouble. They own a meaningful chunk of their home and that gives them options. If they needed to sell, many could because they have a cushion. And that cushion grows over time.

  • Realtor.com found that homeowners who’ve been in their home just 5 years have built up around $180,000 in equity on average. Stick around 6-10 years, and that jumps to over $340,000.

  • Data from ATTOM and the Census shows two-thirds of homeowners either own their home outright or have more than 50% equity.

That’s not a fragile market. That’s a population of homeowners who are financially positioned to sell, to stay, or to make their next move from a place of strength rather than pressure.

Low Rates and Low Foreclosures

At the same time, Federal Housing Finance Agency (FHFA) data shows more than half of all active mortgages still carry a rate below 4% (see graph below): 
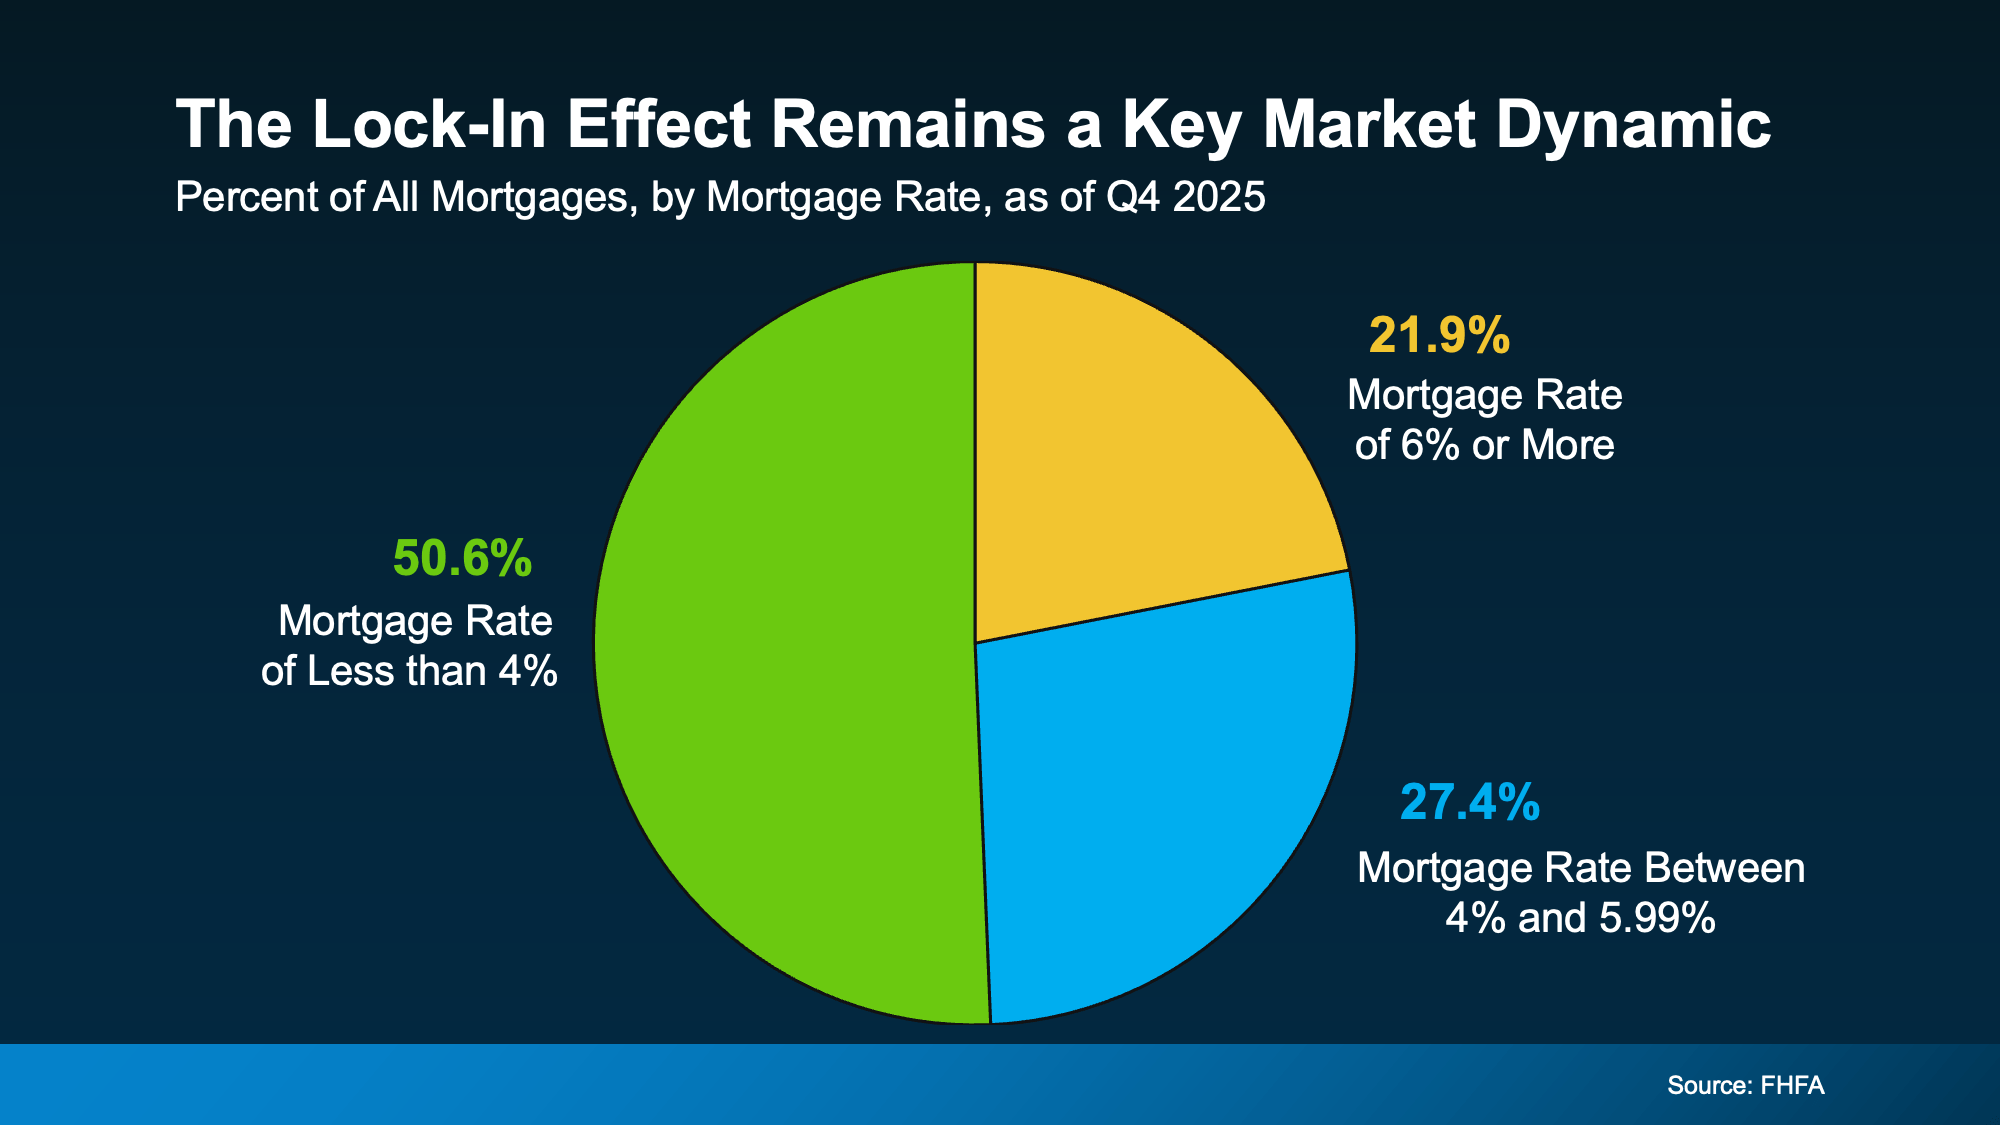
a chart with text on itThat’s a big reason inventory stays tight. Those homeowners aren’t in a rush to trade their rate for a higher one. They’re sitting comfortably in a strong financial position, not scrambling.

That comfort shows up in the foreclosure numbers, too. Despite a slight recent uptick, foreclosure volumes remain dramatically below historical norms, according to ATTOM. Homeowners aren’t losing their homes in droves. They have equity, they have breathing room, and most have options that keep them out of financial distress.

Prices Are Stabilizing, Not Crashing

Here’s another point on the resilience of the market. Redfin research shows home prices are still rising, but the pace has slowed, now closer to 2% year-over-year nationally (see graph below):
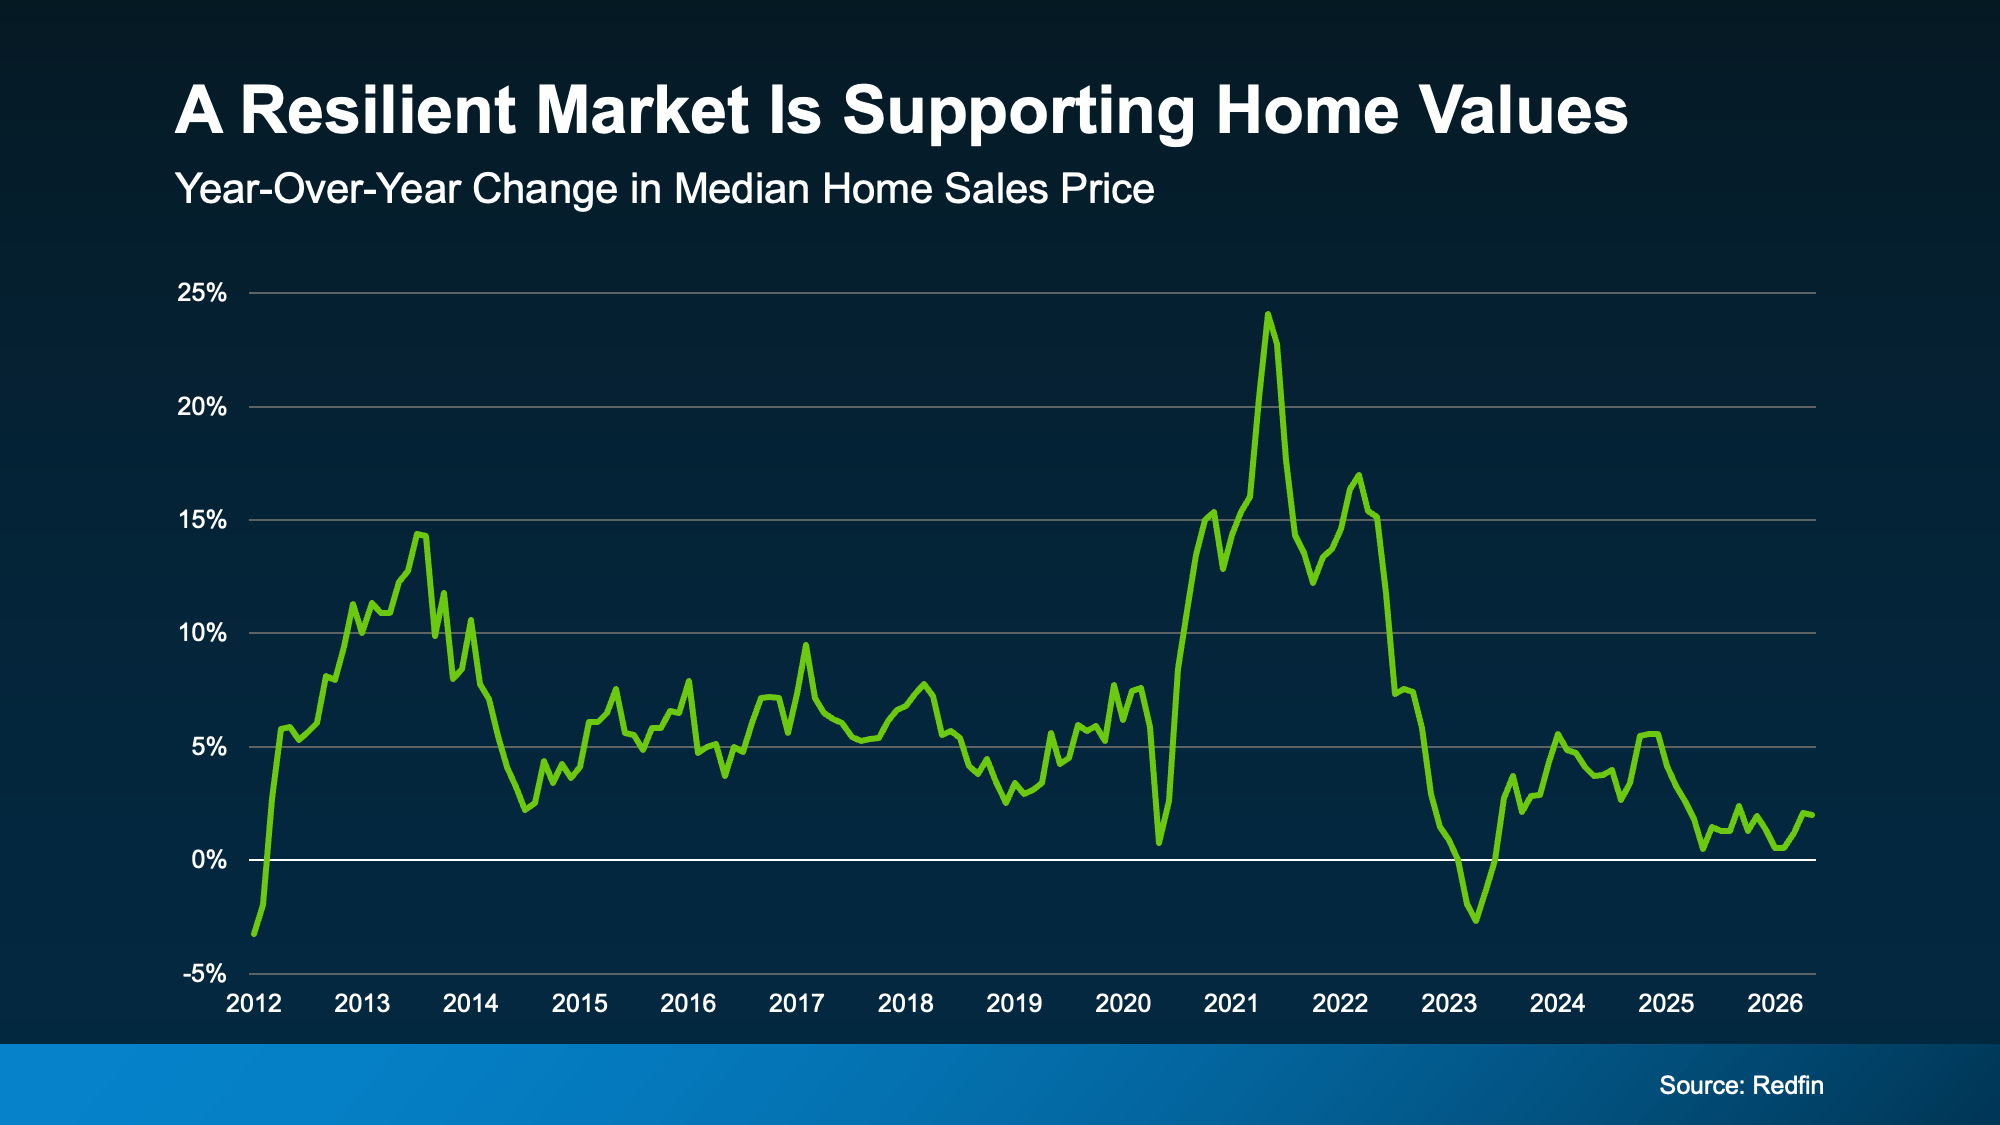
a graph of a line graphThat slowdown is good news, as Daryl Fairweather, Chief Economist at Redfin, explains:

“We’re in the middle of a long-term housing market correction, not a housing market crash. After the pandemic-era frenzy sent prices soaring and inventory to historic lows, the market needed a reset.

Bottom Line

This market isn’t broken, and waiting for a crash that isn’t coming has a cost. Every month spent on the sidelines is a month someone else is building equity, locking in a price, or getting ahead of what most experts expect to be a housing surge once broader economic conditions settle.

Whether you’re thinking about buying or selling, a local real estate agent can help you figure out what this market means for your specific situation and what your next move could look like.
The 1 Factor That Explains Everything Happening with Home Prices Right Now

The 1 Factor That Explains Everything Happening with Home Prices Right Now

The 1 Factor That Explains Everything Happening with Home Prices Right Now Simplifying The Market

You’ve probably heard that home prices are cooling off. And that’s true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.

Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what’s causing all of that variation? 

It All Comes Down to Inventory

Here’s the simple version:

  1. When there are more homes for sale, buyers have options.

  2. More options, means less competition.

  3. Less competition means sellers can’t push prices as high.

On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.

That dynamic is playing out right now in a really visible way across the country. 

Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:

“Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.

In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing.”

The Maps Say It All 

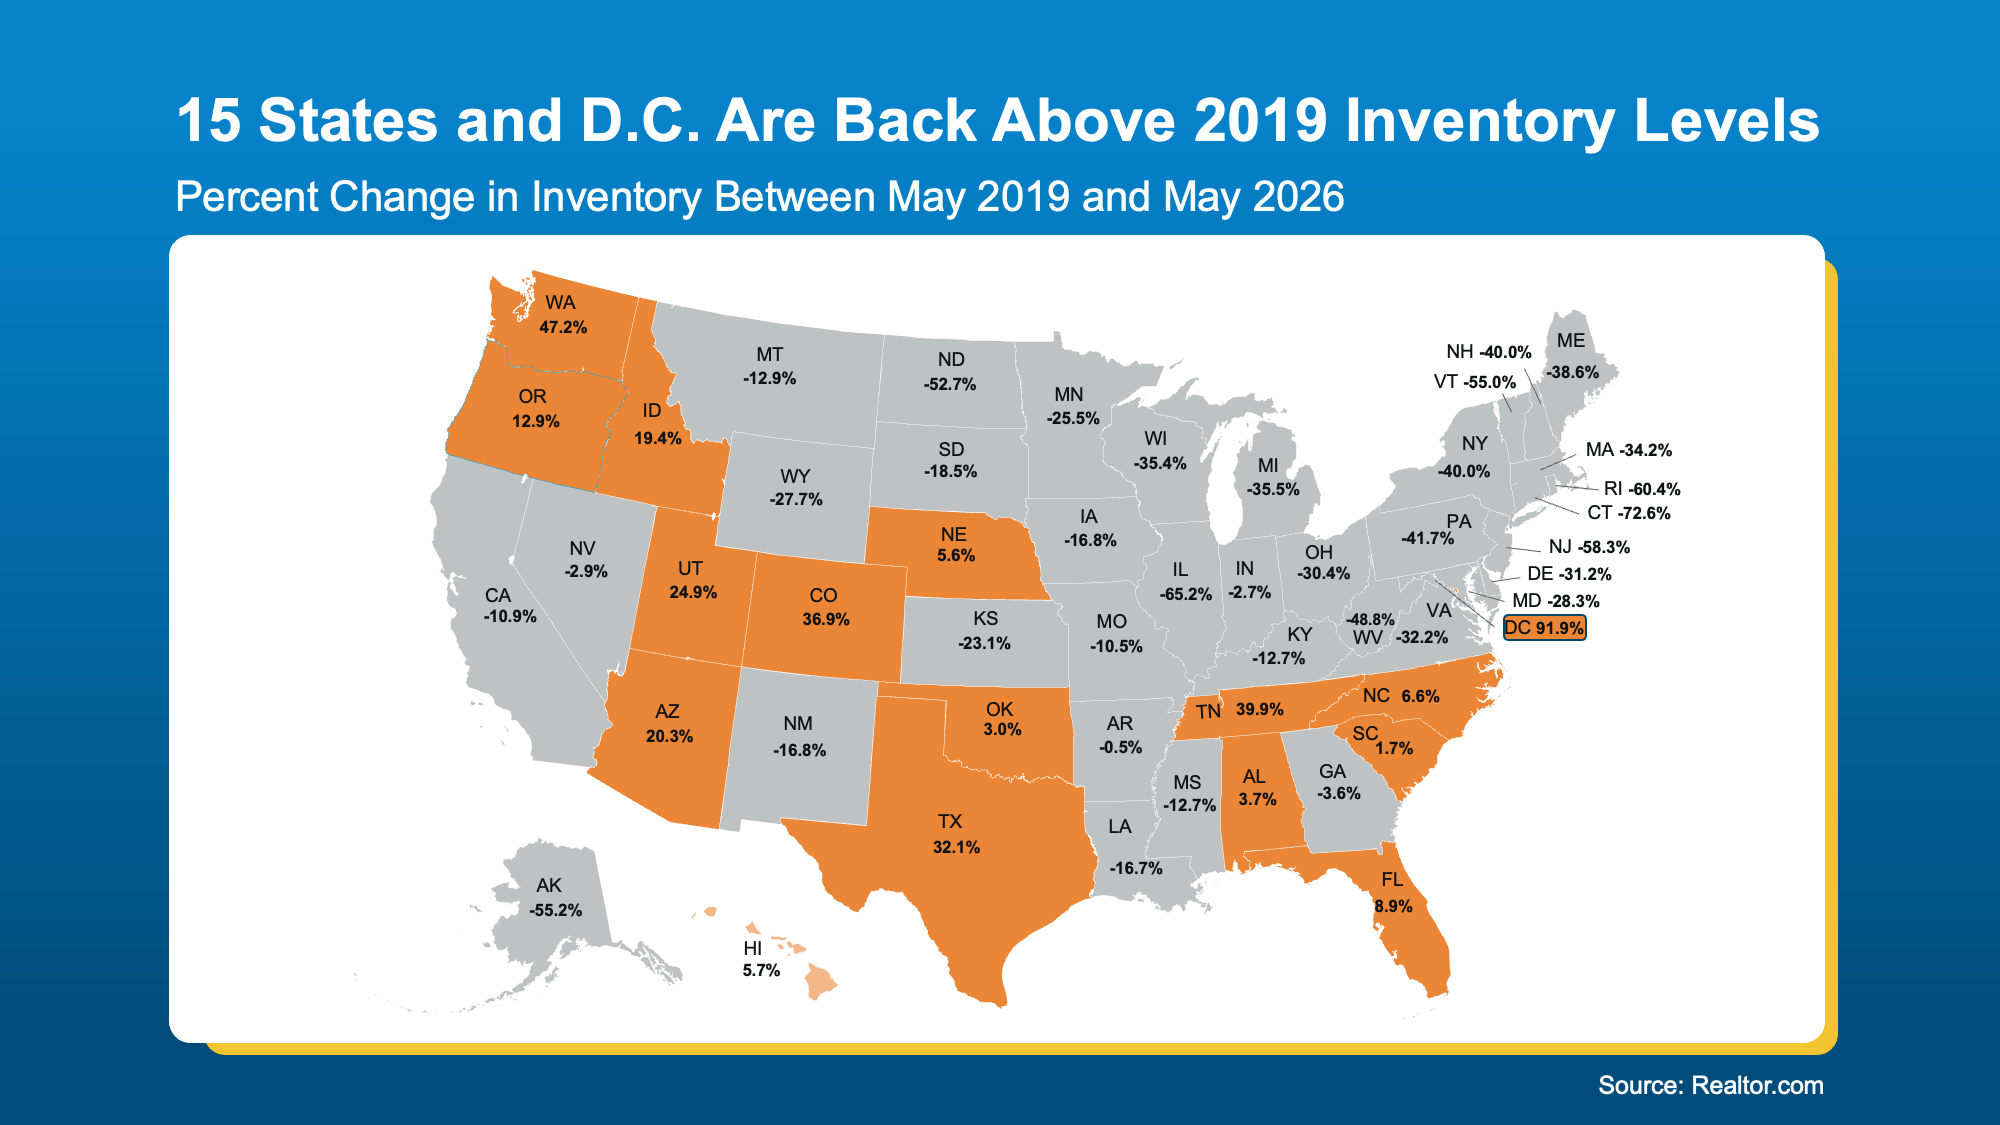
Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.

But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.

According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):

a map of the united statesNow, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what’s happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map). 
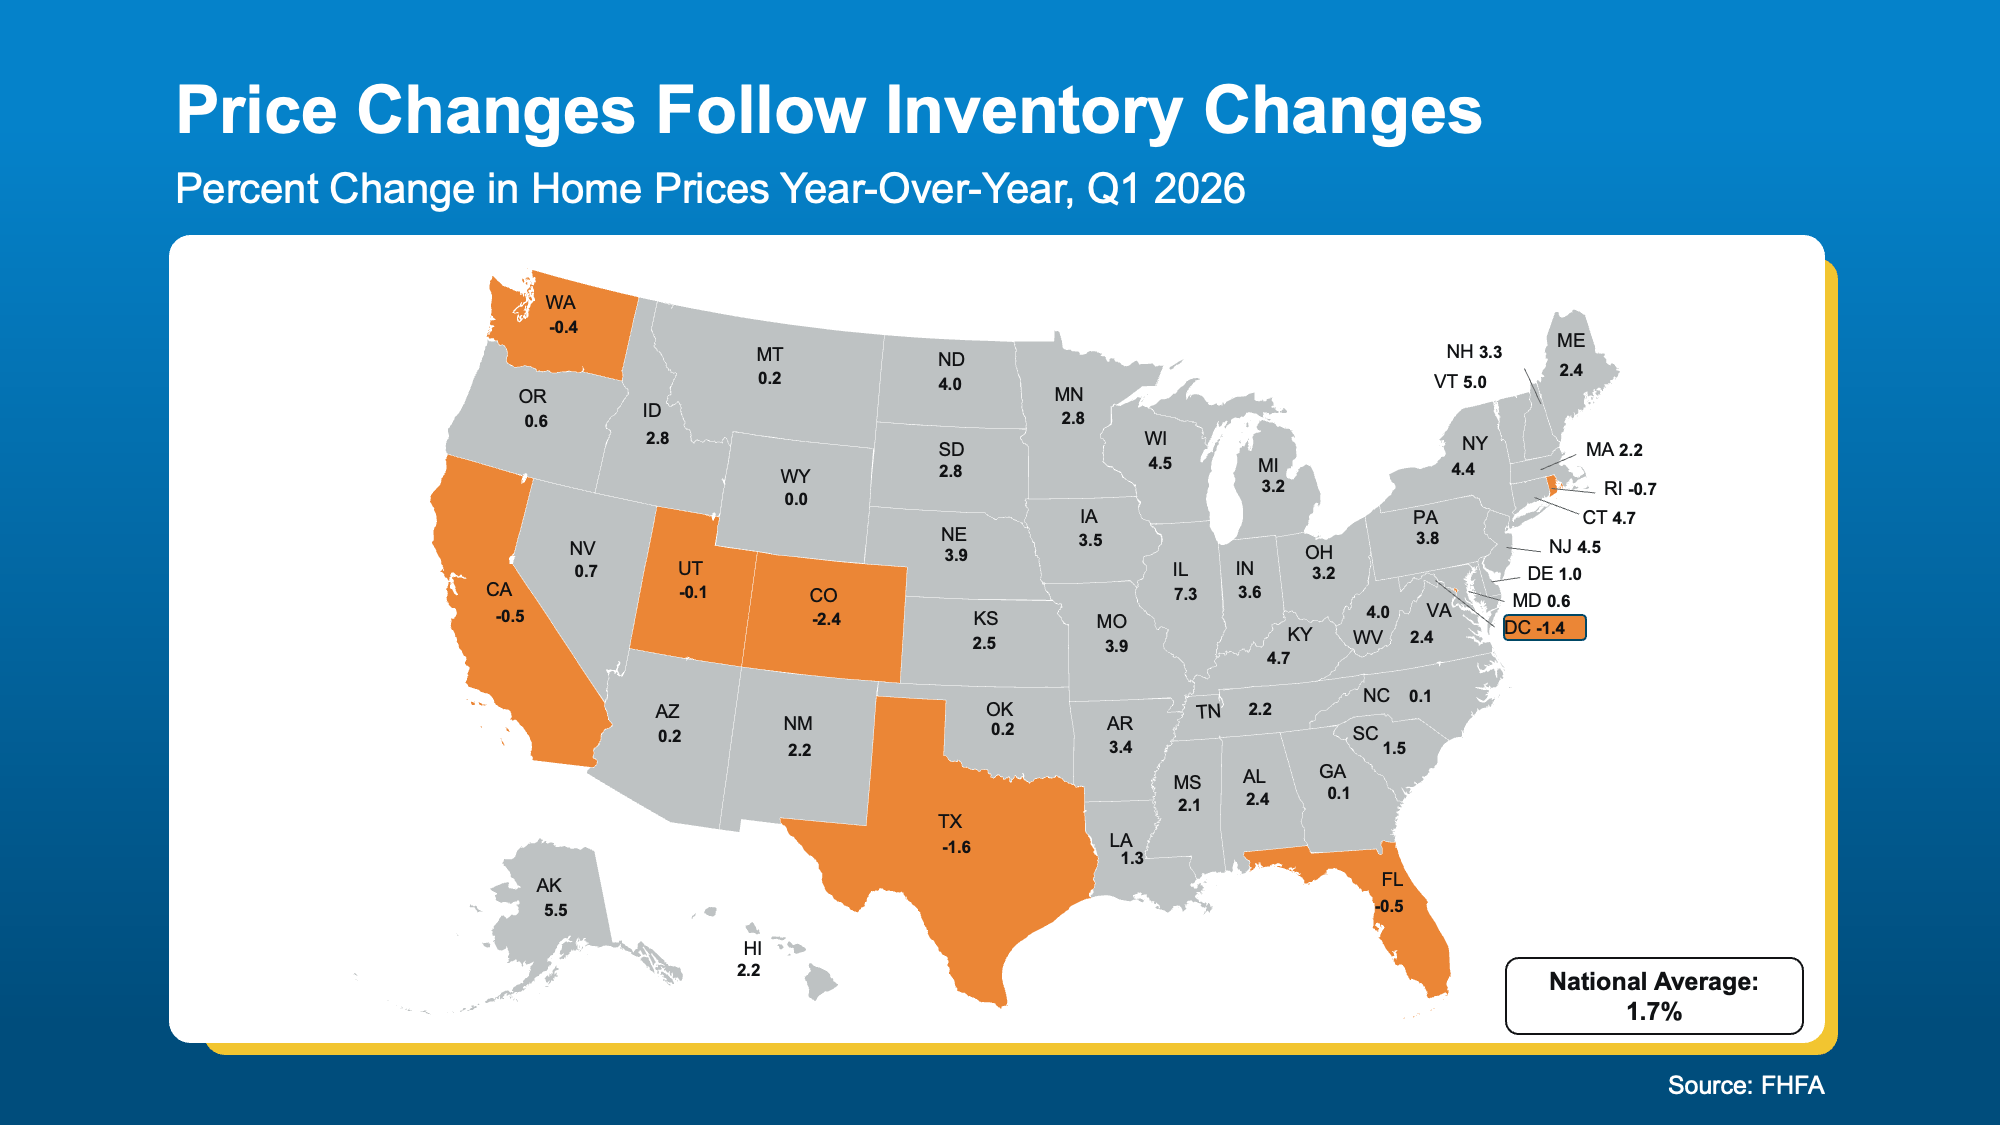
See how those line up pretty closely with the areas seeing more homes for sale today?

The overlap isn’t a coincidence. It’s cause and effect. 

a map of the united states

The national average of 1.7% price growth is accurate, but it’s an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.

What This Means If You’re Buying or Selling 

If you’re a buyer, the market you’re shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you’re still likely facing a lot of competition.

If you’re a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you’re in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that’s where a local real estate agent earns their keep.

Bottom Line

When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.

Reach out to a local real estate agent today and work together to build a plan that fits your market.

Your House Didn’t Sell. Here’s How To Turn It Around.

Your House Didn’t Sell. Here’s How To Turn It Around.

Your House Didn’t Sell. Here’s How To Turn It Around. Simplifying The Market

When your house doesn’t sell, it’s not just disappointing. It messes with your timing. Your plans. Your confidence. You start second-guessing everything, including the decision to move in the first place. And that raises 2 big questions: 

Do you try again?

Is that even worth it?

Here’s the secret to getting a better outcome the second time around.

Different Agent. Different Results.

Most sellers who re-list and ultimately sell don’t wait for market to magically change. They change their approach. And there’s data to back that up.

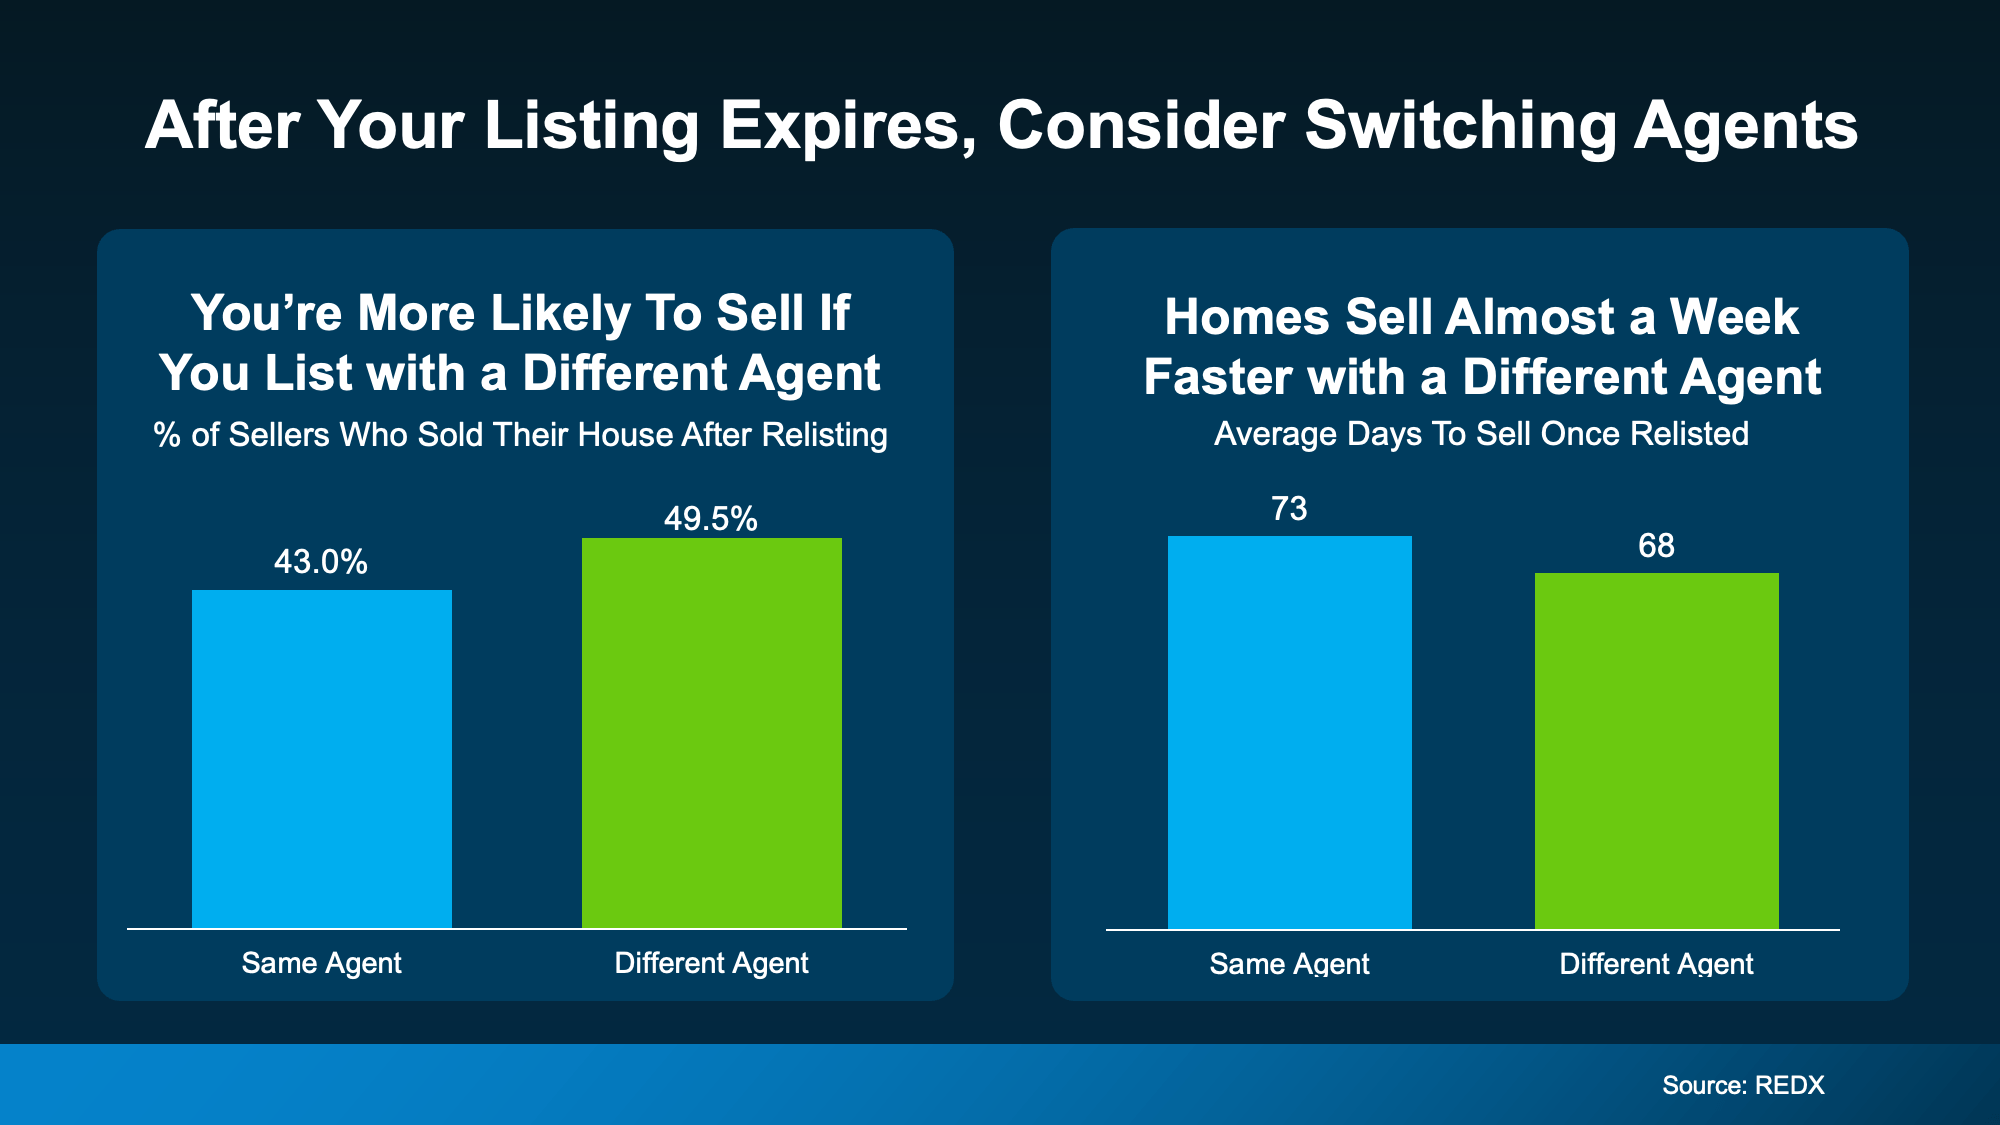
Research from REDX shows homeowners who put their house back on the market with a different agent are more likely to sell than homeowners who re-used the same agent. Not to mention, they see their homes sell faster (see graph below): 

a screenshot of a graph

That’s the power of a fresh set of eyes. Because in a moment like this, the worst thing you can do is rerun the same set of plays and expect a different outcome. A different agent can bring a new perspective on where things went off track – and a lot of the time, one of these things happened.

1. The Asking Price Didn’t Match Buyer Reality

There’s a saying that’s especially important in today’s market, and it’s: if your price isn’t compelling, it’s not selling.” Maybe that’s what happened with your house.

With mortgage rates where they are and inflation driving up the cost of everyday purchases, buyers have less room to stretch. If they feel like your house is priced even a little high, it’s going to get skipped over. And if no one looks at it, it’s not going to sell.

The Fix: Price to draw buyers in, not push them away. Have an agent pull fresh data from recent sales so your asking price matches what buyers are actually paying right now. 

2. The First Impression Didn’t Win the Click 

Most buyers decide whether they want to tour a home in seconds. If the photos look dark, or dated, they scroll right past. And while you may think: “If they just saw it in person, they’d get it,” you may not get that chance.

And honestly, even in person, small things can quietly kill momentum – worn down paint, outdated fixtures, clutter, or a yard that feels high-maintenance. Individually, they’re small. Stacked together, they create doubt.

The Fix: Walk the house like you’re a buyer, not the owner. Start with what’s easy and obvious – paint, lighting, curb appeal, decluttering. Then update the photos so they match the best version of your house.

3. The Marketing Was Too “Set It and Forget It”

Today, the number of homes for sale has grown in many areas. Buyers have more options, which means your house needs a plan to stand out. A generic description and a basic upload to the MLS can blend in fast.

The Fix: Find an agent who can build stronger exposure through digital marketing and social platforms, plus content that makes buyers stop – strong photos, a smart description, a video walk-through, and a plan for open houses and follow-up.

4. There Was No Clear Plan for Feedback

Sometimes the house gets showings, but no offers. If that was your experience, it actually tells you something important. Buyers liked it enough online to come see it. So, something else was holding them back.

Those buyers were sending a message. It just wasn’t translated into action. 

The Fix: Make sure your agent has a clear plan for seeking out and acting on feedback quickly. That dialogue often points to the one change that would get a house sold.

5. The Deal Couldn’t Get Over the Finish Line 

Even when a house is priced well and marketed right, deals fall apart when there’s no plan for the human side of the transaction.

Buyers today are more likely to ask for repairs, credits, or help with closing costs than a few years ago. In this type of market, being unwilling to negotiate can cost you more than a reasonable concession ever would.

The Fix: Decide ahead of time what matters most to you and where you can be flexible. Keep the dialogue open and lean on your agent for advice.

Bottom Line

If your house didn’t sell the first time, you’re not stuck. You just need a different strategy, and maybe a different partner.

When you’re ready for a fresh set of eyes on what happened and what to change first, connect with a local agent.

More Sellers Are Taking Their Homes off the Market. Here’s What You Need To Know.

More Sellers Are Taking Their Homes off the Market. Here’s What You Need To Know.

More Sellers Are Taking Their Homes off the Market. Here’s What You Need To Know. Simplifying The Market

You may be hearing that a near-record number of homeowners are pulling their houses off the market. And if that headline has you thinking, “Wait… is something bad about to happen?” You’re not alone.

Because when people start stepping to the sidelines, it sounds like a warning sign that something’s coming – or that they realize something you don’t know.

Here’s the thing. This trend gets spun like it means the market is about to crash. But the data tells a more practical story.

What the Numbers Actually Say

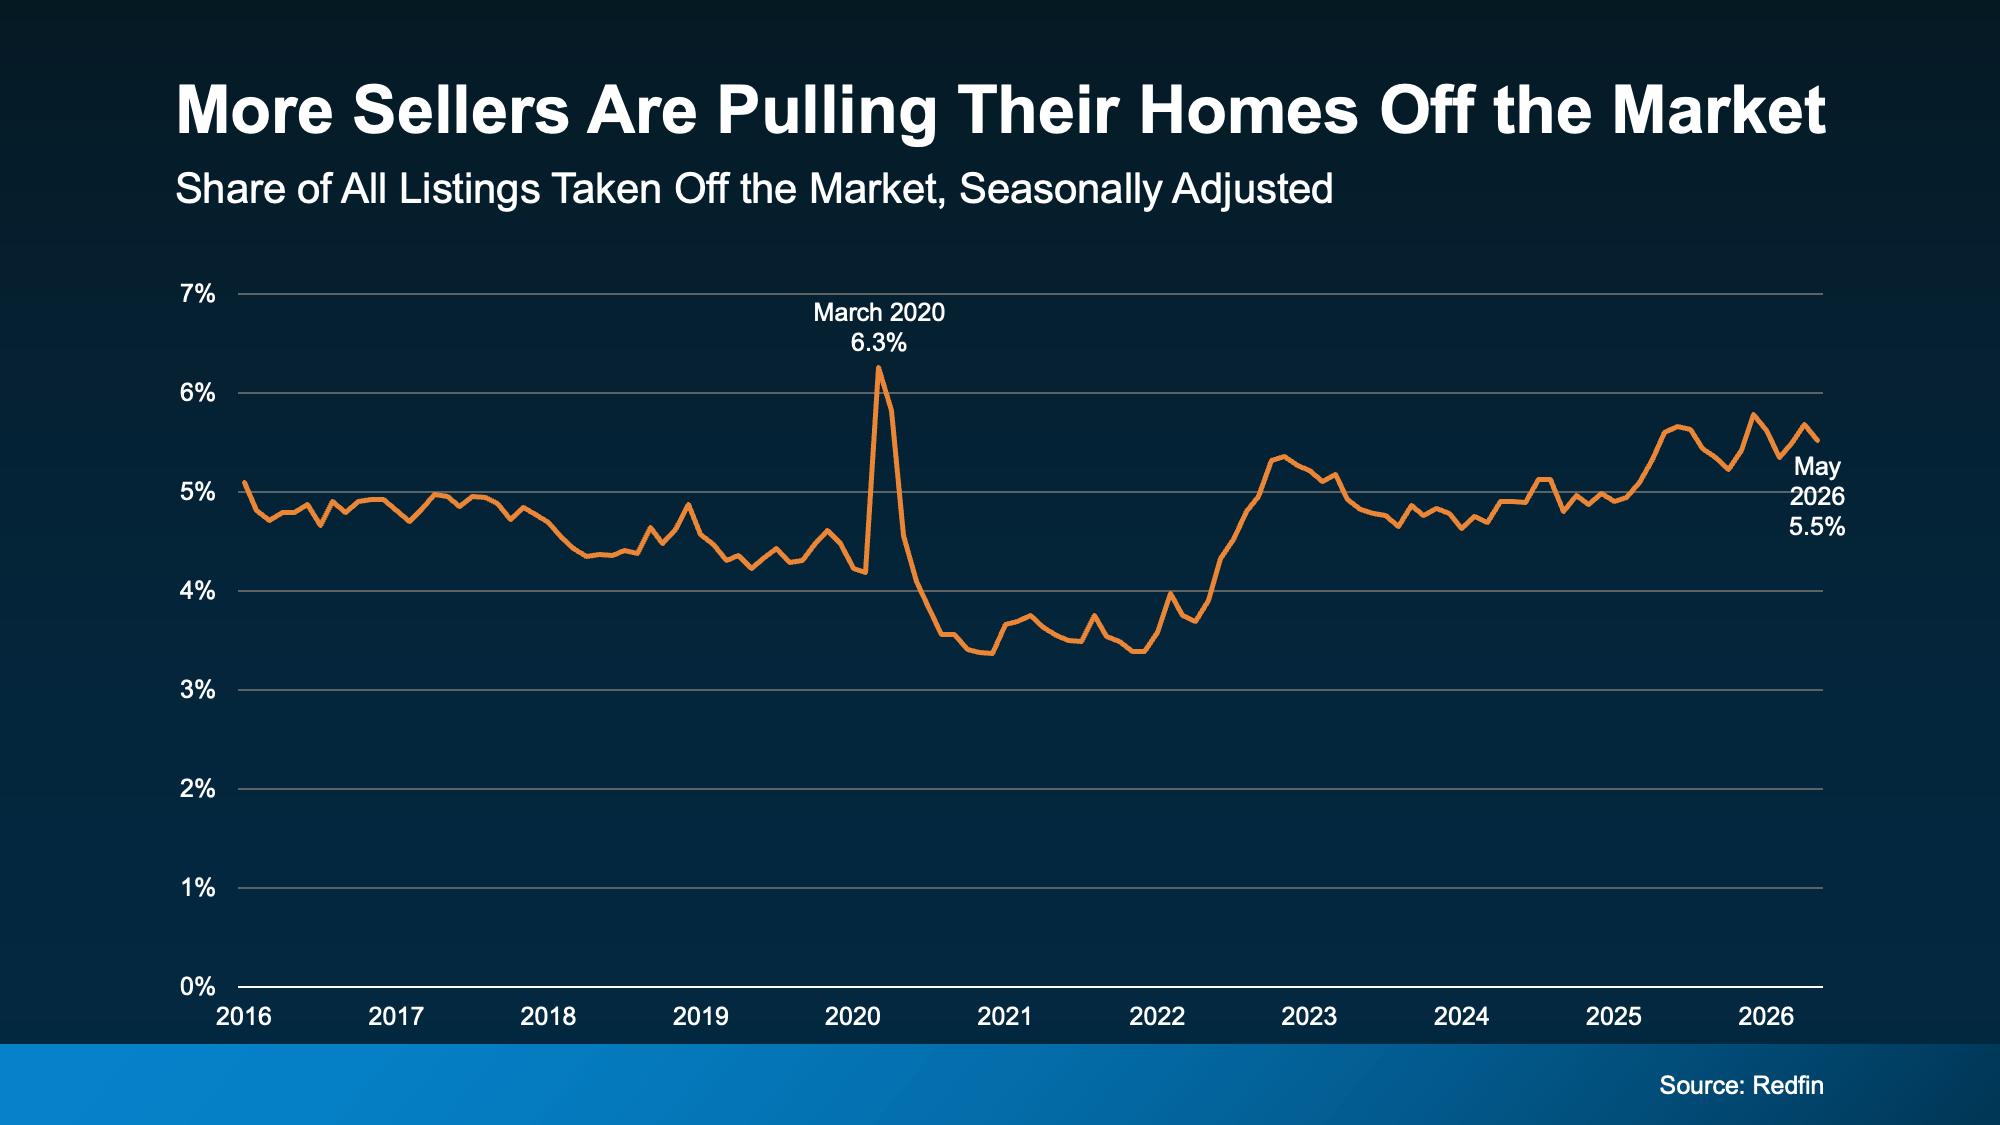
According to the latest data from Redfin, 5.5% of all listings were taken off the market in May. And it’s true that’s almost the highest it’s been since back in March 2020 (see graph below): 

a graph showing the price of a home

That can sound scary. But a lot of the fear comes from how this story gets told. “A near record number of sellers are pulling their listings” makes a great clickbait headline – and that sort of thing spreads fast, especially online. But sellers pull a house off the market for plenty of reasons that have nothing to do with a crash.

Redfin points to four main forces driving this trend:

  • Homes are taking longer to sell. When the pace slows down, some sellers get frustrated and decide to hold off.

  • The number of homes for sale is rising faster than demand. That means buyers have more options. And sellers who don’t price or prep right may not get many eyes on their house.

  • Some sellers still have pandemic-era price expectations. A price that would’ve worked a couple years ago may not match what today’s buyers will pay.

  • Economic uncertainty is making both buyers and sellers cautious. Buyers pause. Sellers second-guess. And that has an impact on overall sales volume and pace.

Notice what’s missing from that list? There isn’t a single mention of an impending market crash or price collapse.

This is about a shifting pace, more competition, and sellers deciding how they want to respond.

One Detail Most Headlines Leave Out

Want more peace of mind that this isn’t a crash? This next stat delivers. Yes, more sellers are taking their homes off the market. But Redfin also shows something you’re not going to see in social posts…

The number of re-listings is growing too.  

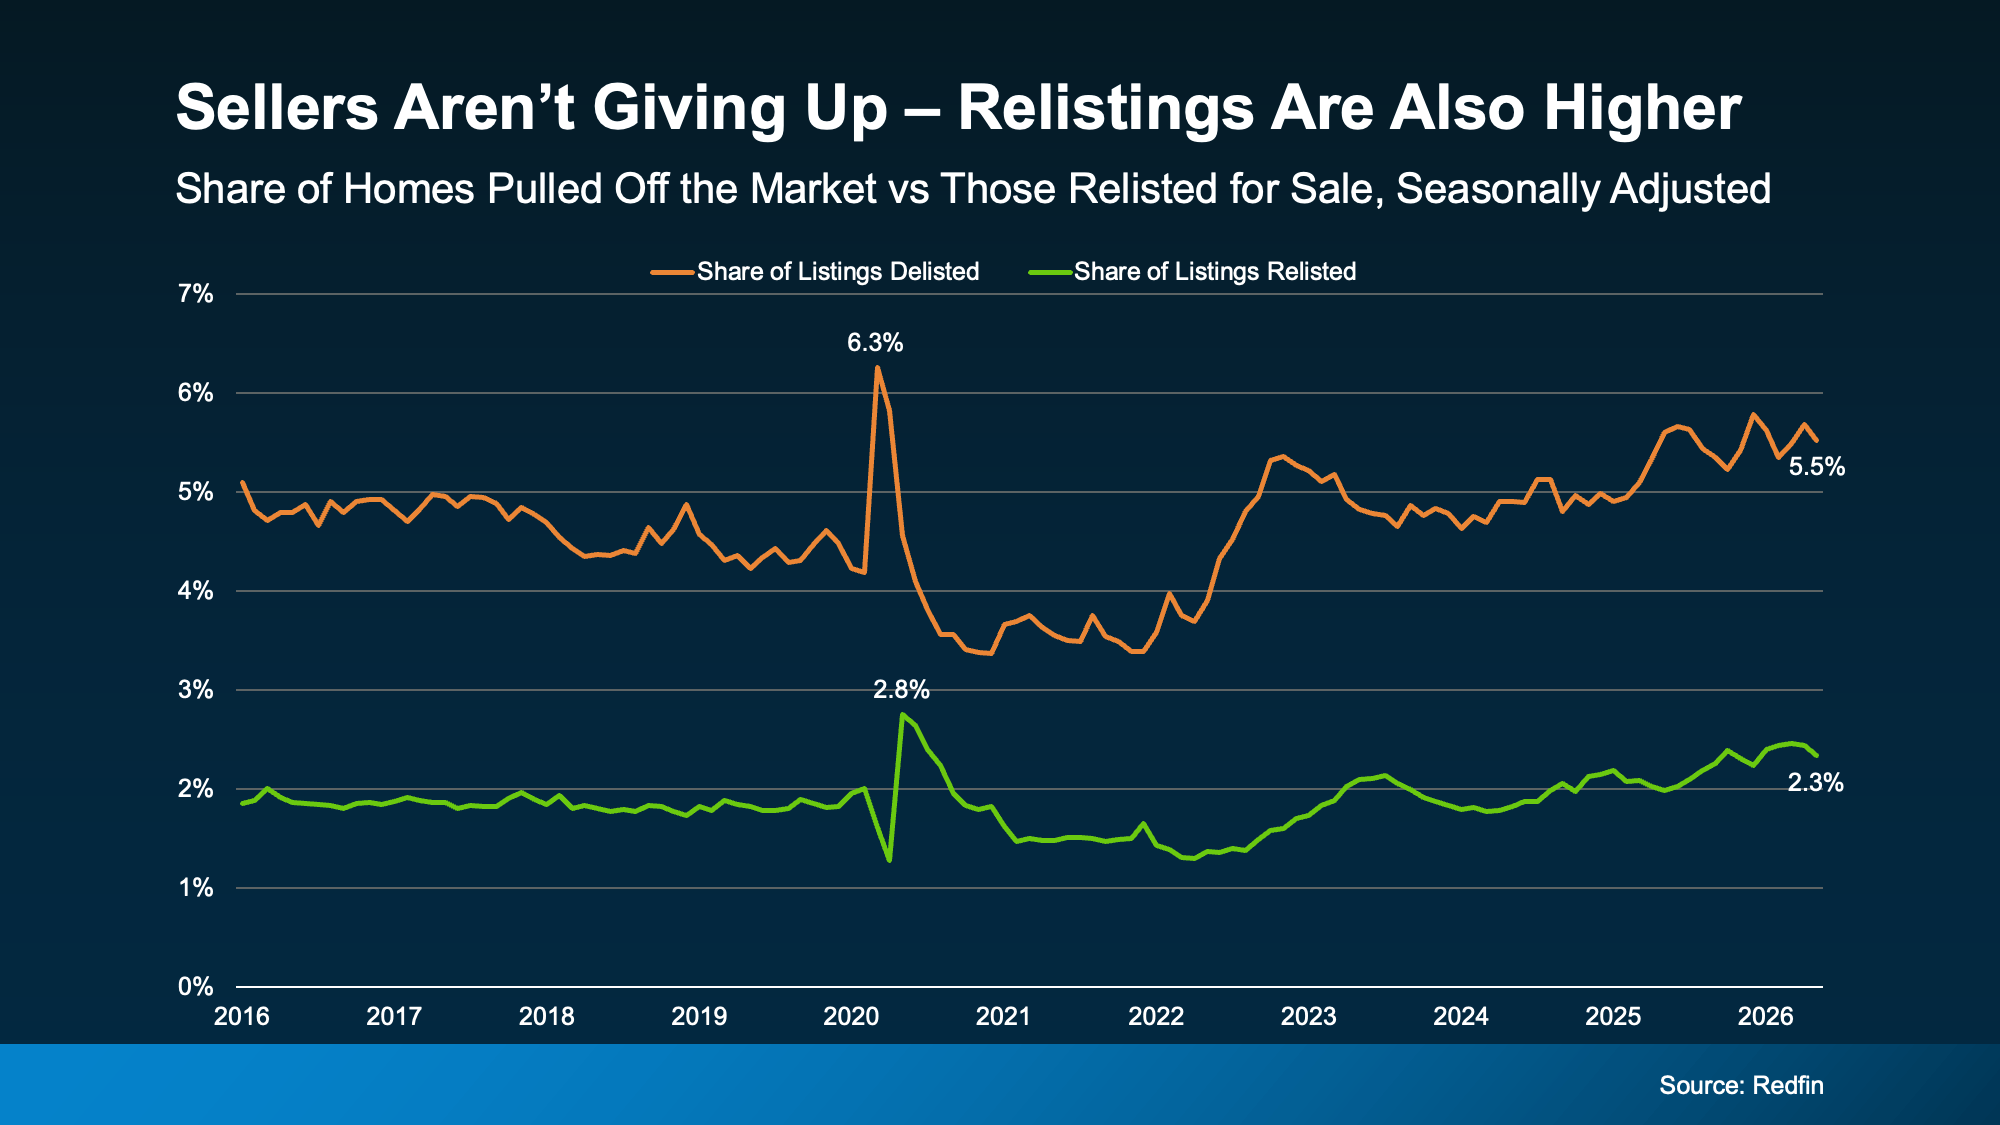
While more sellers are pulling their listings, more are also deciding to give selling a second shot too. This is pretty much the highest re-listings have been since the pandemic hit.

While 5.5% got pulled in May, 2.3% were also put back on the market (see graph below):

a graph of sales and prices

That’s a signal sellers aren’t giving up or running away in large numbers.

Some are simply stepping away briefly before deciding to try again. That tells you this often isn’t a permanent decision. In many cases, it’s a pause – and the seller comes back with a different approach.

A lot of the time that change in the overall strategy is all that’s needed to finally get a house sold. 

And just in case you need more proof this isn’t a reason to worry, check this out. Buyer activity may be starting to pick back up – and that could bring more sellers back in or, at least, prevent some sellers from pulling back. 

The National Association of Realtors (NAR) reports existing home sales increased 3.2% in May. That’s the biggest increase since December. As the Wall Street Journal puts it: 

“Home sales in May posted the biggest rise this year, a sign that the housing market’s crucial spring selling season may be showing signs of life after a sluggish start.”

That doesn’t sound like a market in trouble.

Bottom Line

If you’re seeing headlines about how a record number of sellers are taking their homes off the market, don’t panic. It’s not a warning of an impending crash. It’s a market adjusting.

Is It Still a Seller’s Market? Here’s What the Data Says.

Is It Still a Seller’s Market? Here’s What the Data Says.

Is It Still a Seller's Market? Here's What the Data Says. Simplifying The Market

Remember a few years back when sellers held all the power and buyers were stuck offering way over asking or waiving inspections just to get a chance at the house? In many markets, those days are behind us.

While it’s going to vary by area, more metros are slowly shifting to favor buyers, and the market is starting to look a lot more like a two-way street again.

And that balance is something we haven’t had in a while.

Whether you’re buying or selling, here’s what you need to know about what’s changing and what it means for your move.

The Most Buyer-Friendly Market in Years

The national data tells an interesting story right now. According to Realtor.com:

“The national housing market is balanced but gradually loosening as the cycle moves in a more buyer-friendly direction . . .

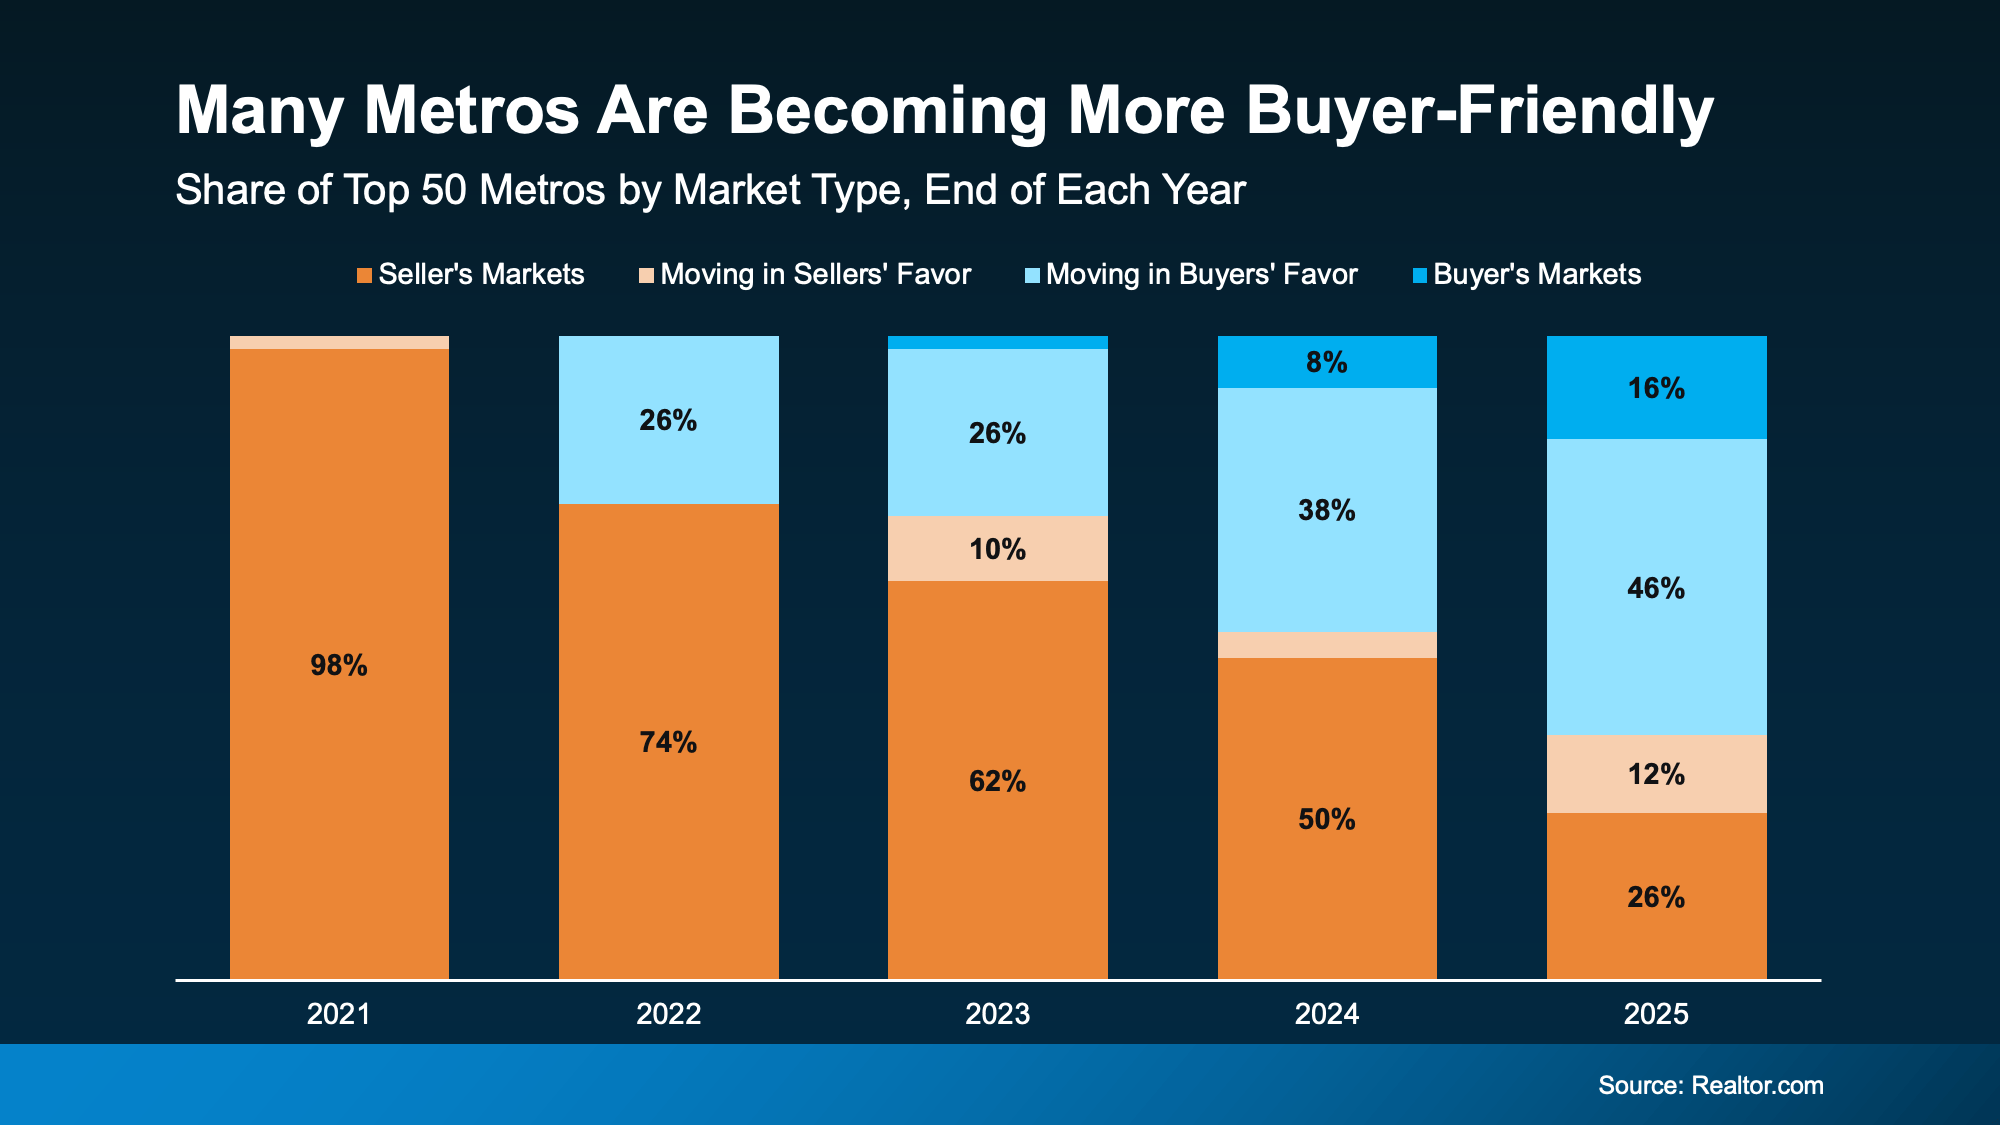
That’s because, over the past few years, more and more metros have been flipping back to more buyer-friendly terms as inventory’s grown. And when you zoom in on the latest Realtor.com data for the top 50 metro markets over time, the trend becomes really clear (see graph below).

Back in 2021, almost all major metros were seller’s markets. By the end of 2025, only 1 in 3 still favored sellers. That’s an obvious shift.

a graph of sales

And that changes how the market is going to feel for everyone. Sellers shouldn’t still expect 2021 conditions, but neither should buyers. At least, not generally speaking.

It’s Not the Same Story Everywhere

That said, who has the power ultimately depends on where you live. While more metros are leaning buyer-friendly lately, there are still plenty of strong seller’s markets right now, too.

It really comes down to how much housing supply and demand there is in your area. And that varies enormously by region.

Sun Belt cities like Austin, Tampa, and San Antonio saw major building booms in recent years, giving buyers more options and more negotiating room. Meanwhile, cities in the Northeast and Midwest – think Rochester, Hartford, and Buffalo – didn’t see that same wave, so inventory stayed tight and competition stayed fierce. As Jeff Ostrowski, Housing Analyst at Bankrate, explains:

“The formerly hot Sun Belt markets have cooled, while the Northeast and Midwest have stayed hot. The big driver here is construction activity. The softest markets now [have] experienced big booms that spurred new building, and that has led to a large supply of new and existing homes on the market in those places.”

Practical Advice for Your Move

To find out who has the power in your local market, talk to an agent. Because knowing what’s happening locally is going to be the key to setting the right strategy for your move.

If the market is working in your favor, great. Lean in and use it to your benefit. But if it’s not, all hope isn’t lost. Your agent can help you figure out how to approach any market.

Here’s some practical advice if there’s a mismatch between your goal and local market conditions.

If you’re buying in a seller’s market:

  • Get pre-approved before you start shopping. It shows sellers you’re serious.

  • Be ready to act fast when the right home hits the market.

  • Consider offering a quick closing date or flexible terms.

  • Work closely with your agent to craft a competitive offer.

If you’re selling in a buyer’s market:

  • Price it right from day one. Overpricing will cost you time and money.

  • Focus on curb appeal and staging to stand out in areas with more inventory.

  • Be open to offering incentives, like covering closing costs or a home warranty.

  • Expect buyers to negotiate and be ready to be flexible.

Bottom Line

Right now, local markets are moving in very different directions. And your strategy as a buyer or seller should reflect your market.

Want to know which way your local market is leaning and what that means for your move? Talk to a local real estate agent.

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know. Simplifying The Market

A few years ago, sellers could get away with saying “no” to just about everything.

No repairs.

No concessions.

No negotiation.

If buyers wanted the house, they pretty much had to take it on the seller’s terms. But now that inventory’s grown, negotiations are becoming a normal part of the process again.

That’s why one of the most important things sellers need to understand right now is this:

The goal isn’t to “win” every negotiation.

Sometimes, it’s worth meeting buyers where they are to get a deal done, fast. One example? Helping with a buyer’s closing costs.

Let’s break that down, so you know what to expect if it comes up in your sale.

What Are Buyer Closing Costs?

Closing costs are the extra expenses buyers pay on top of their down payment when they purchase a home. Freddie Mac gives some examples:

  • Loan origination fees

  • Appraisal and inspection costs

  • Title and attorney fees

  • Survey fees and more

Typically, buyer closing costs range from about 2% to 5% of the home’s purchase price. So, on the typical $400,000 home, that could mean anywhere from $8,000 to $20,000 out of pocket.

And in today’s affordability-challenged market, that upfront cash can be a major hurdle for some buyers – even if they can comfortably afford the monthly mortgage payment itself. 

That’s why more people are asking sellers for help.

And More Sellers Are Saying “Yes”

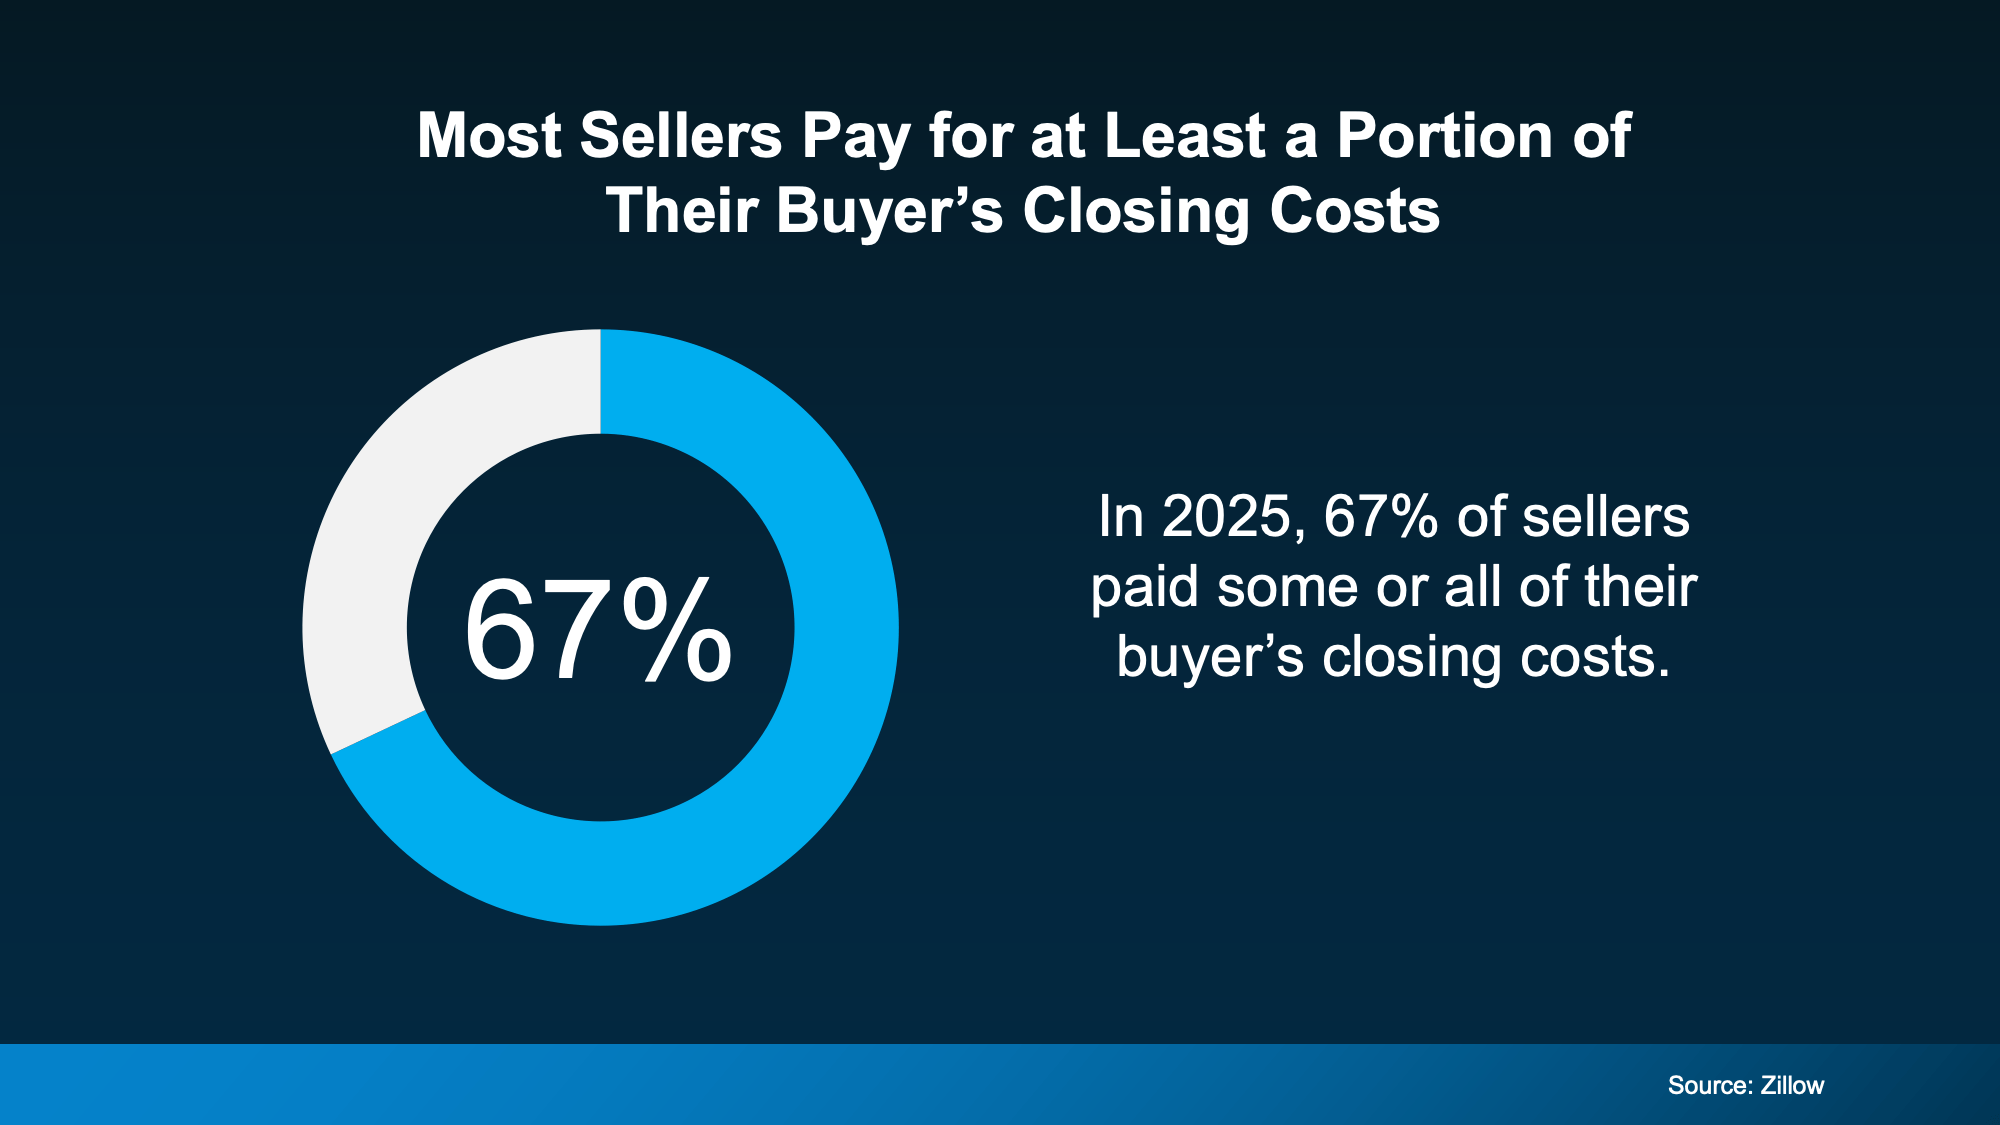
According to the latest data from Zillow, 67% of sellers reported paying some or all of the buyer’s closing costs in 2025 (see chart below):

a blue circle with white text

Now, that doesn’t mean every seller is doing it. And it definitely doesn’t mean every seller should. But it does show how common concessions have become as the market has shifted. And that’s important for you to know.

When Paying Closing Costs May Make Sense

This is where many sellers get stuck. They hear “help with closing costs” and immediately think: “Why should I pay for their expenses?”

But that’s not always the right way to look at it. You’ve got to consider who has the leverage in today’s market.

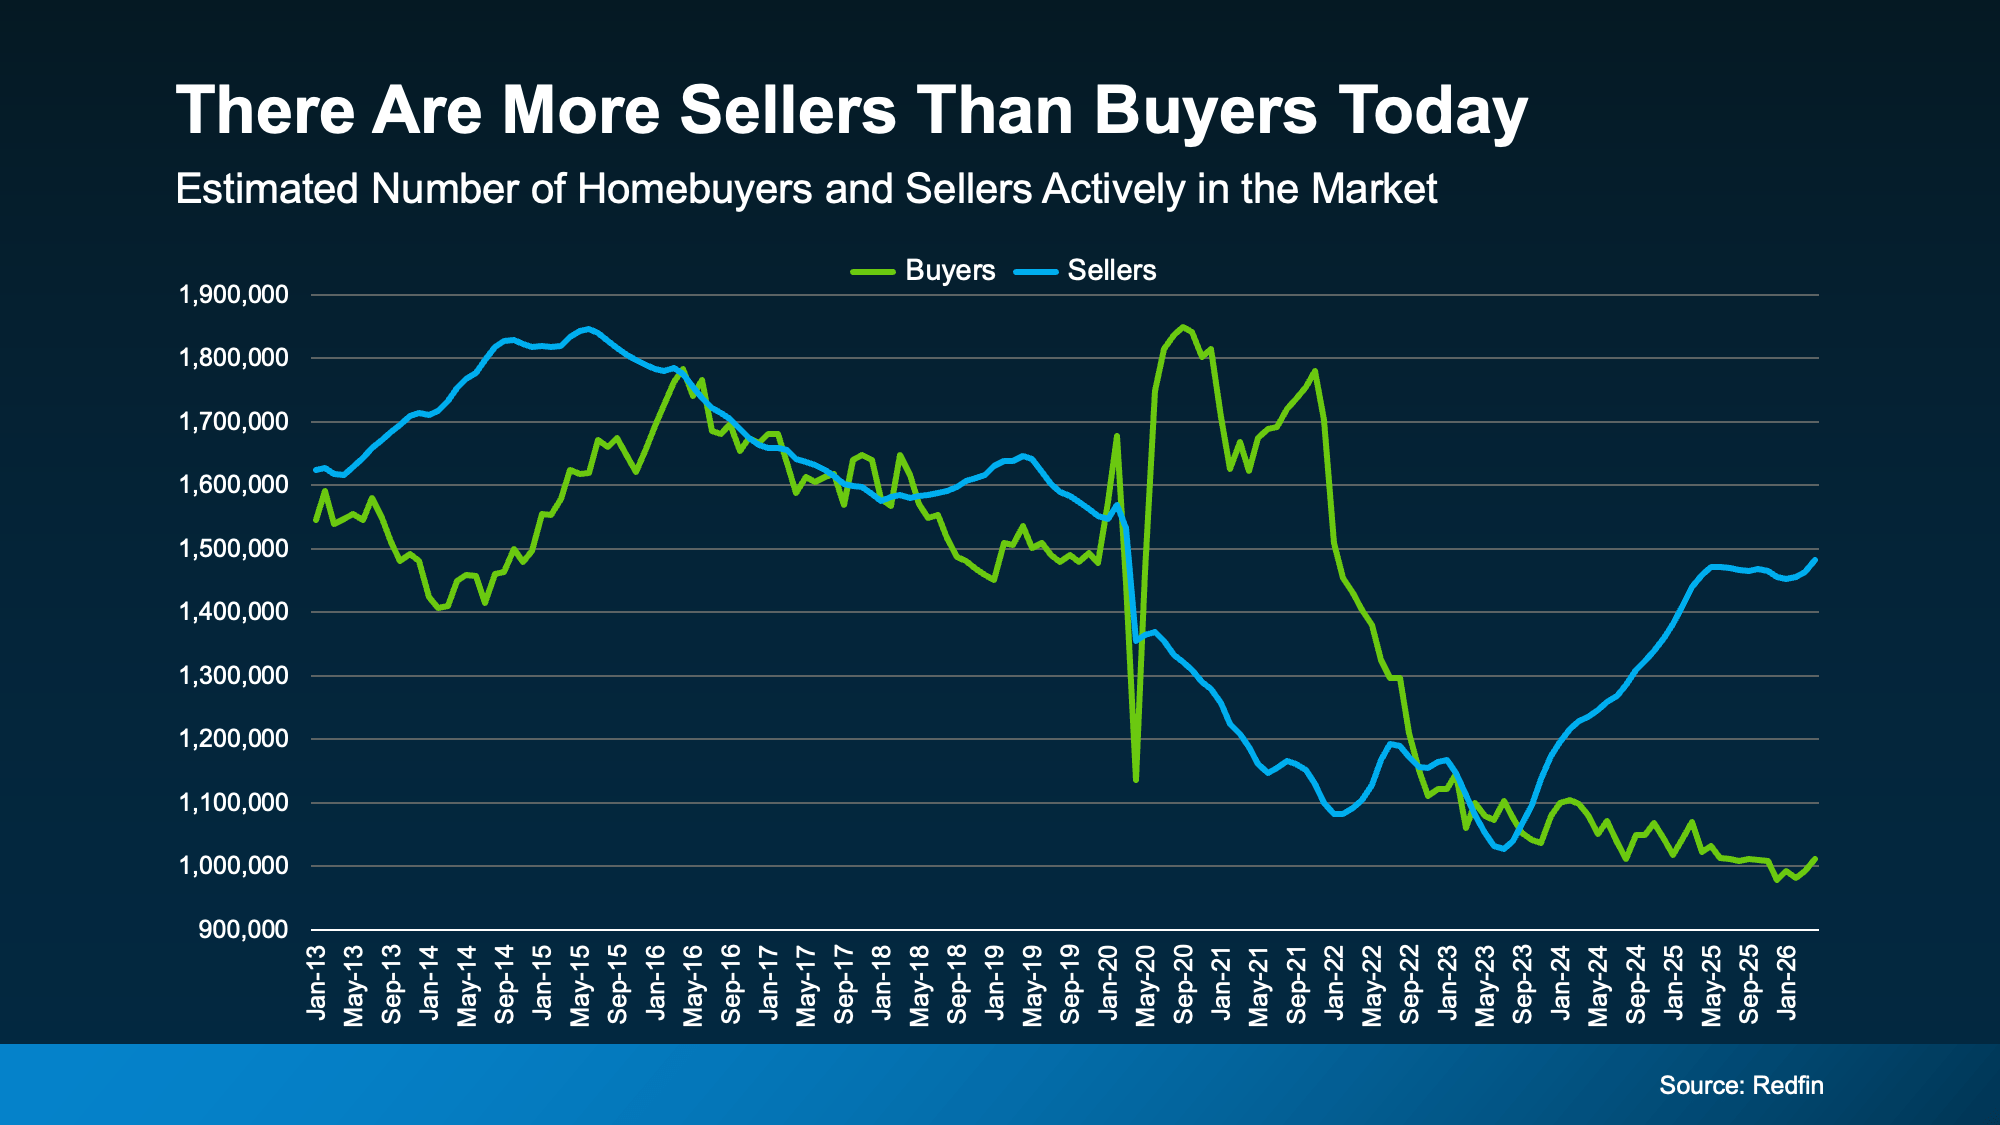
Redfin data shows there are more sellers than buyers active today. And that shifts the market dynamics (see graph below):

a graph of sales and buyers

That doesn’t mean every market favors buyers. Far from it. In some areas, homes are still selling quickly and sellers have plenty of leverage. But in others, buyers have more room to negotiate than they’ve had in years.

That’s why local market conditions matter so much when you make your decision.

For example, helping with closing costs may be worth considering if:

  • There are a lot of homes for sale in your area

  • Your house has been sitting on the market longer than expected

  • You’ve had showings, but no offers

  • You’re motivated to move quickly

  • Or you’re trying to keep a deal together during negotiations

After all, if it’s the thing that helps bring a serious buyer across the finish line, it could be well worth it.

Other Concessions You Could Offer Instead

Just remember, being flexible doesn’t mean saying “yes” to every request.  It means understanding which compromises actually help you accomplish your goals. Because there are always alternatives.

Redfin suggests considering other concessions if you’re not interested in helping with closing costs, like:

  • A home warranty

  • Repair credits

  • Flexible closing dates, or

  • Leave behind appliances or furniture

The right answer depends on what buyers in your market are asking for and what matters most to you. That’s exactly why working with an experienced local agent is so important.

Bottom Line

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for your local market.

If you’re wondering what’s normal in your area, what’s worth negotiating, and where it makes sense to stand firm, connect with an agent.

Pin It on Pinterest