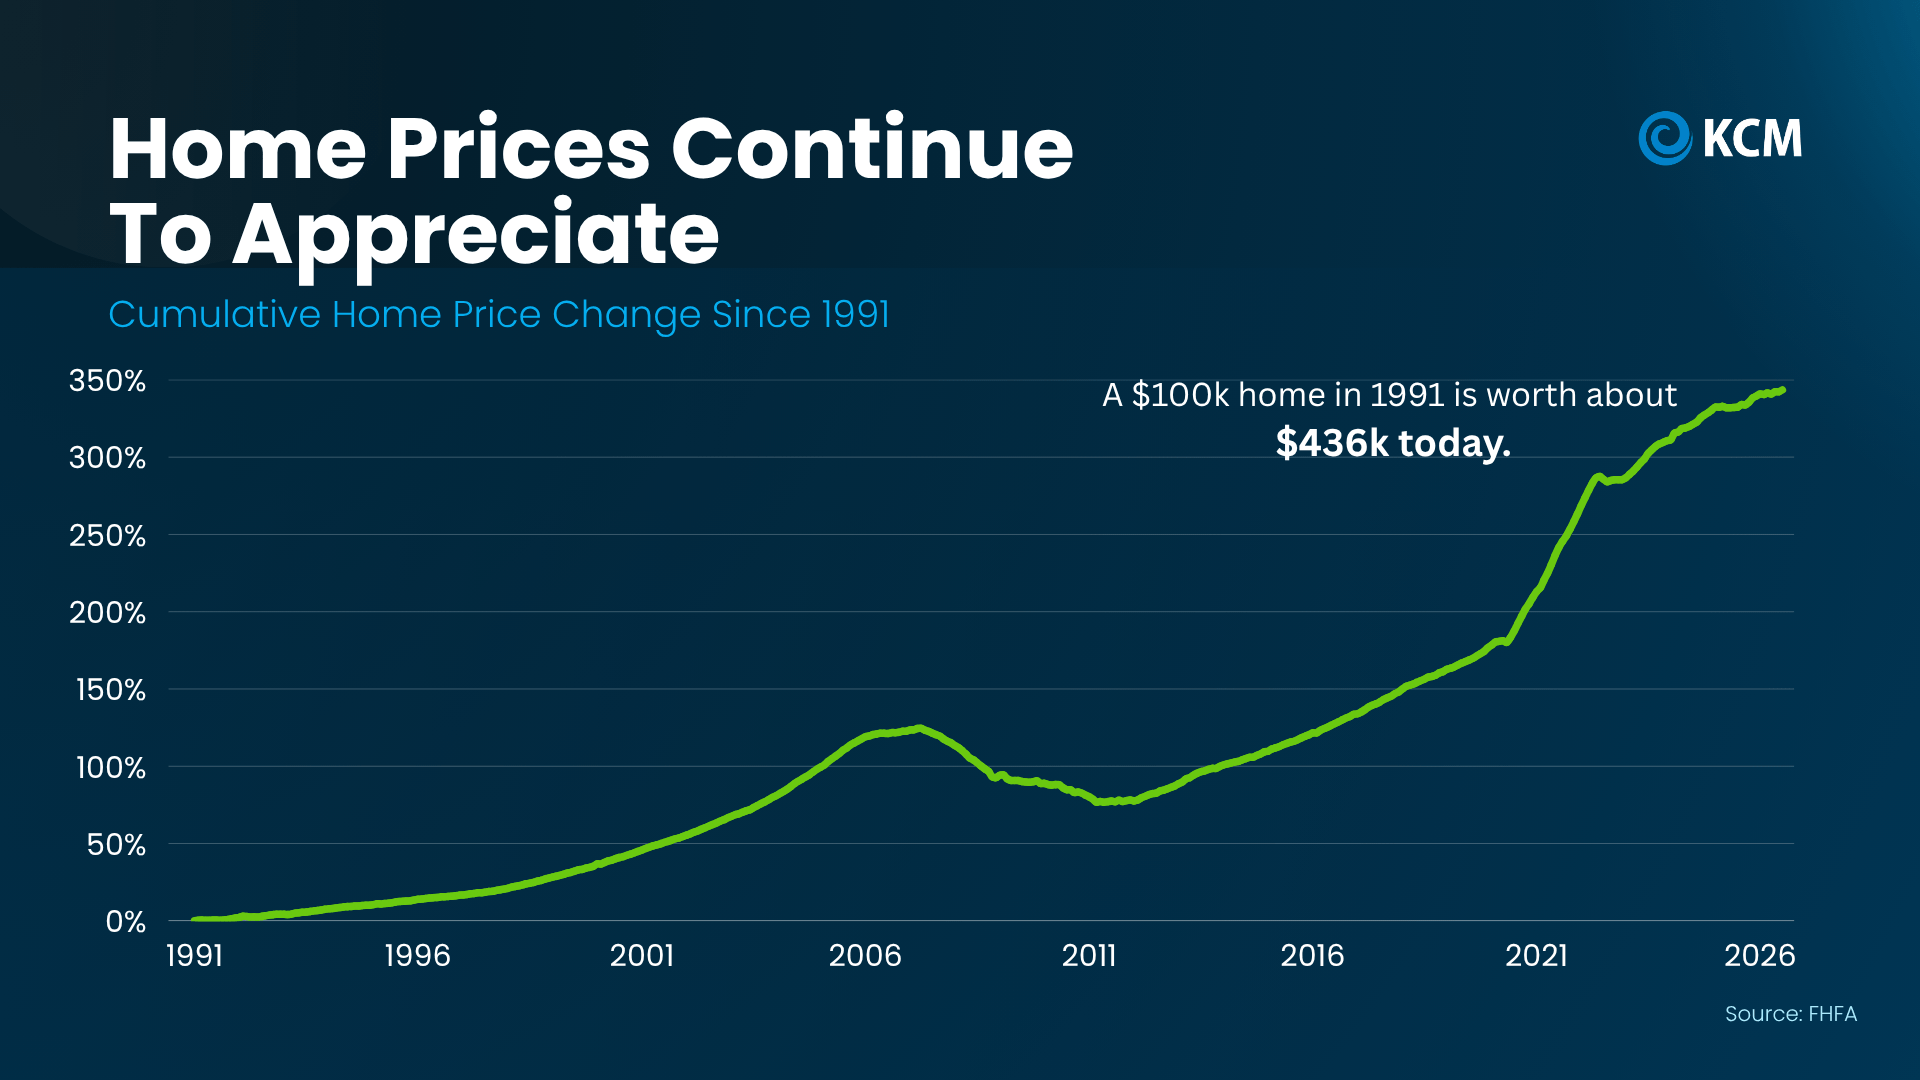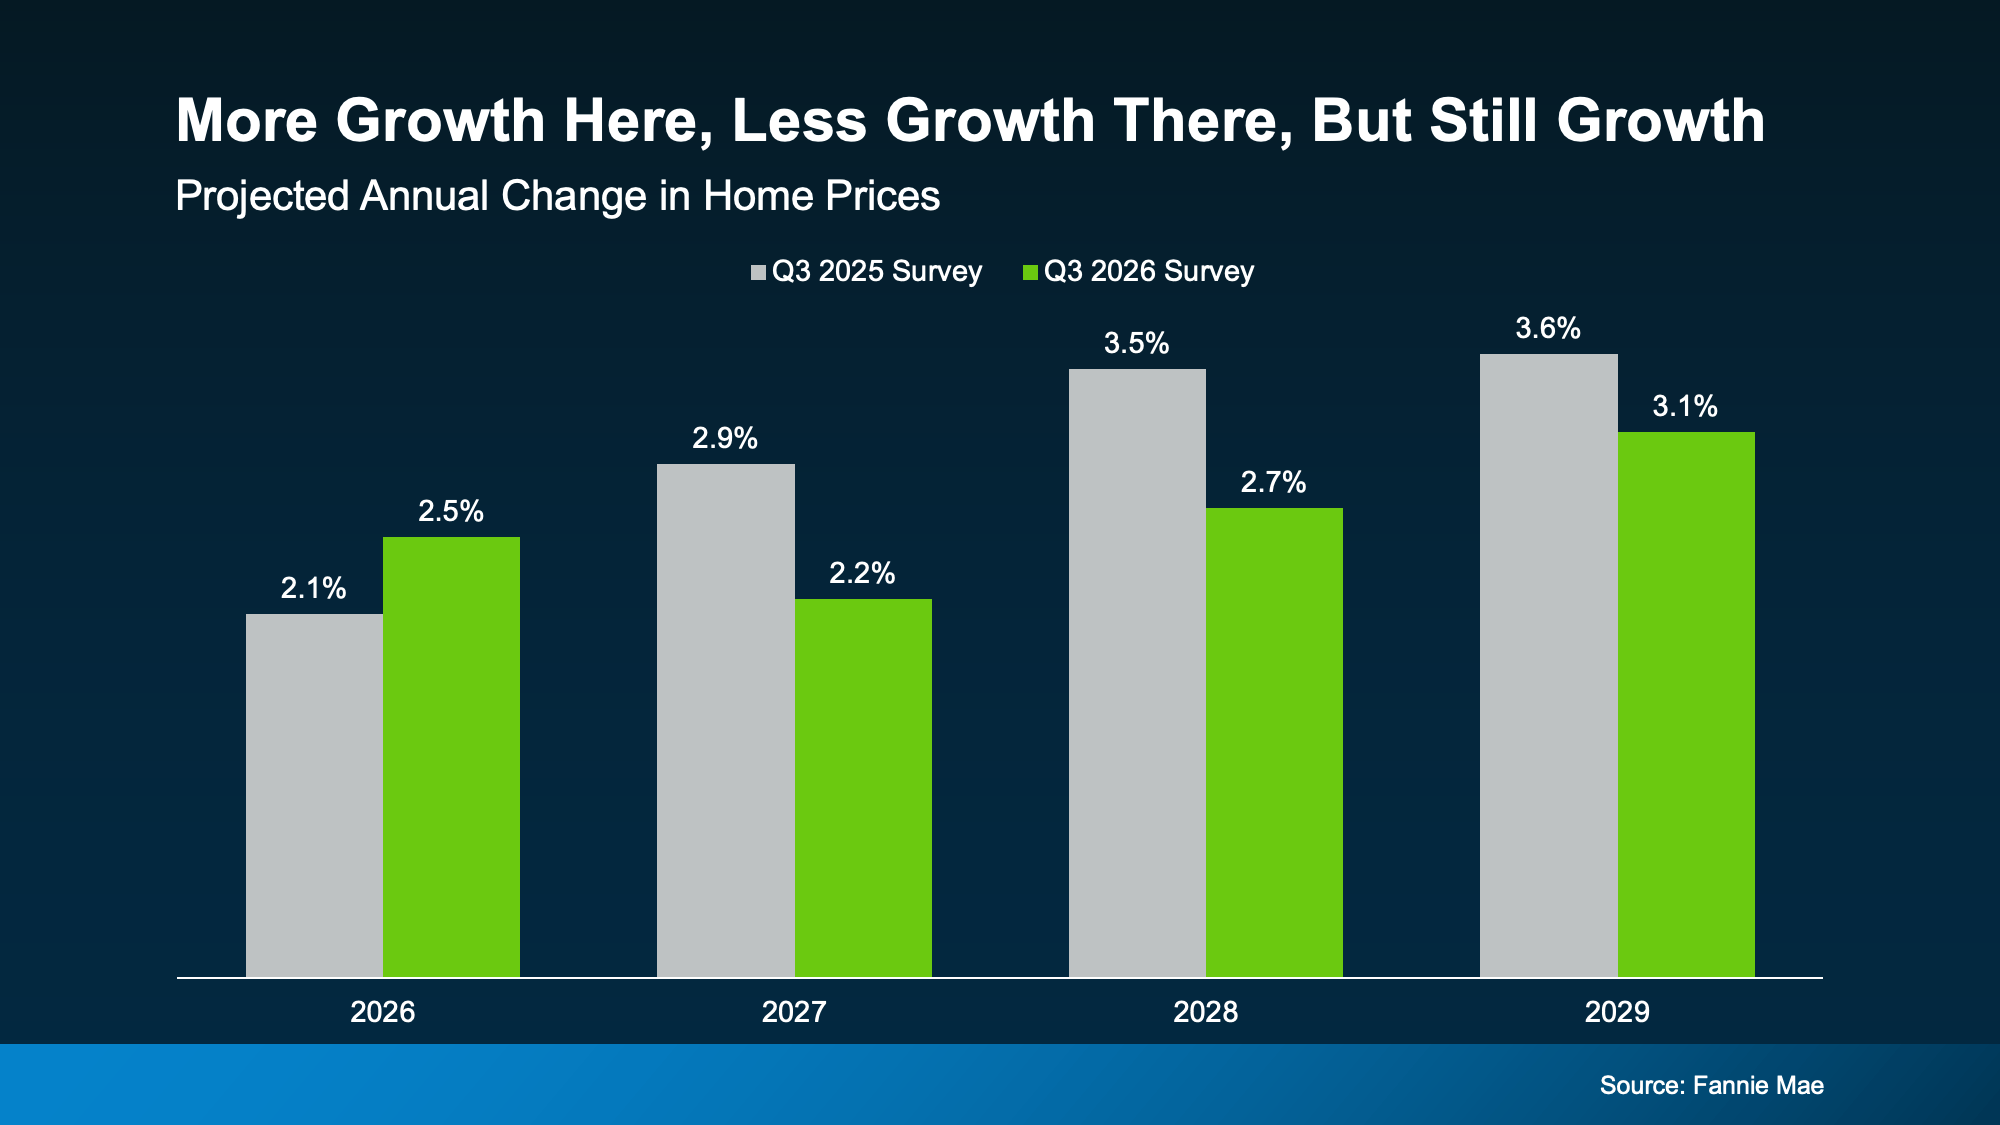
A Fixer-Upper Could Be Your Path To Homeownership

A Fixer-Upper Could Be Your Path To Homeownership
A Fixer-Upper Could Be Your Path To Homeownership Simplifying The Market

When the homes you love keep landing outside your budget, it may be time to look at the ones other buyers skip.

A fixer-upper won’t be the right call for everyone. Plenty of buyers want a home that’s ready on move-in day. But homes that need some updating could get you in the door for a lot less. 

More buyers are starting to realize it too. And Danielle Hale, Chief Economist at Realtor.com, explains why:

“Fixer-uppers give buyers a way to break into the housing market at a time when affordability is still stretched thin. For those with the vision. . . fixer-uppers provide both a starting point in the market and the chance to create a home that’s truly their own.”

If that sounds like you, here’s why a fixer-upper could be worth a closer look.

The Price Tag Is Usually Lower

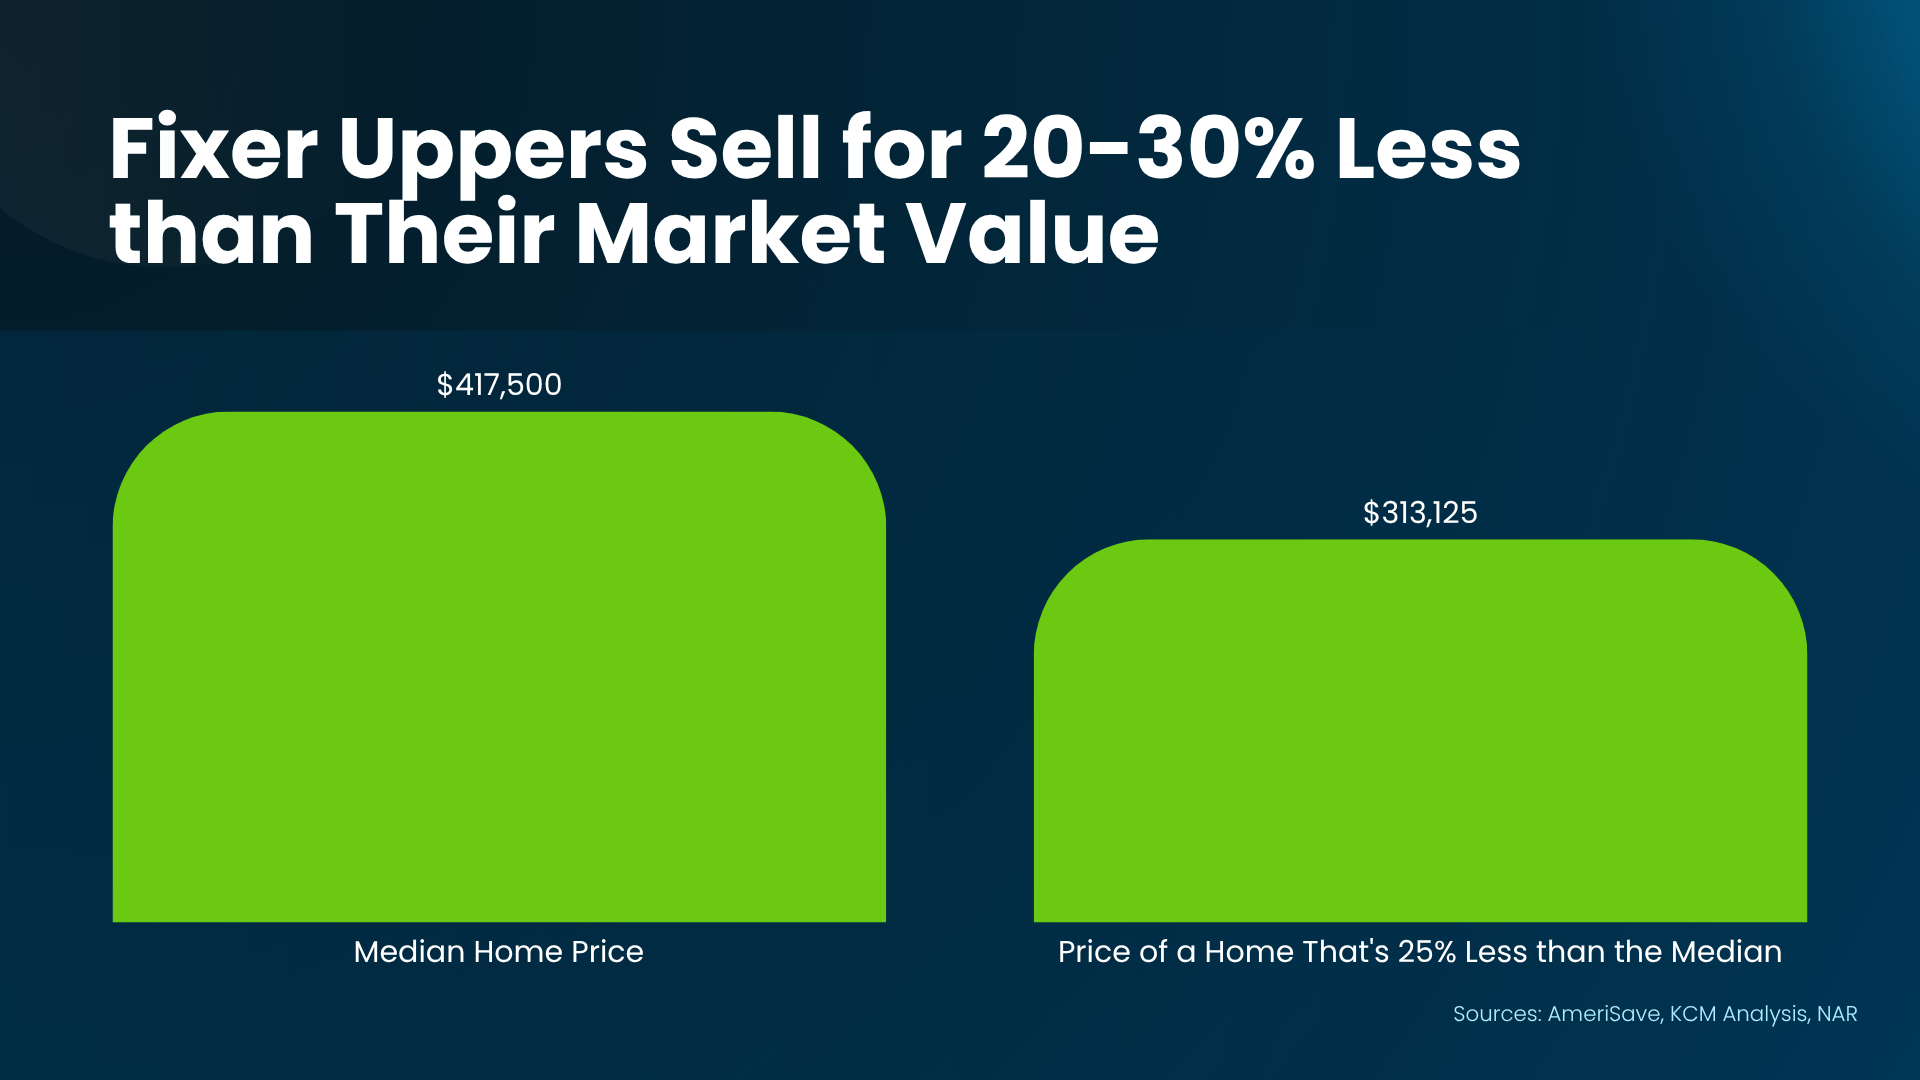
Because these homes need work, they tend to have a lower asking price up front. According to AmeriSave, fixer-uppers usually sell for 20% to 30% less than what they’re worth on the market.

Here’s what that could look like. KCM applied a 25% discount – the middle of that range – to the median home price from the National Association of Realtors (NAR). This is an example, not the average price of a fixer-upper. But it shows the savings could top $100,000 (see graph below):
a green rectangles with white text

That’s a big difference up front and it could be what gets you into a home today. And odds are you don’t have to tackle all the repairs at once – you can space them out over time as it works for you.

Just remember repair costs can add up quickly and eat into those savings if you don’t plan ahead. So, before you make an offer, get estimates from a contractor and set a repair budget you’re comfortable with. There are even some loan types designed to help pay for the work.

One Loan Can Cover the Home and the Repairs

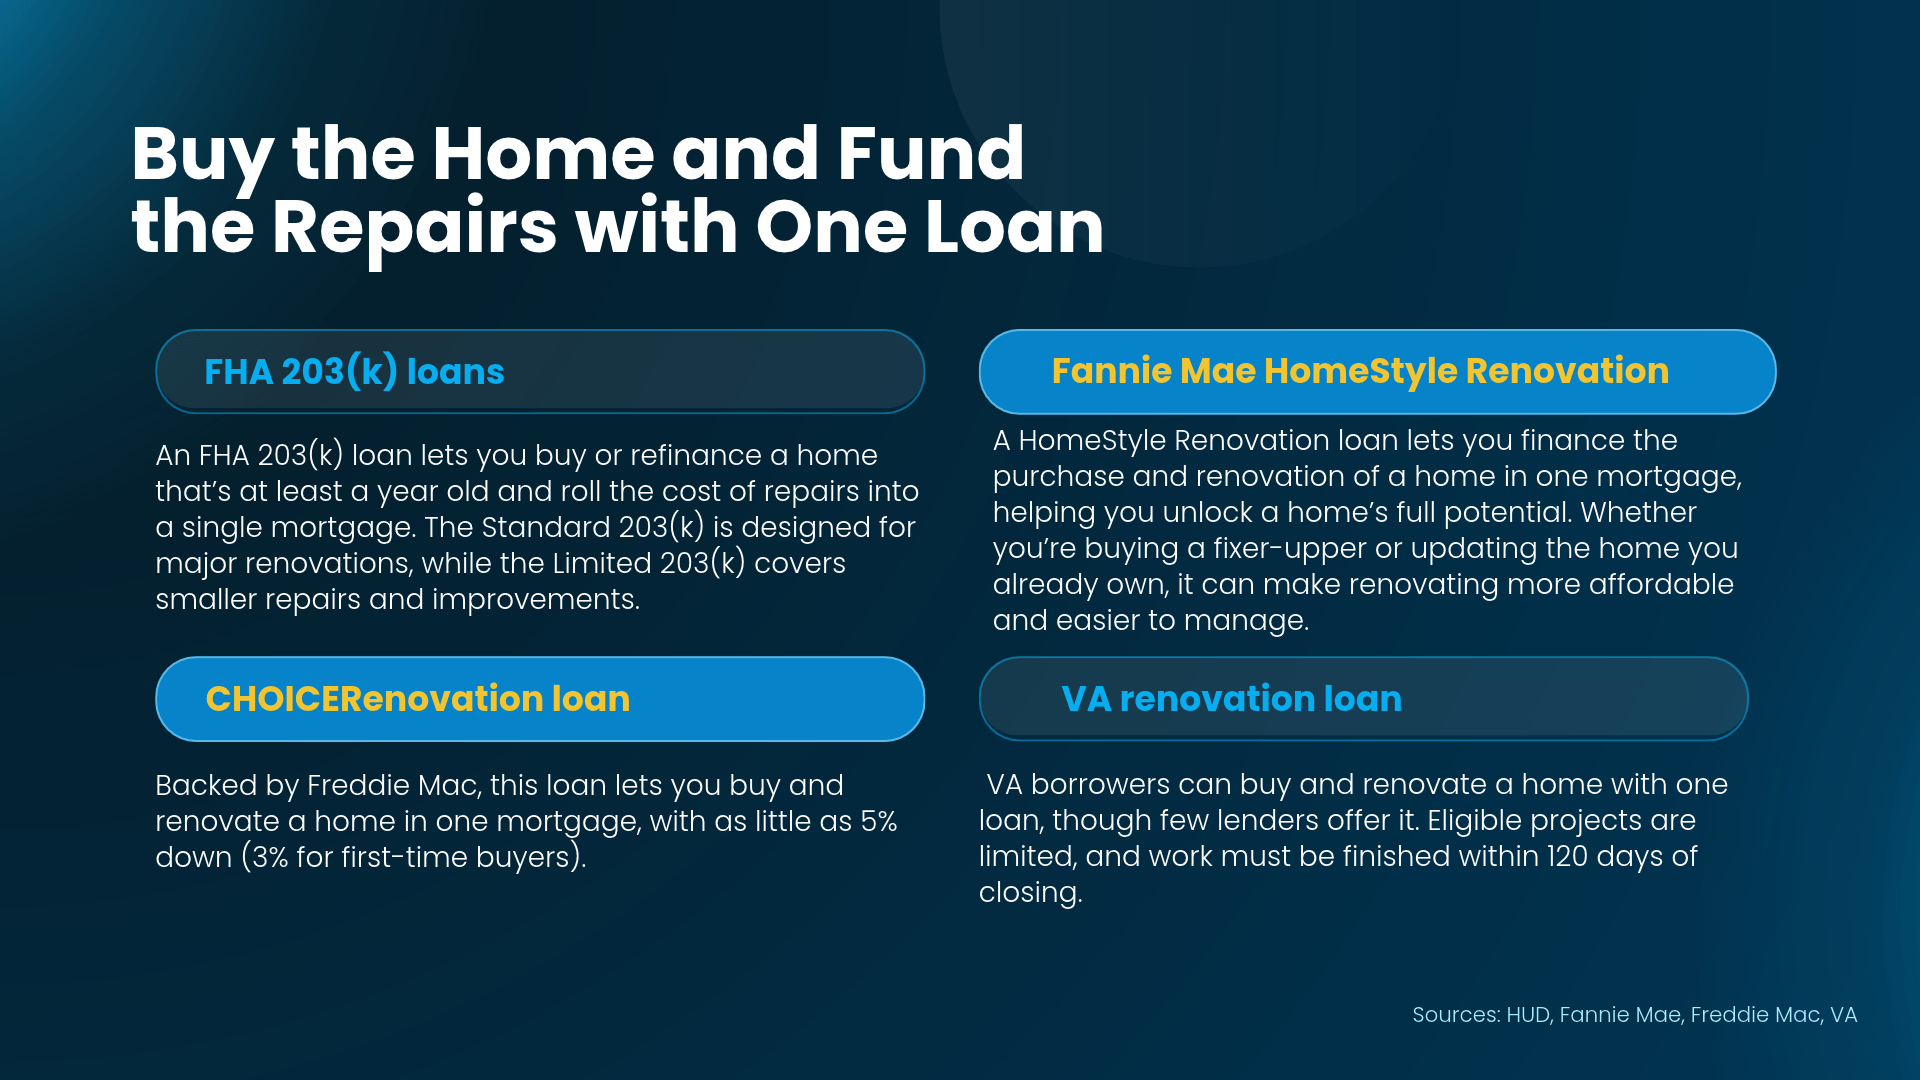
With a renovation loan, you can roll the cost of the work into your mortgage, so you don’t have to cover it all out of pocket once you move in. Here are a few options from FHA, Fannie Mae, Freddie Mac, and the VA (see visual below):
a screenshot of a home loan application

Each program has its own rules, and not every lender offers all of them. So, talk to a trusted lender to see which options are available to you and which make sense for how you plan to tackle updates and repairs over time.

Don’t Overlook Local Perks

Some cities even offer tax breaks to buyers who renovate a fixer-upper and raise its value. These programs vary by location, so check with your city or a tax professional to see what’s available where you want to live.

If you want to check for more information yourself, go to your local county or city official dot-gov website. Then, use the search bar and look for: [City or County Name] AND “home rehabilitation” OR “property tax incentive” OR “housing repair”

A local agent can also help you find fixer-uppers in the neighborhoods you have your heart set on.

Bottom Line

If move-in-ready homes keep coming in over budget, a home that needs some TLC could be your way in. Plan your repair budget and line up the right loan before you buy, and you can get in the door now and make the space your own over time, as your budget allows.

Connect with a local agent to start looking at fixer-uppers in the neighborhoods you love.
What Experts Forecast for Mortgage Rates and Home Prices in 2027

What Experts Forecast for Mortgage Rates and Home Prices in 2027

What Experts Forecast for Mortgage Rates and Home Prices in 2027 Simplifying The Market

When it comes to housing, two of the biggest questions on everyone’s mind right now are:

  1. What’s next for mortgage rates?

  2. Where will home prices go from here?

And if you’re weighing whether to move in the next few months or wait until 2027, here’s what you should know.

When experts look ahead to 2027, they see a steady housing market. No wild swings. No big surprises. Just a calmer, more balanced market.

And steady makes planning a whole lot easier. Let’s break it down.

Rates Are Expected To Settle into a Steady Range

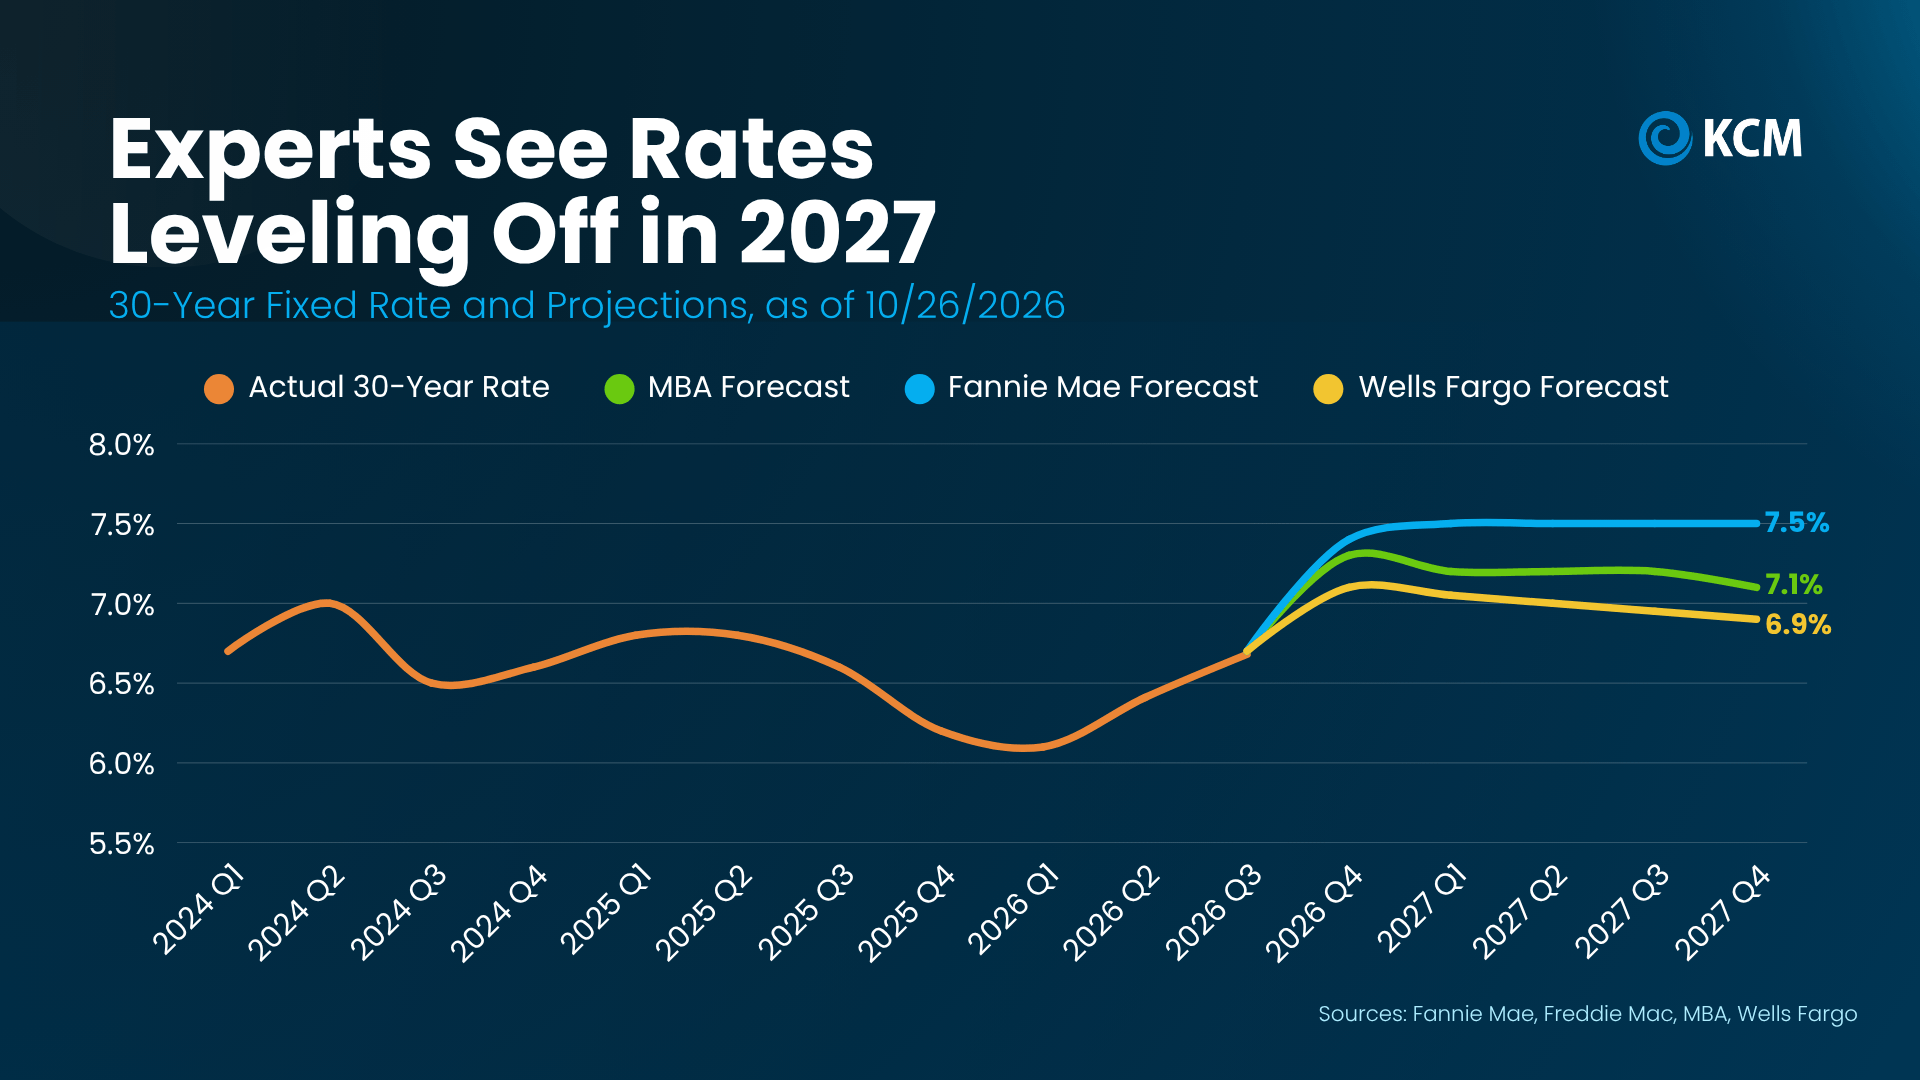
Lots of people are holding out for lower rates. But the latest forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo show rates holding fairly flat through 2027 (see graph below):

a graph of a graph showing the number of the same time

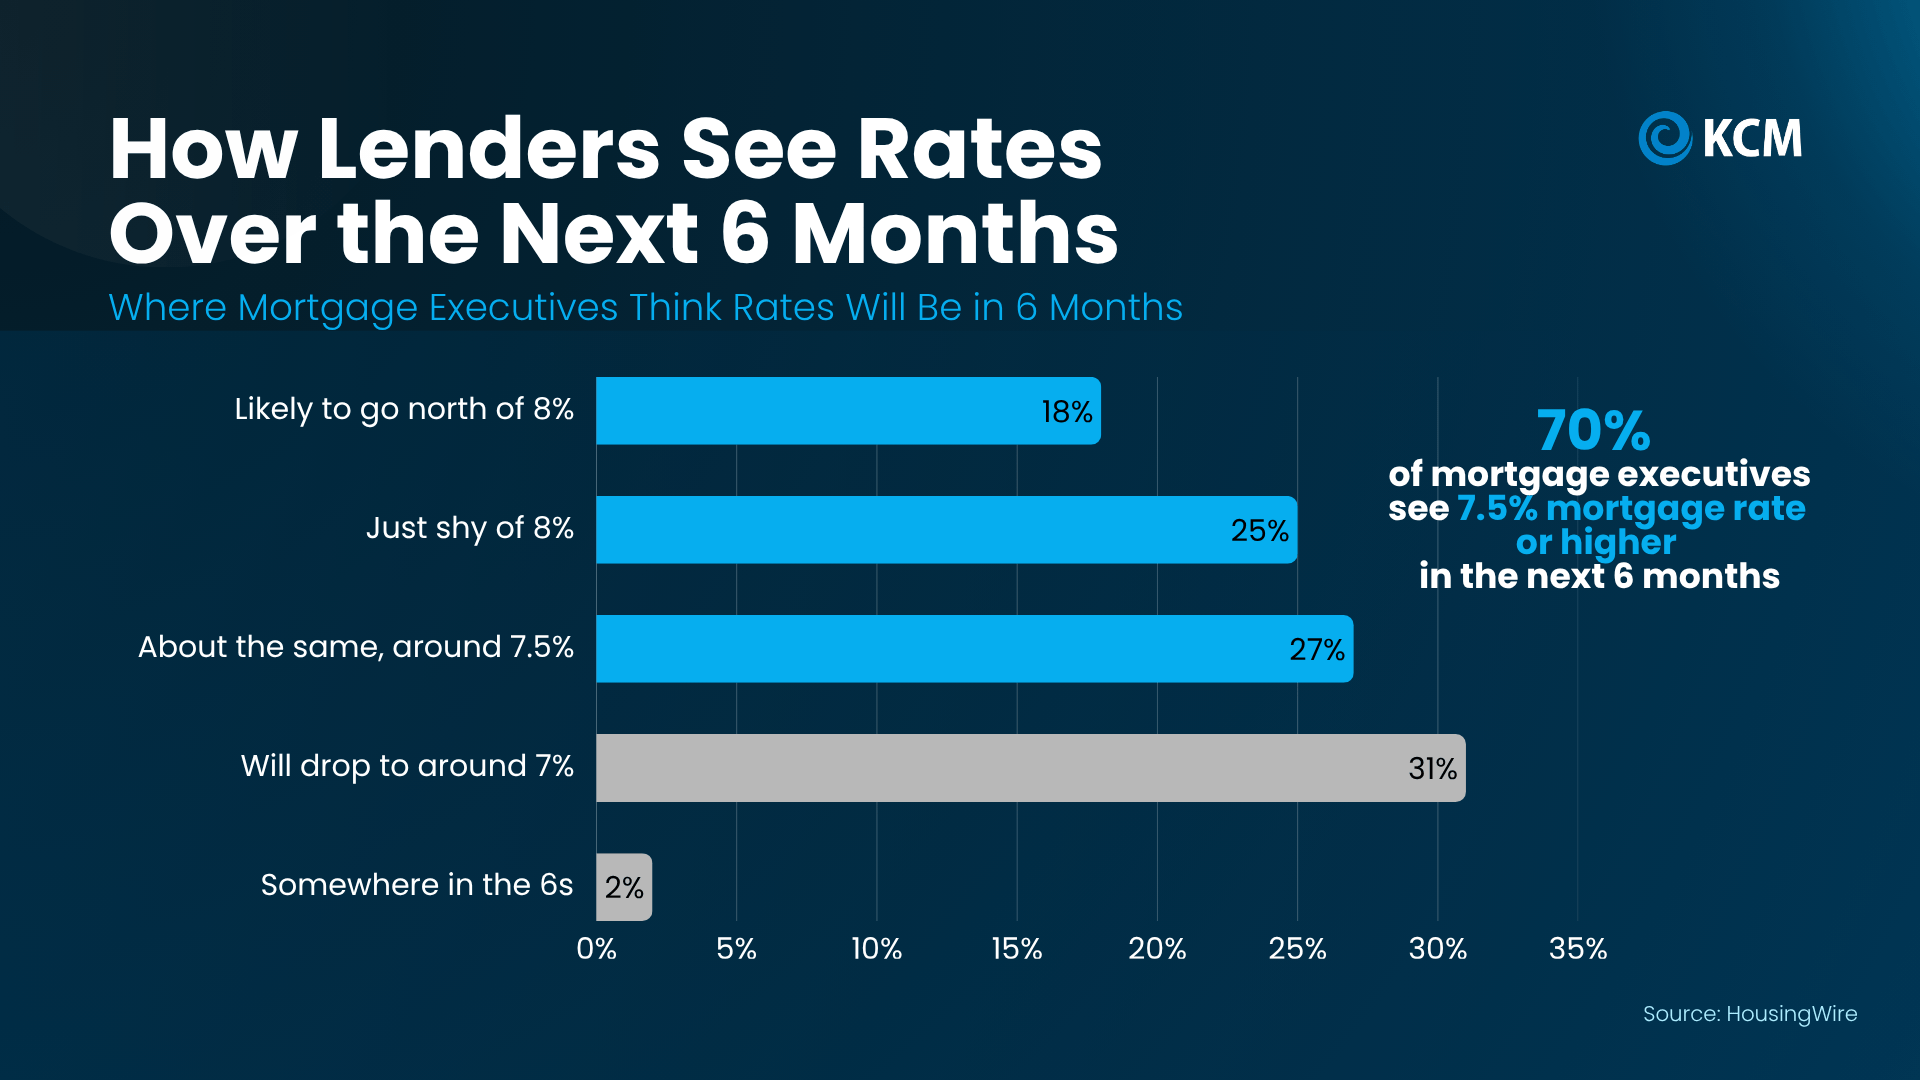
Lenders see it the same way. In a recent survey from HousingWire, 70% of mortgage executives said they expect rates to be around 7.5% or higher six months from now (see graph below):

a graph of percentages and numbers

And if you’re wondering why, the answer is fairly simple. Chen Zhao, Head of Economics Research at Redfin, says:

“Until the underlying economic fundamentals—everything from oil prices to AI–that are keeping rates high change, mortgage rates are unlikely to fall significantly.”

So what does that mean for you? Instead of trying to guess where rates go next, focus on what you can control. Even if rates don’t budge, there are still ways to get the best rate possible. When you talk with your lender, ask about:

  • Your credit score. Even a small bump in your score could help lower your rate.

  • Different loan types. Some programs offer lower rates or smaller down payments than you might expect.

  • Buying down your rate. Paying a little more upfront (called “points”) can lower your rate and your monthly payment.

That way, you’ll know exactly where you stand and what a comfortable monthly payment looks like for you. 

Prices Should Keep Climbing, Just More Slowly

But what about prices? Here’s where steady really works in your favor. 

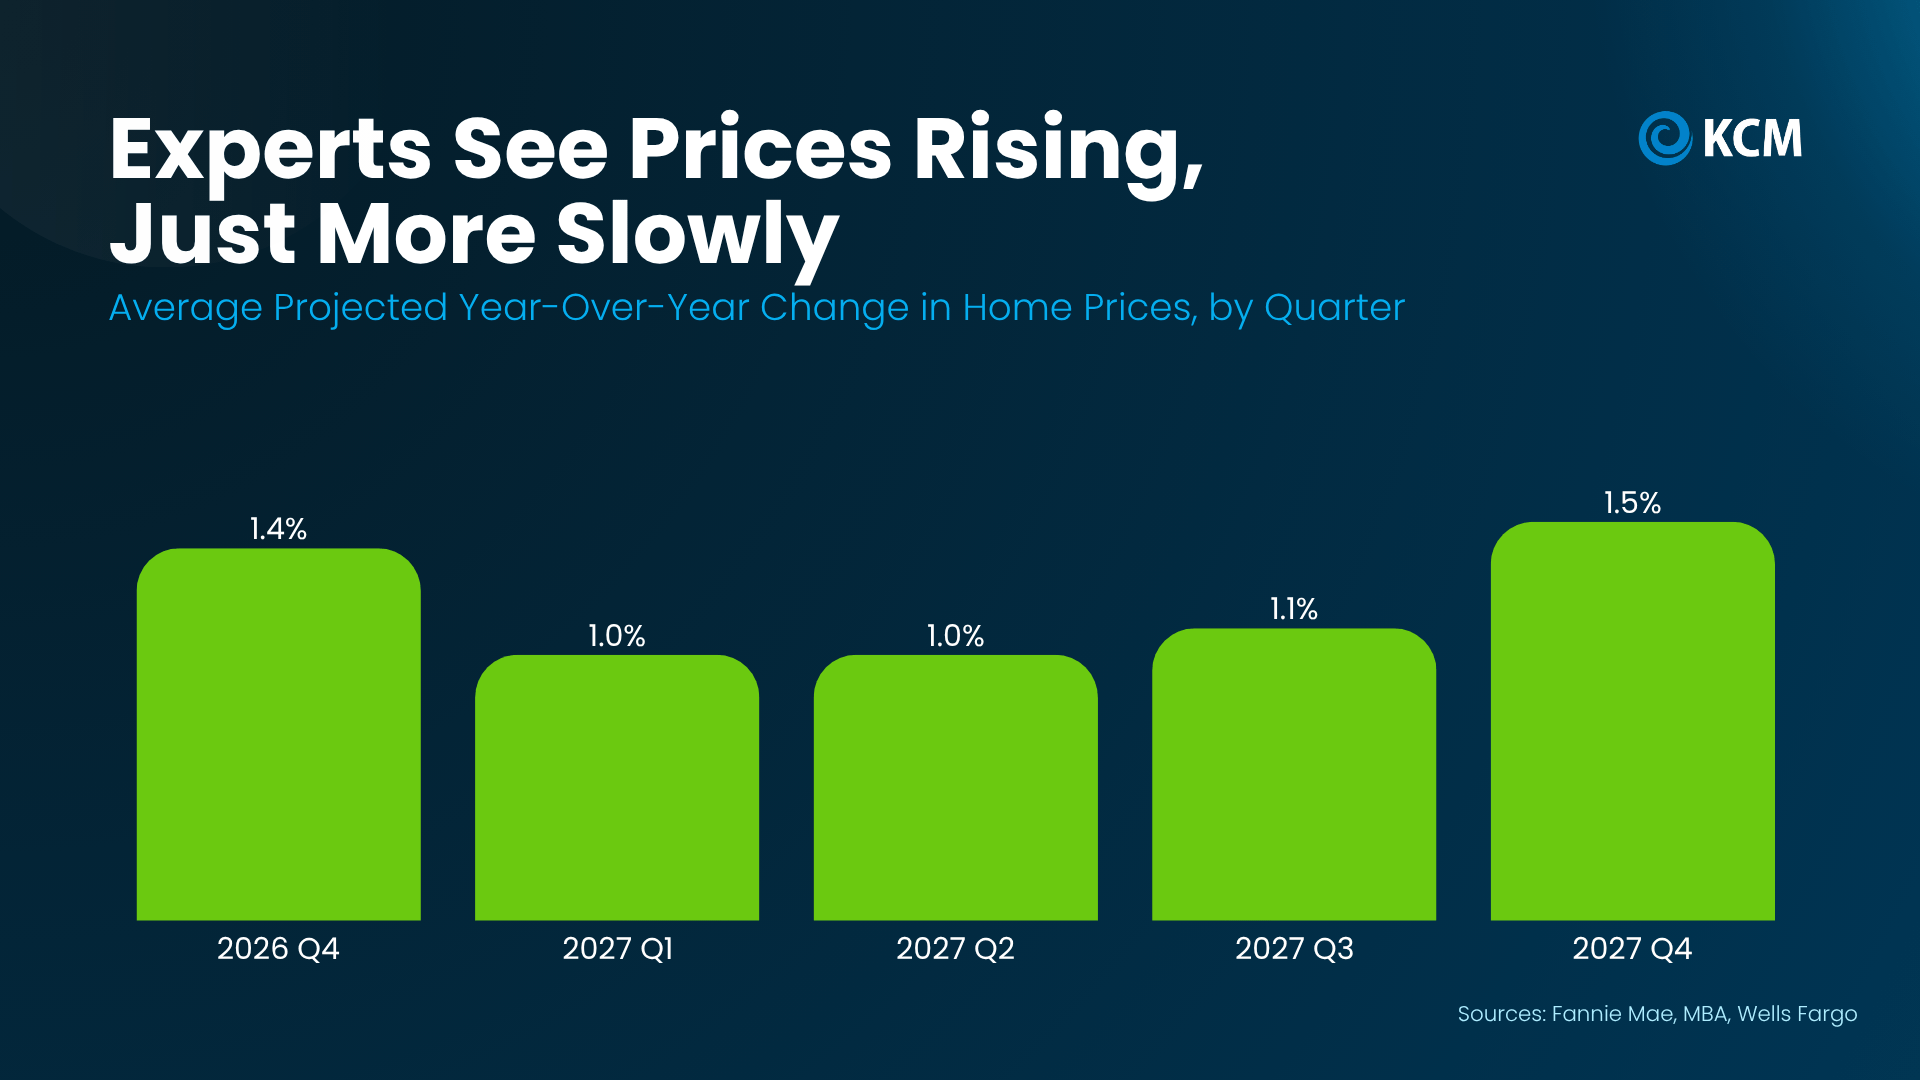
Experts don’t see a home price drop coming. On average, forecasts from Fannie Mae, MBA, and Wells Fargo show prices rising about 1% to 1.5% a year through 2027 (see graph below):

a graph of a number of green squares

In plain terms, in most places prices are still going up, just not as fast. For sellers, that means your home should hold onto its value. For buyers, slower growth gives you a little more breathing room. Just don’t count on prices getting cheaper while you wait.

But keep in mind, these are national forecasts. Prices can look very different from one area to the next, so what matters most is what’s happening where you live.

The Best Time To Move Is When It Fits Your Life

When the market is steady, you don’t have to try to time it perfectly. There’s no big swing to wait out.

That puts the focus back on you. Maybe you need more space for a growing family. Maybe you’re ready for less upkeep. A steady market makes it easier to plan for either one.

Bottom Line

If you’re asking yourself should you move now or wait? You should know experts see a steady market through 2027, with rates holding near today’s levels and prices rising slowly. 

So, rather than waiting for a big shift that may not come, connect with a local real estate agent and run the numbers on what a move looks like at today’s rates and prices, so you can decide based on your goals instead of the headlines.

Confused by Home Price Headlines? Here’s Why.

Confused by Home Price Headlines? Here’s Why.

Confused by Home Price Headlines? Here’s Why. Simplifying The Market

Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.

One says home prices are falling. The next says they’re still climbing.

So, which one’s right? It comes down to where you live.

What’s Really Going on with Asking Prices

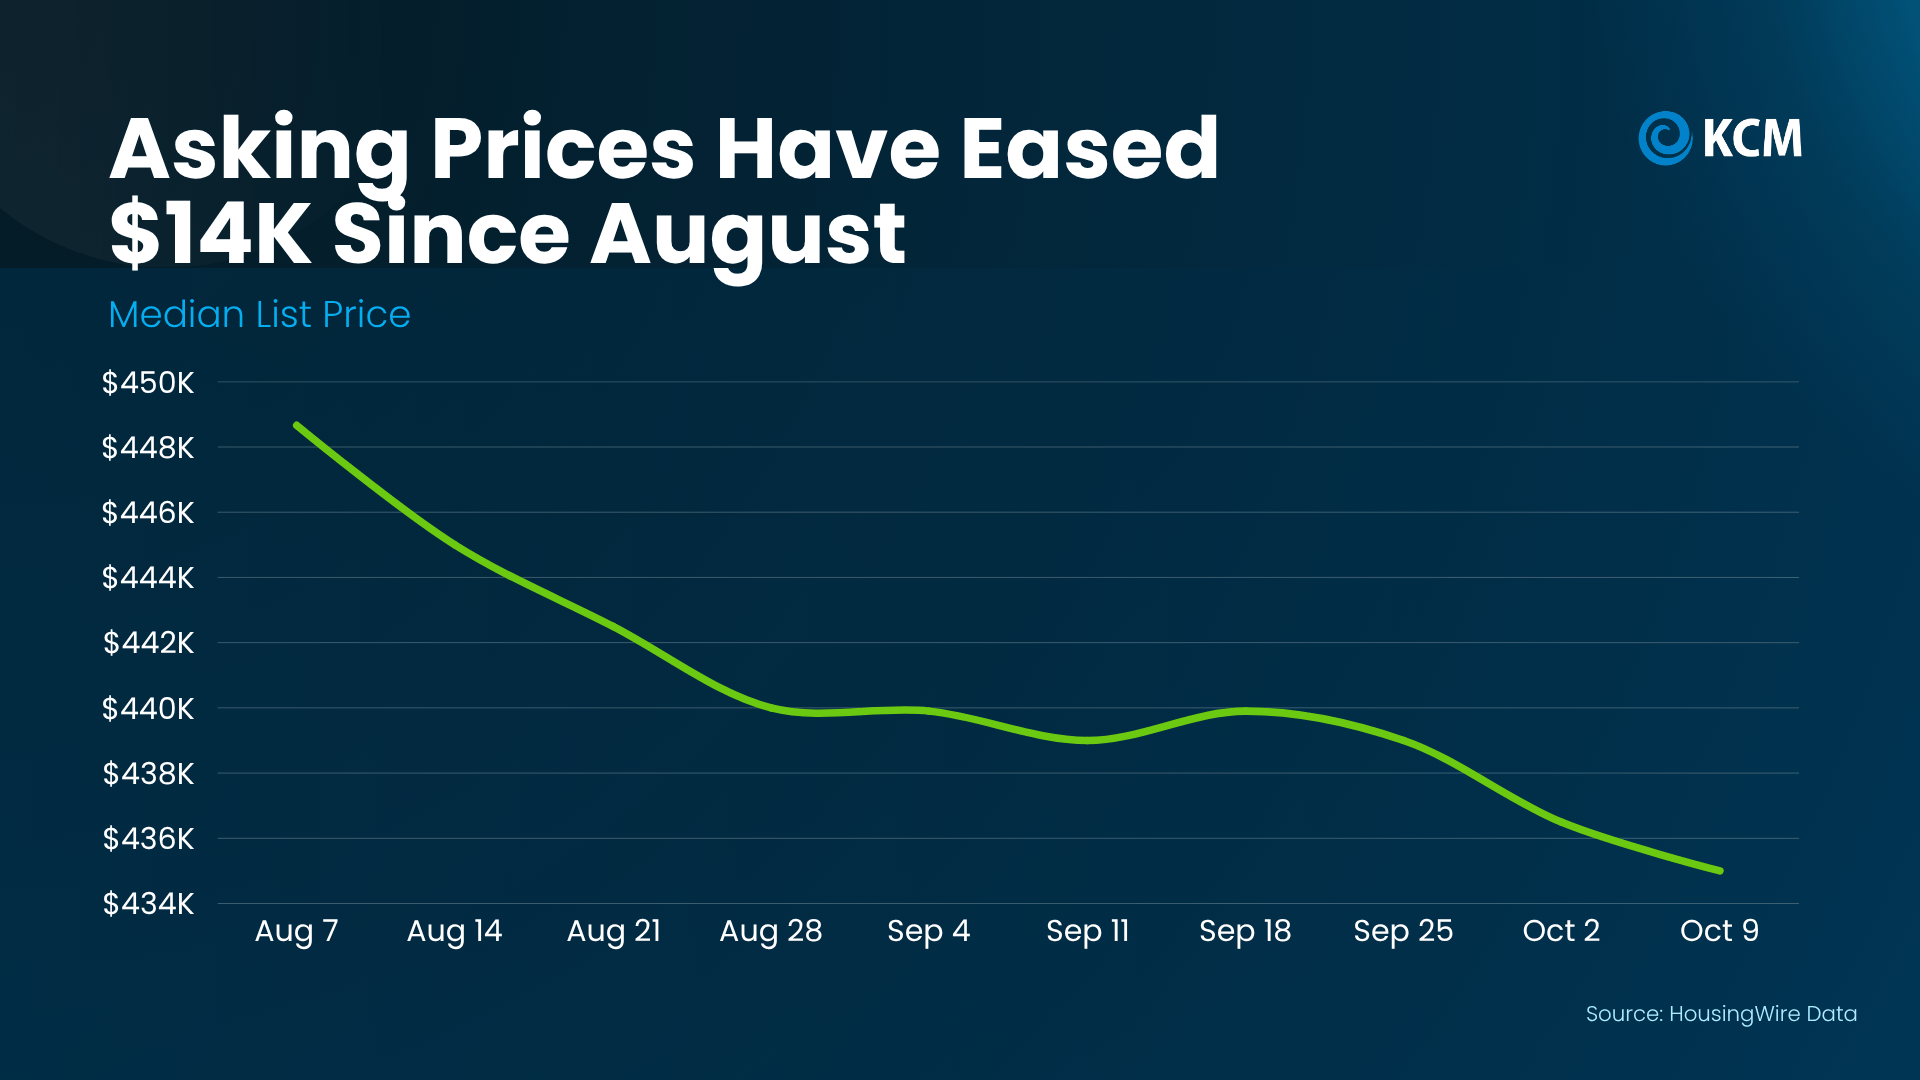
Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.

Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.

According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):

a graph with green line

That’s a dip of about 3%, and a lot of it is normal for this time of year.

Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.

Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.

Where You Live Changes Everything

Realtor.com explains:

“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”

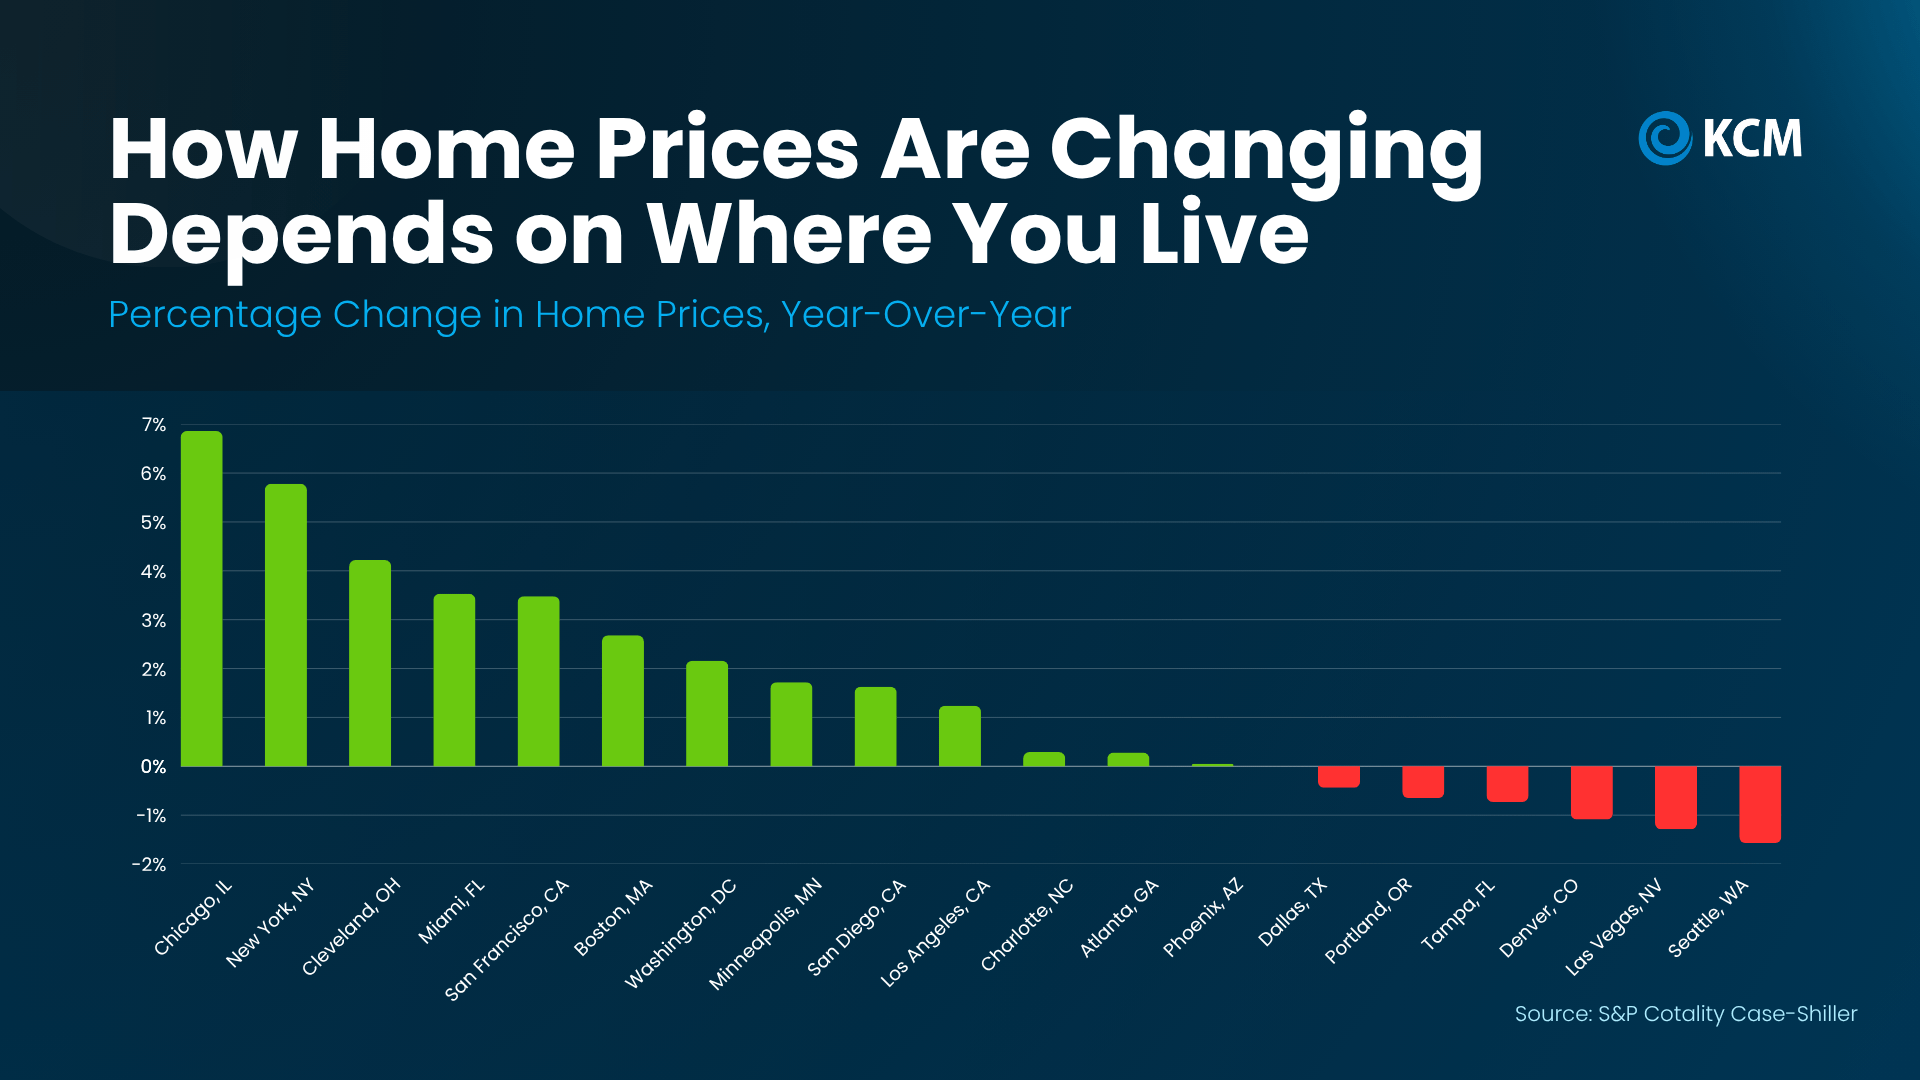
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):

a graph of a price

That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.

Why You Don’t Need To Worry About a Crash

Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.

And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):

a graph with a line going up

So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.

Bottom Line

National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, connect with a local real estate agent to look at how prices are moving in your area, so you can set your price or make your offer with confidence.

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home Simplifying The Market

With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. 

Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…

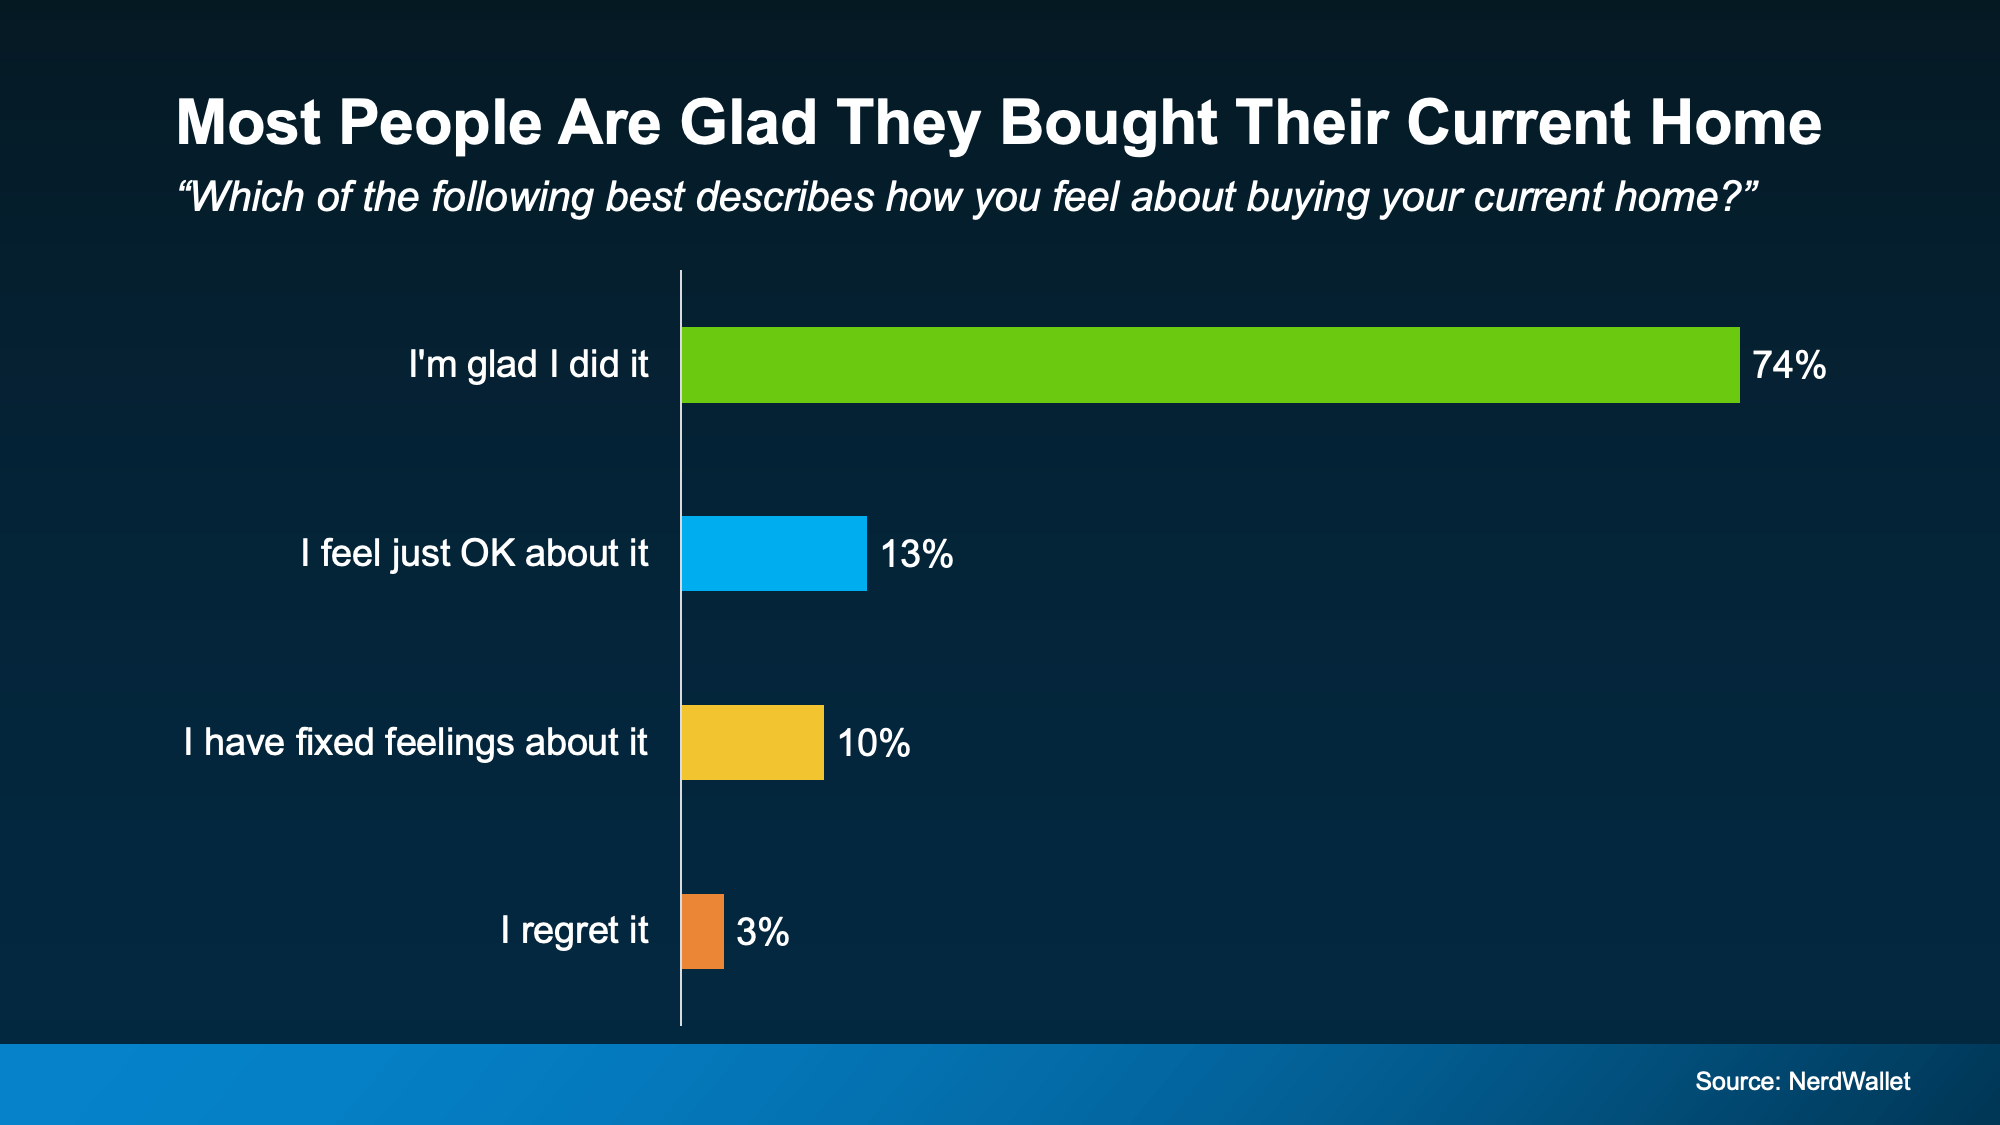
Most people who already made that leap would do it again.

According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:

a graph with text on it

And here’s a big reason why so many people feel it was worth it, even now.

Homeownership Is a Long-Term Play

When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.

A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.

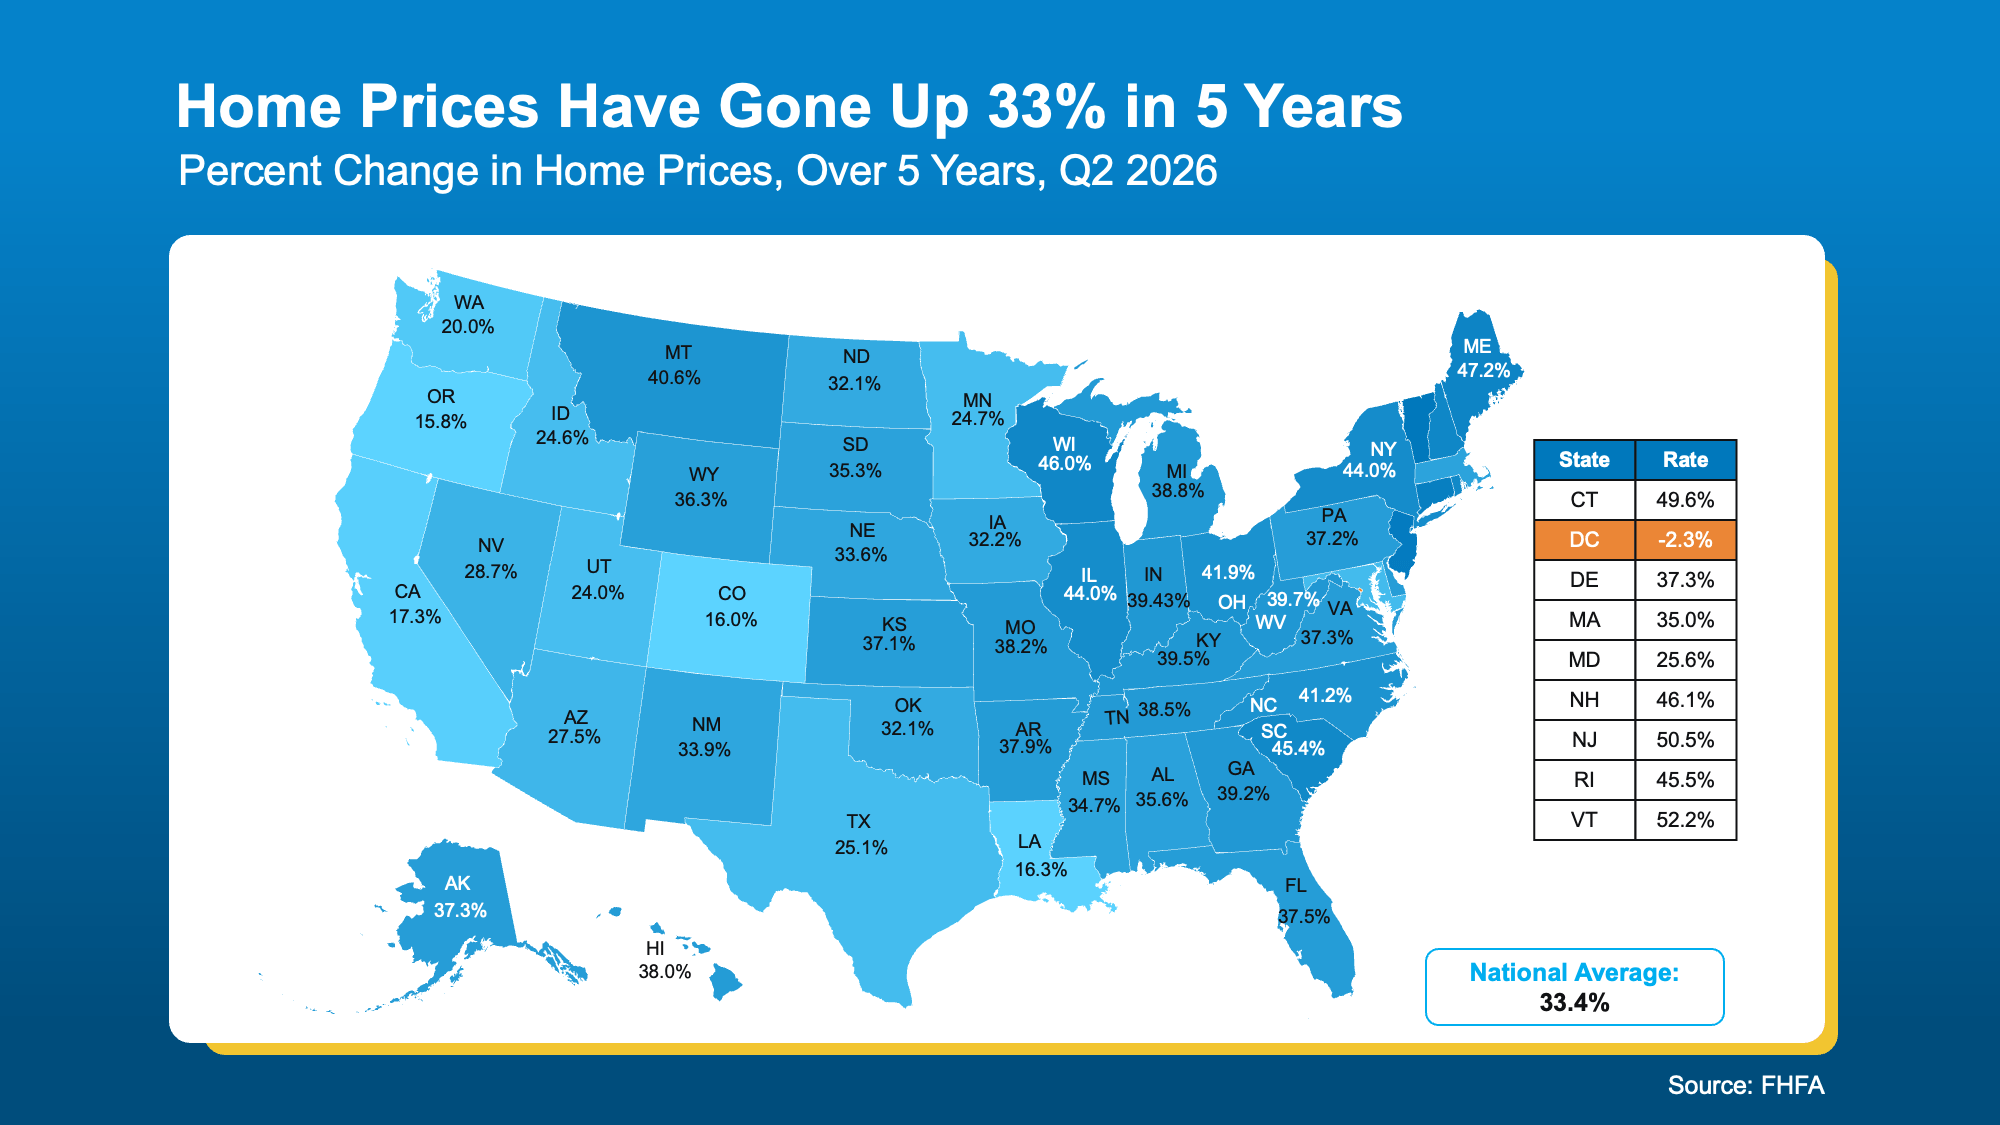
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):

a map of the united states

And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.

That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.

Now, Zoom Out Even Further

The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.

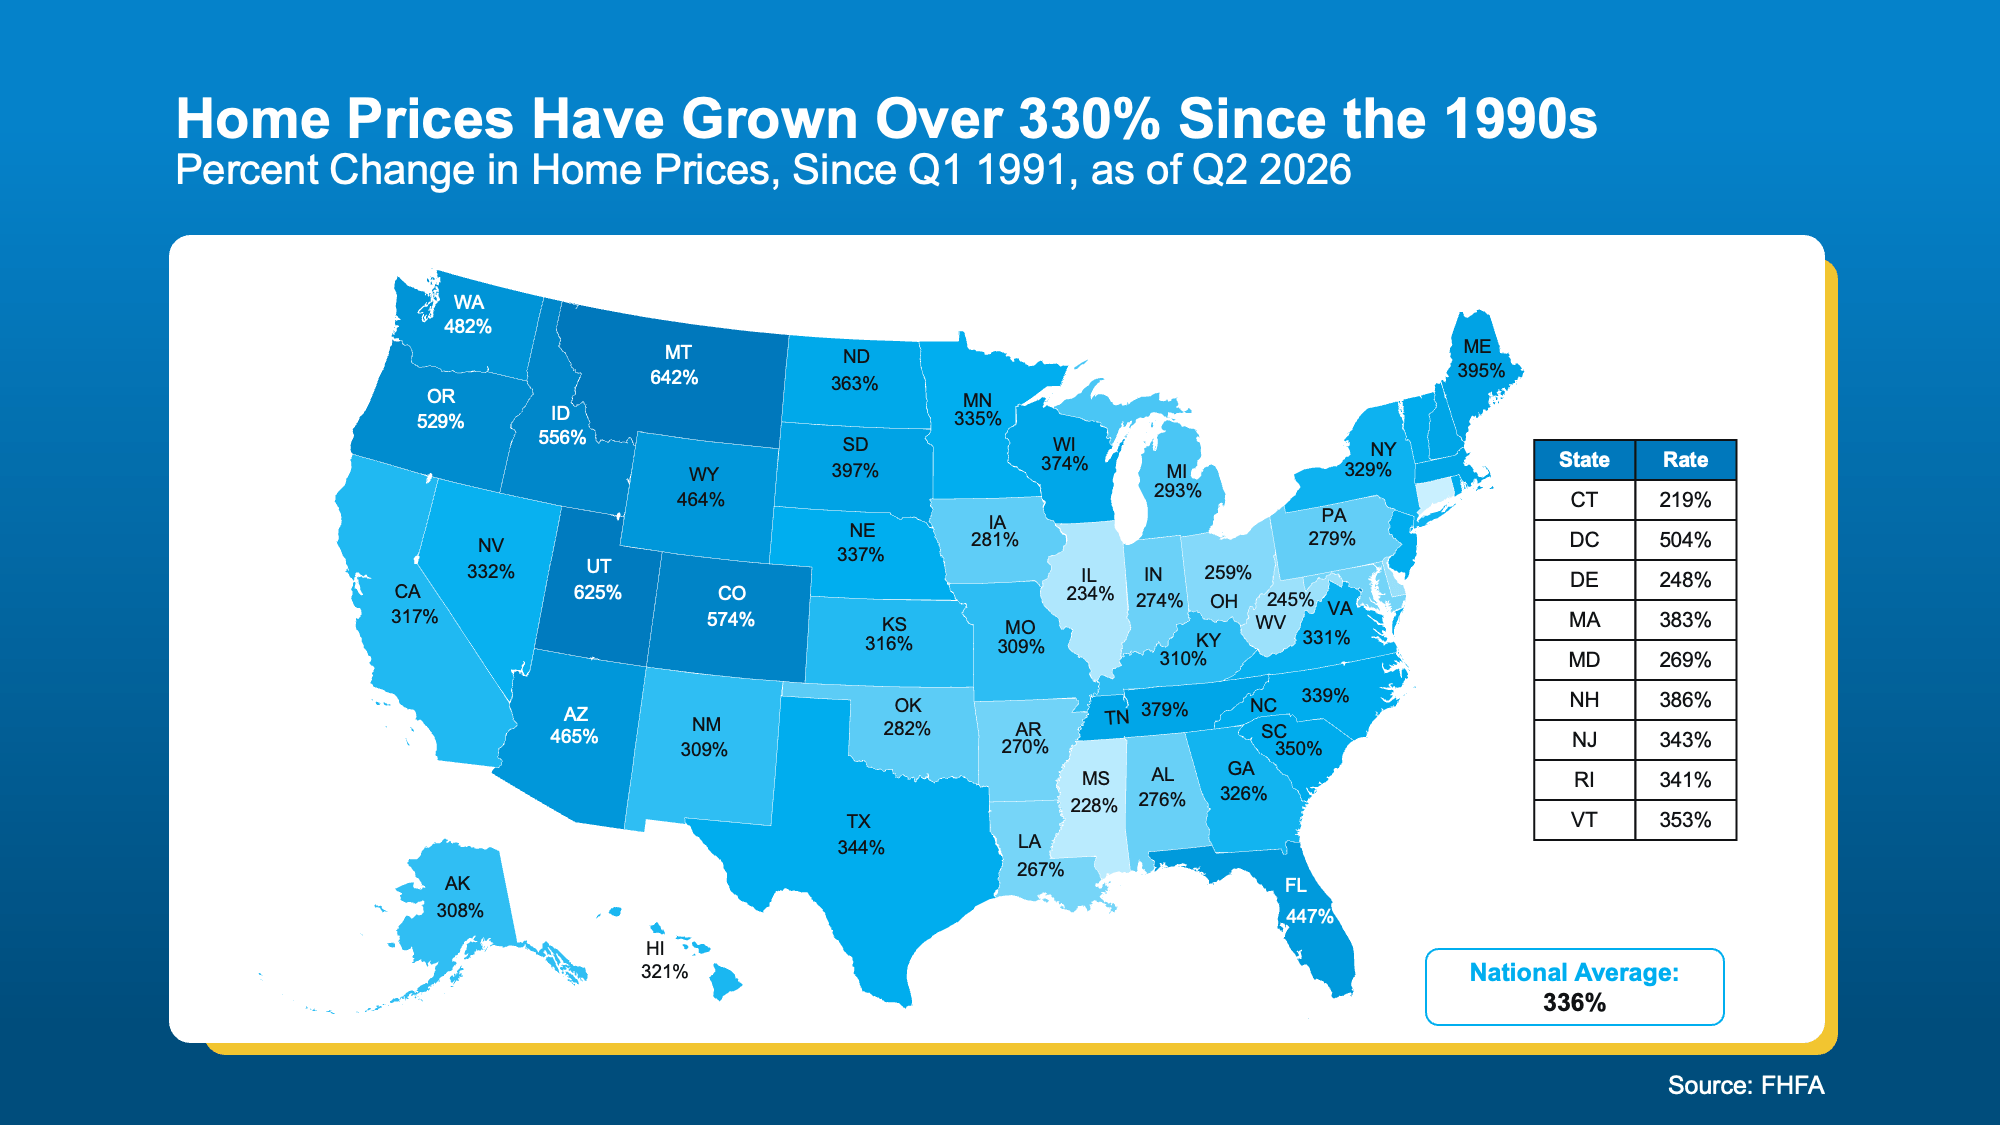
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):

a map of the united states with numbers and a number of states 

That doesn’t mean prices go up every single year. And it doesn’t mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.

What it does show is why trying to perfectly time the market can make you miss the bigger picture. 

Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains: 

“Your home’s equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .

If it’s time to upsize or downsize, you can use that cash for the down payment on your next home.”

Basically, if you can afford to do it, buying a home now could set you up for future moves.

And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.

Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.

Bottom Line

Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.

If you’re wondering whether buying makes sense for you right now, connect with an agent to look at the numbers together – and what owning a home could mean for you in the years ahead.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In. Simplifying The Market

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.

So, what do the forecasts actually say?

Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.

What the Newest Numbers Actually Say

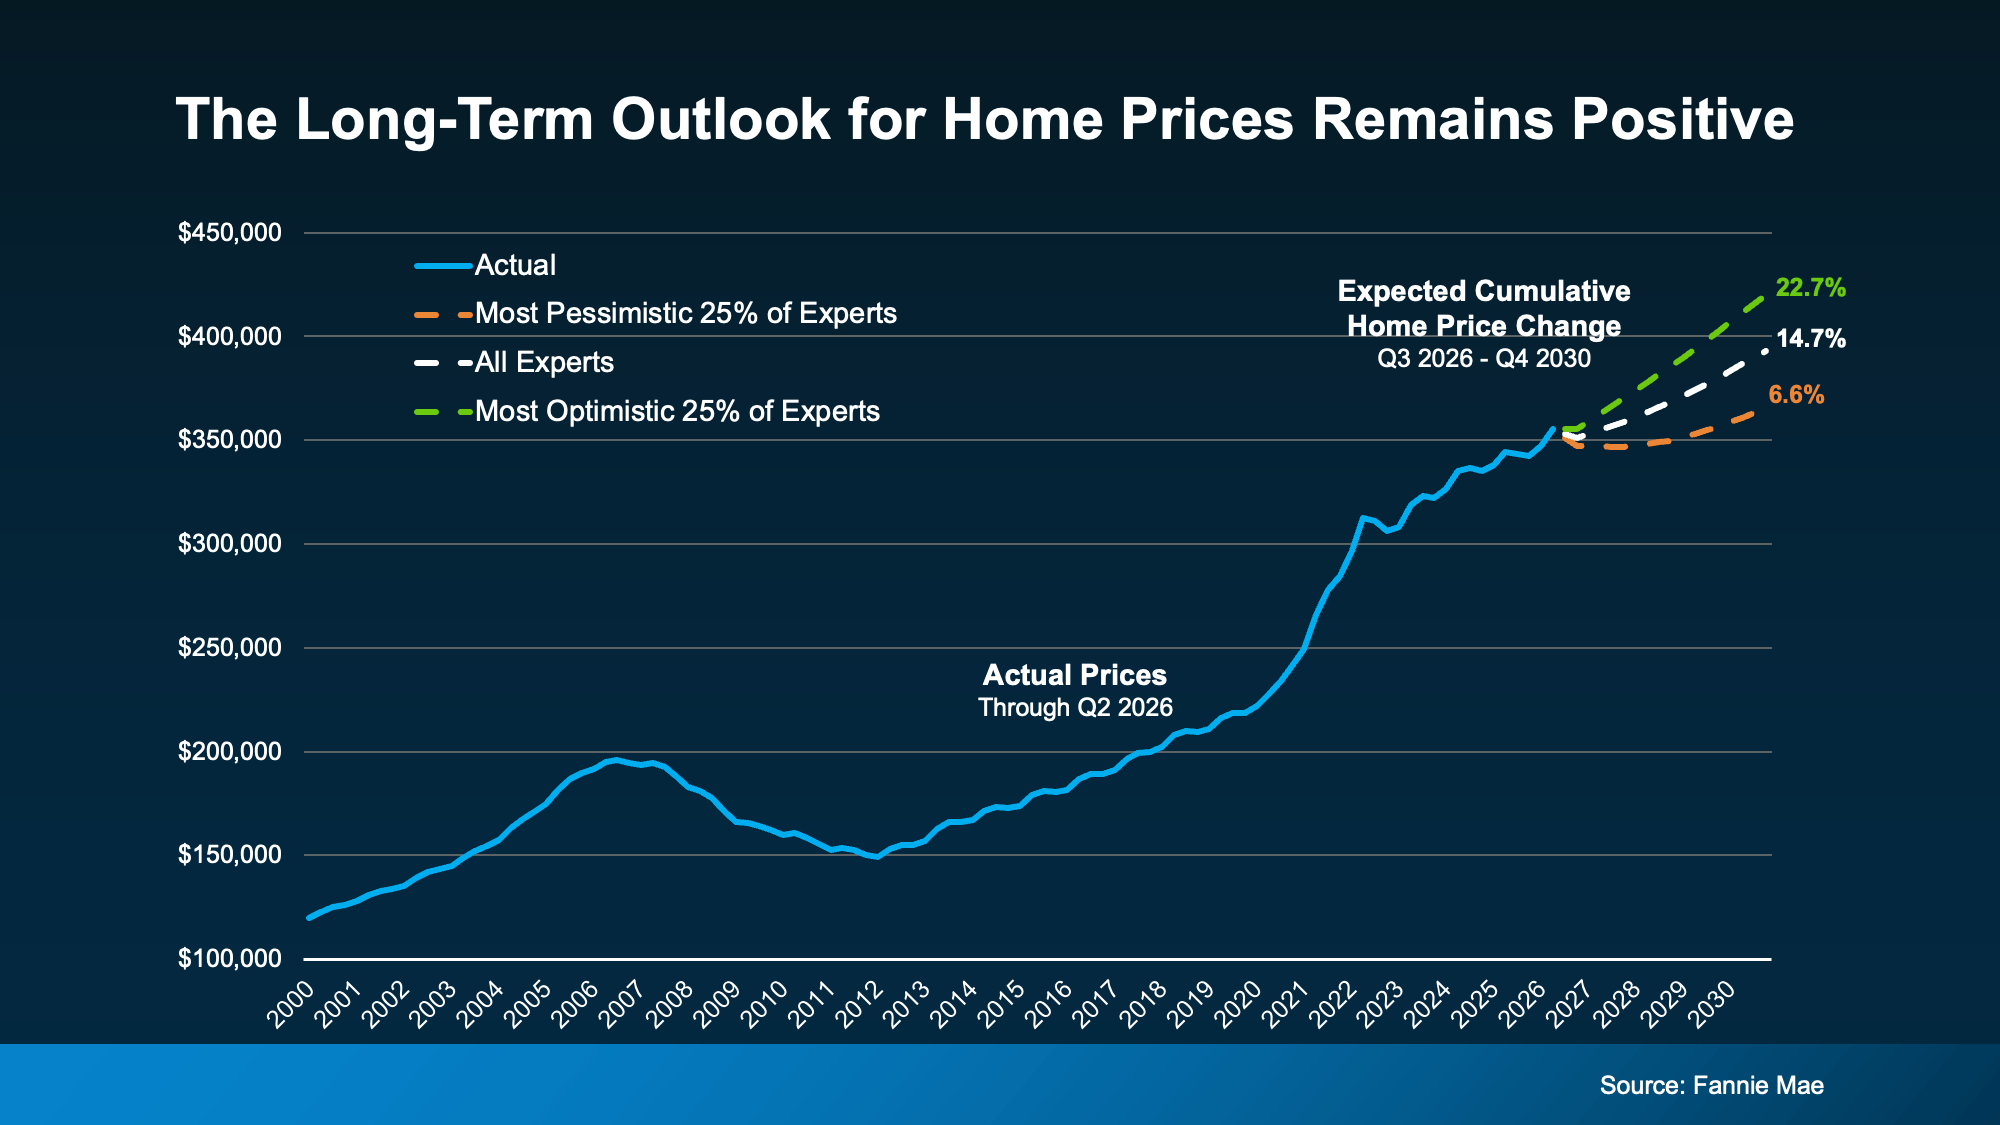
The panel’s latest forecast has prices climbing every single year through at least 2030.

The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):

a graph showing the price of a home

The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.

One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.

How This Quarter Compares to the Past

Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.

A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):

a graph of growth in a graph

Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.

But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.

A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.

A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.

What It Means for Your Next Move

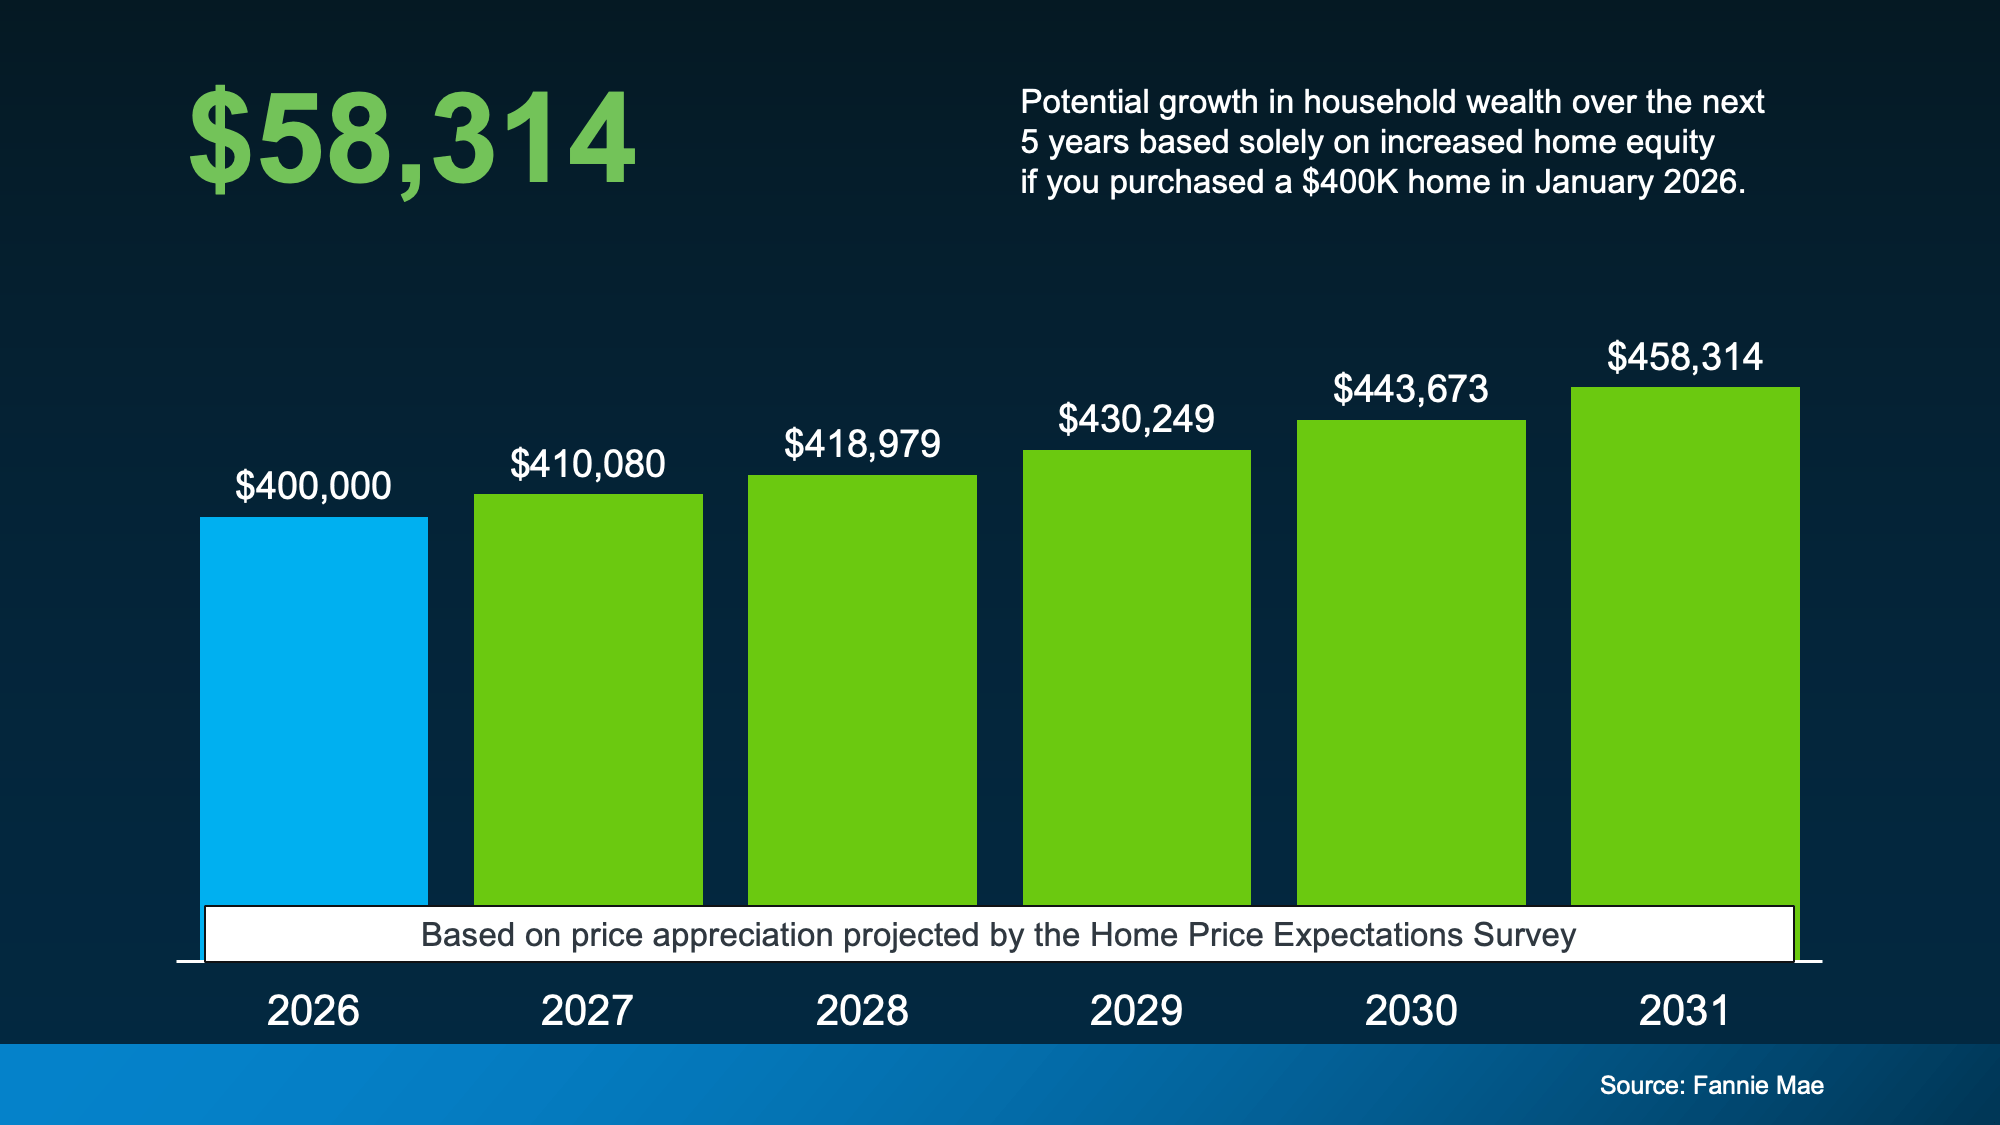
Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.

Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):

a graph of growth in a number of green squares

That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.

Bottom Line

Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

Why So Many Sellers Are Cutting Their Price Right Now

Why So Many Sellers Are Cutting Their Price Right Now

Why So Many Sellers Are Cutting Their Price Right Now Simplifying The Market

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.

Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.

This is what’s actually driving all those price cuts, and why it matters no matter which side of the deal you’re on.

42% of Homes for Sale Are Now Carrying a Price Cut

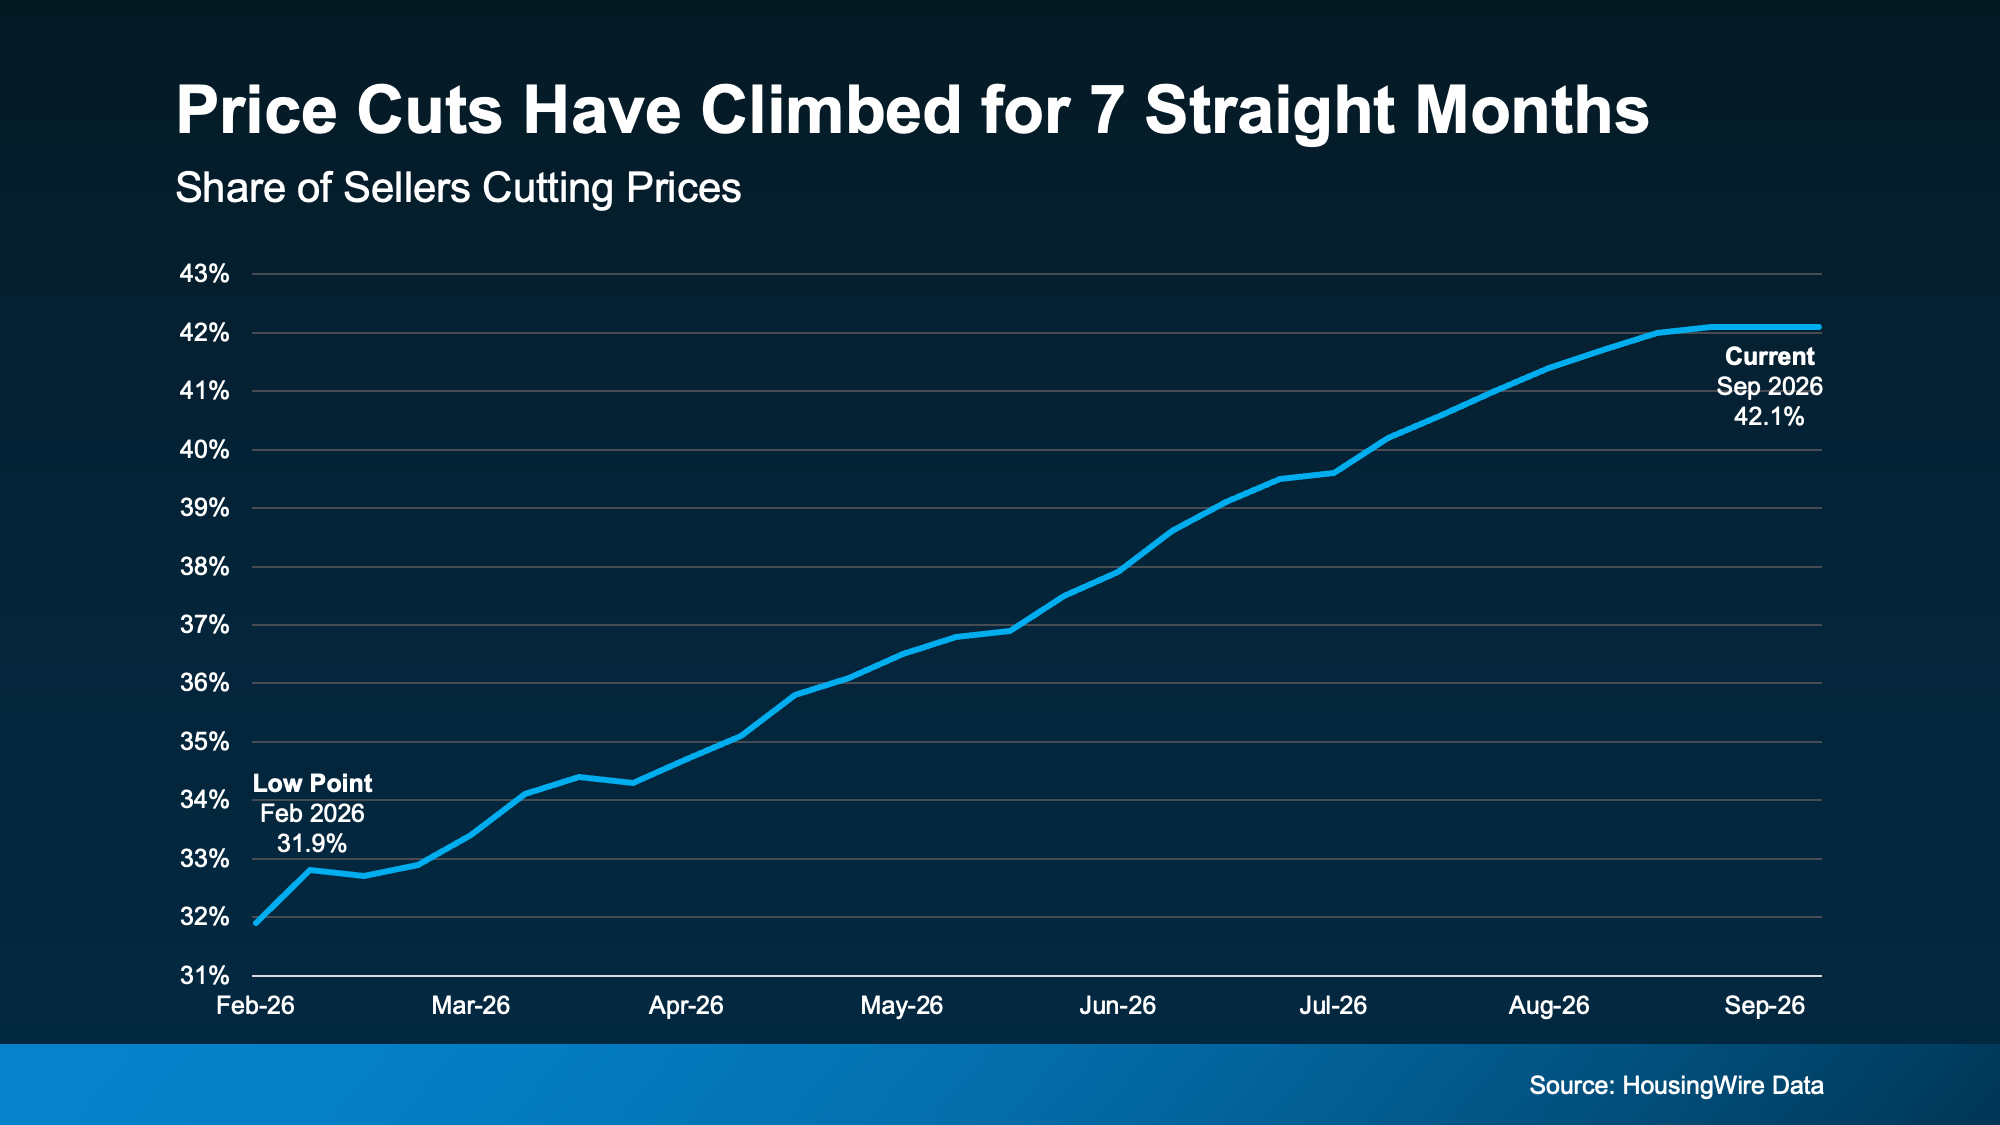
According to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):

a graph showing the growth of a straight month 

Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. 

Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.

What does that mean for you?

  • If you’re selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market’s been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.

  • If you’re buying, it’s easy to assume a price cut means something’s wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that’s exactly the kind of opening you need to get a better deal.

Why Sellers Are Adjusting Faster than Before

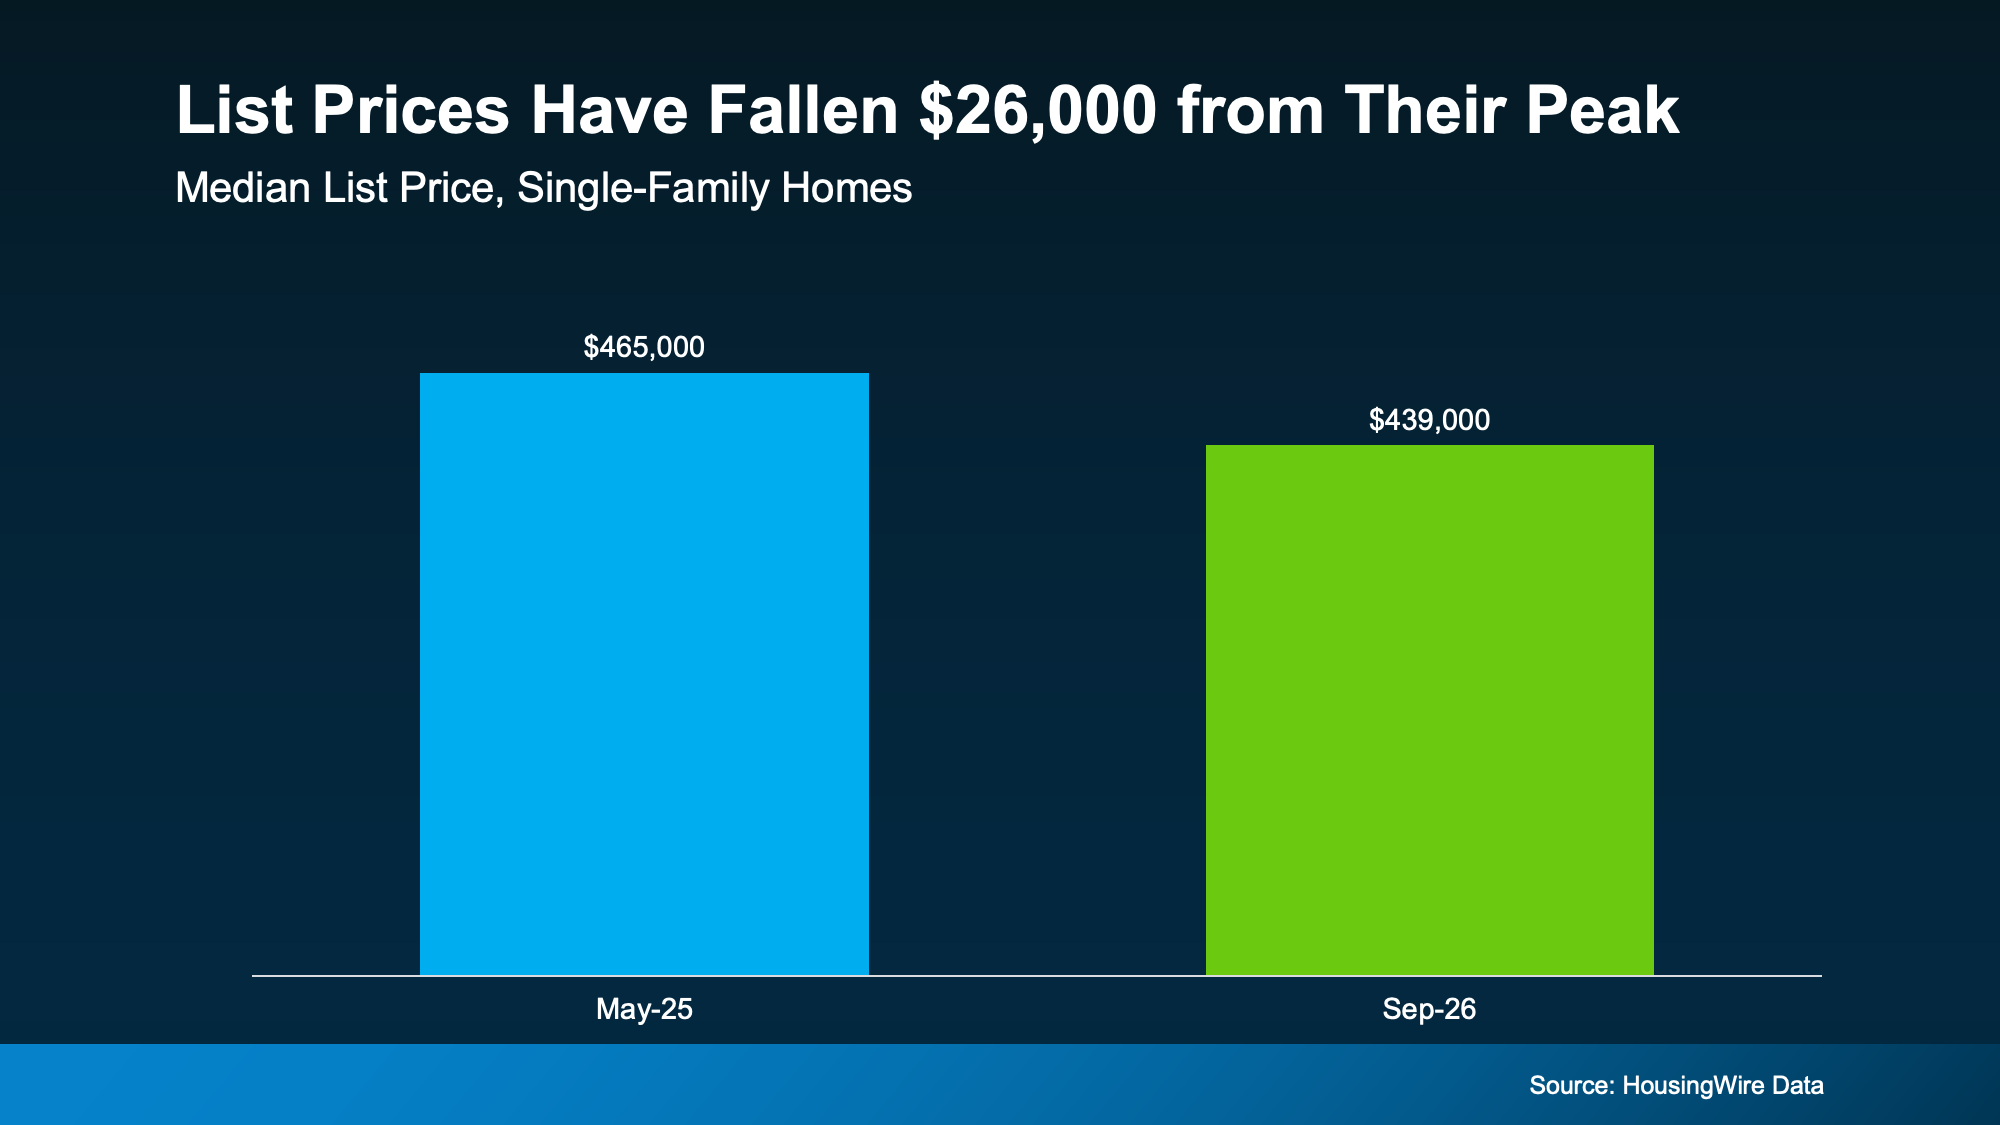
HousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year’s peak.

Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below):

a graph of a number of people 

Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.

Buyers, You’ve Got Room To Negotiate Again

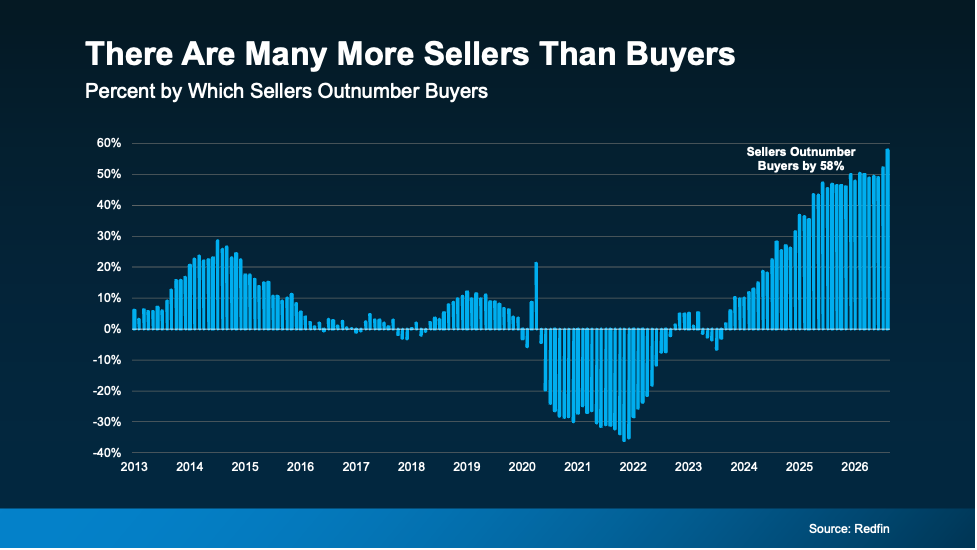
At the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below):

a graph of sales 

That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.

  • For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.

  • For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.

Bottom Line

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Connect with a local real estate agent to look at what’s actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

Pin It on Pinterest