Myth vs. Reality: Does the Fed Control Mortgage Rates?

Myth vs. Reality: Does the Fed Control Mortgage Rates?
Myth vs. Reality: Does the Fed Control Mortgage Rates? Simplifying The Market

You’ve probably heard the Federal Reserve (the Fed) is raising rates again. And if you’re planning to buy or sell a house, you may be wondering what that means for you.

With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.

So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.

Why the Fed Is Raising Rates

It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.

So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.

  • MYTH: The Fed controls mortgage rates.

  • REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.

As NerdWallet explains:

“The Federal Reserve influences mortgage rates, but doesn’t set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve’s monetary policy is a factor, too . . .”

Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.

Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.

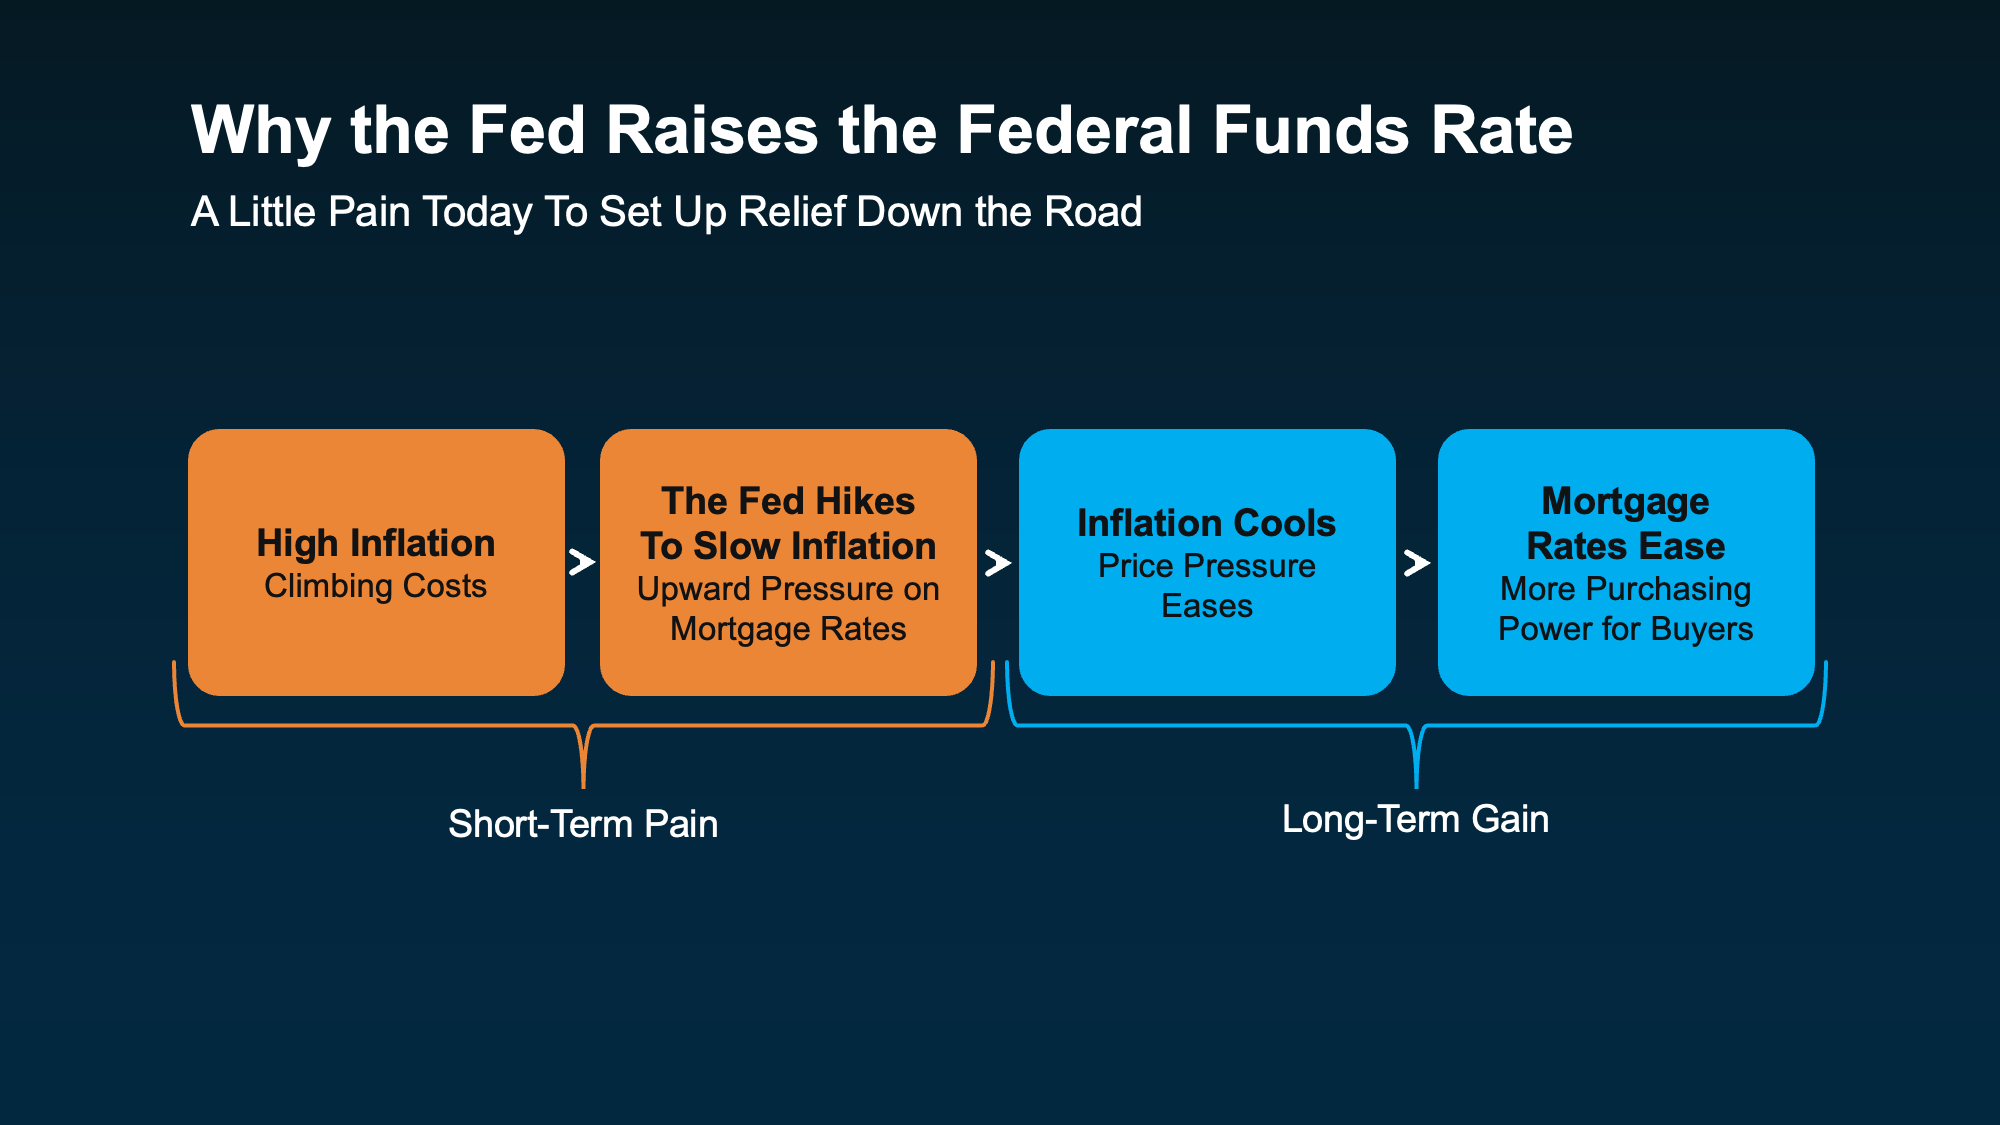
What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):
a diagram of a federal funds rate

Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.

There’s a Strong Possibility the Fed Will Hike Again This Year

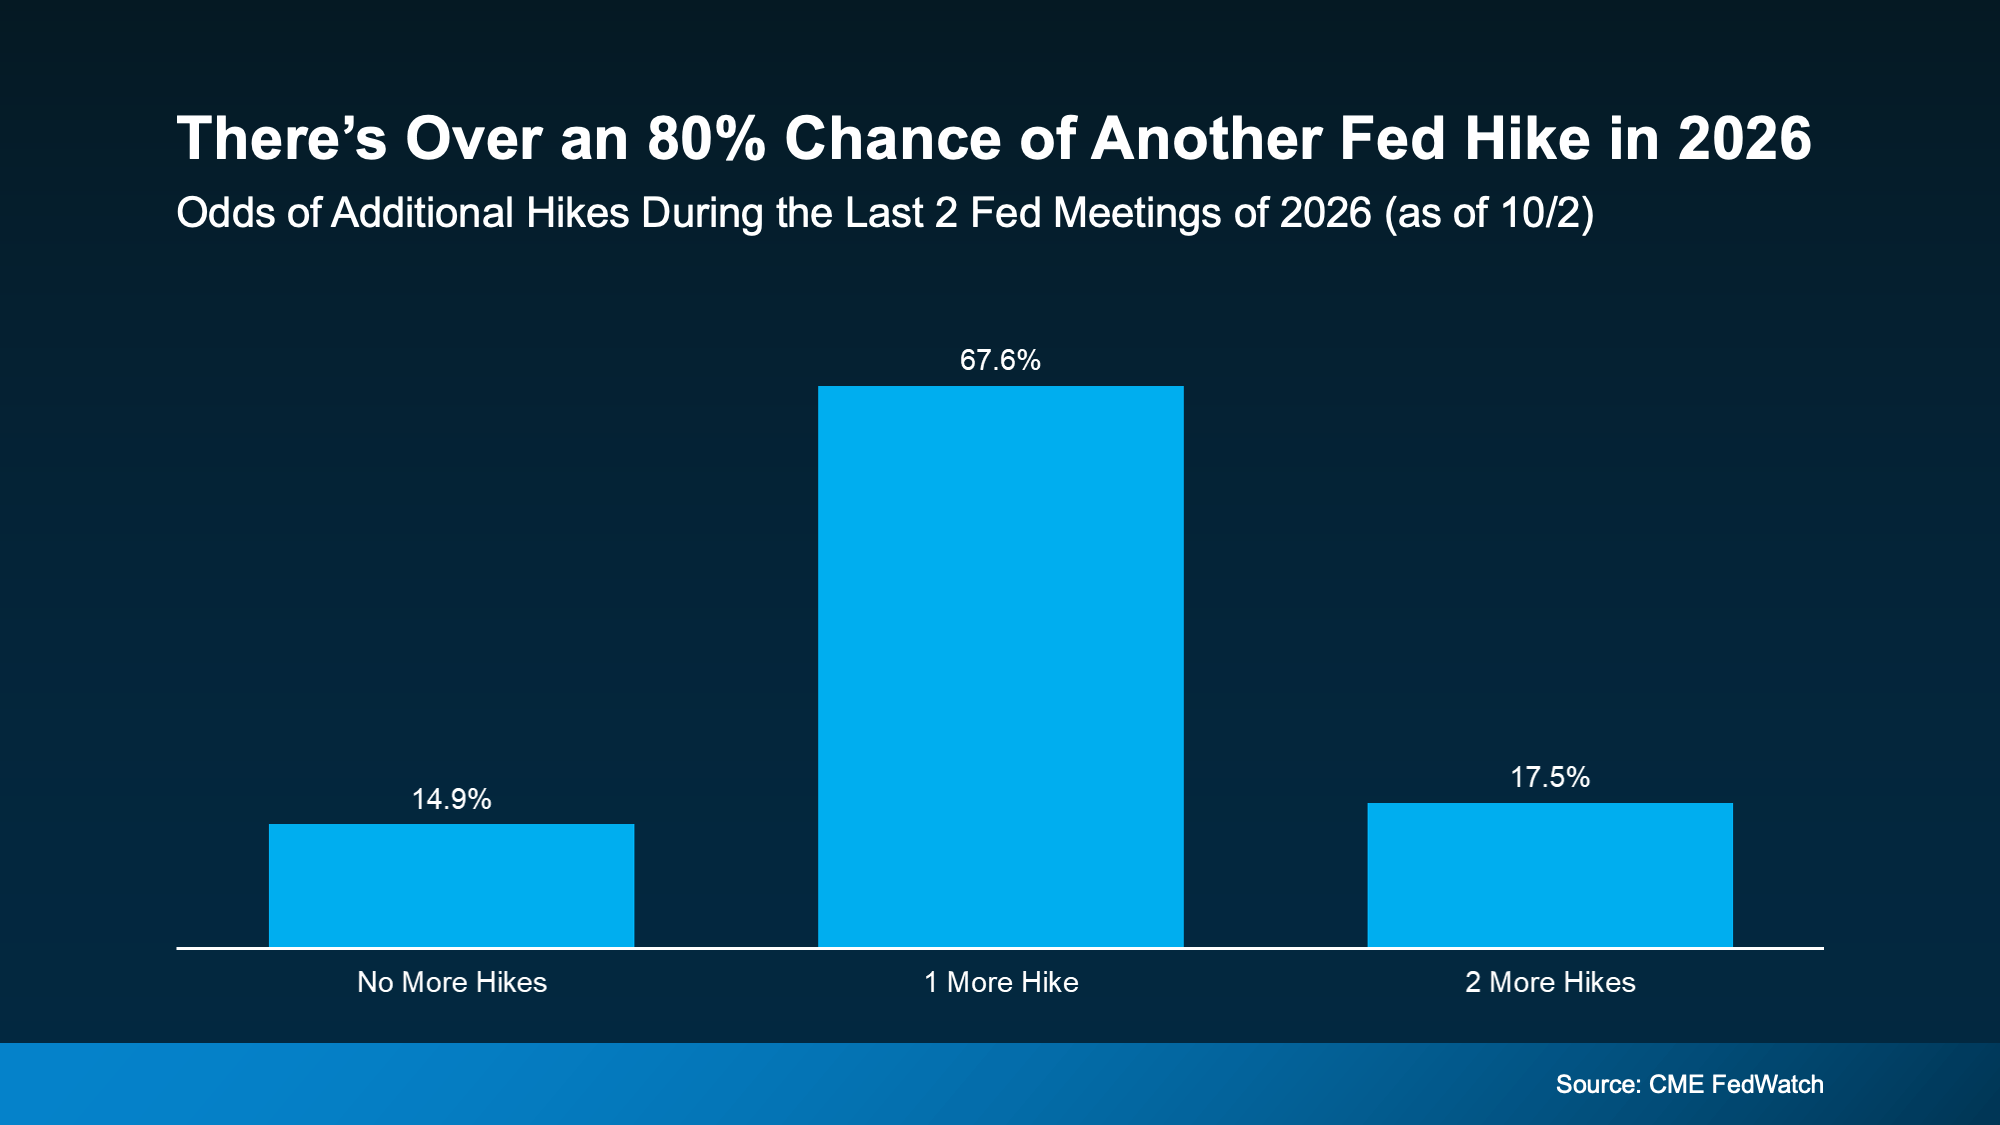
According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):
a graph of hikers with blue squares

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:

“Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control.“

And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:

  • PCE inflation dropped to 3.4%, down from 3.7% in July.

  • Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.

That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.

How To Make Your Move Work Right Now

While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.

  • If you’re buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you’re under contract, lock your rate so a jump before closing doesn’t raise your payment.

  • If you’re selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today’s buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.

Bottom Line

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today’s rates.
What Higher Mortgage Rates Mean for Home Sellers

What Higher Mortgage Rates Mean for Home Sellers

What Higher Mortgage Rates Mean for Home Sellers Simplifying The Market

Higher mortgage rates don’t just affect buyers. They can change what it takes to sell your house, too.

That’s because today’s buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they’re looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.

If you’re planning to sell, that doesn’t mean you can’t compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.

Builders Are Competing on the Monthly Payment

New construction has something interesting going for it right now. While existing-home sales  (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.

In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.

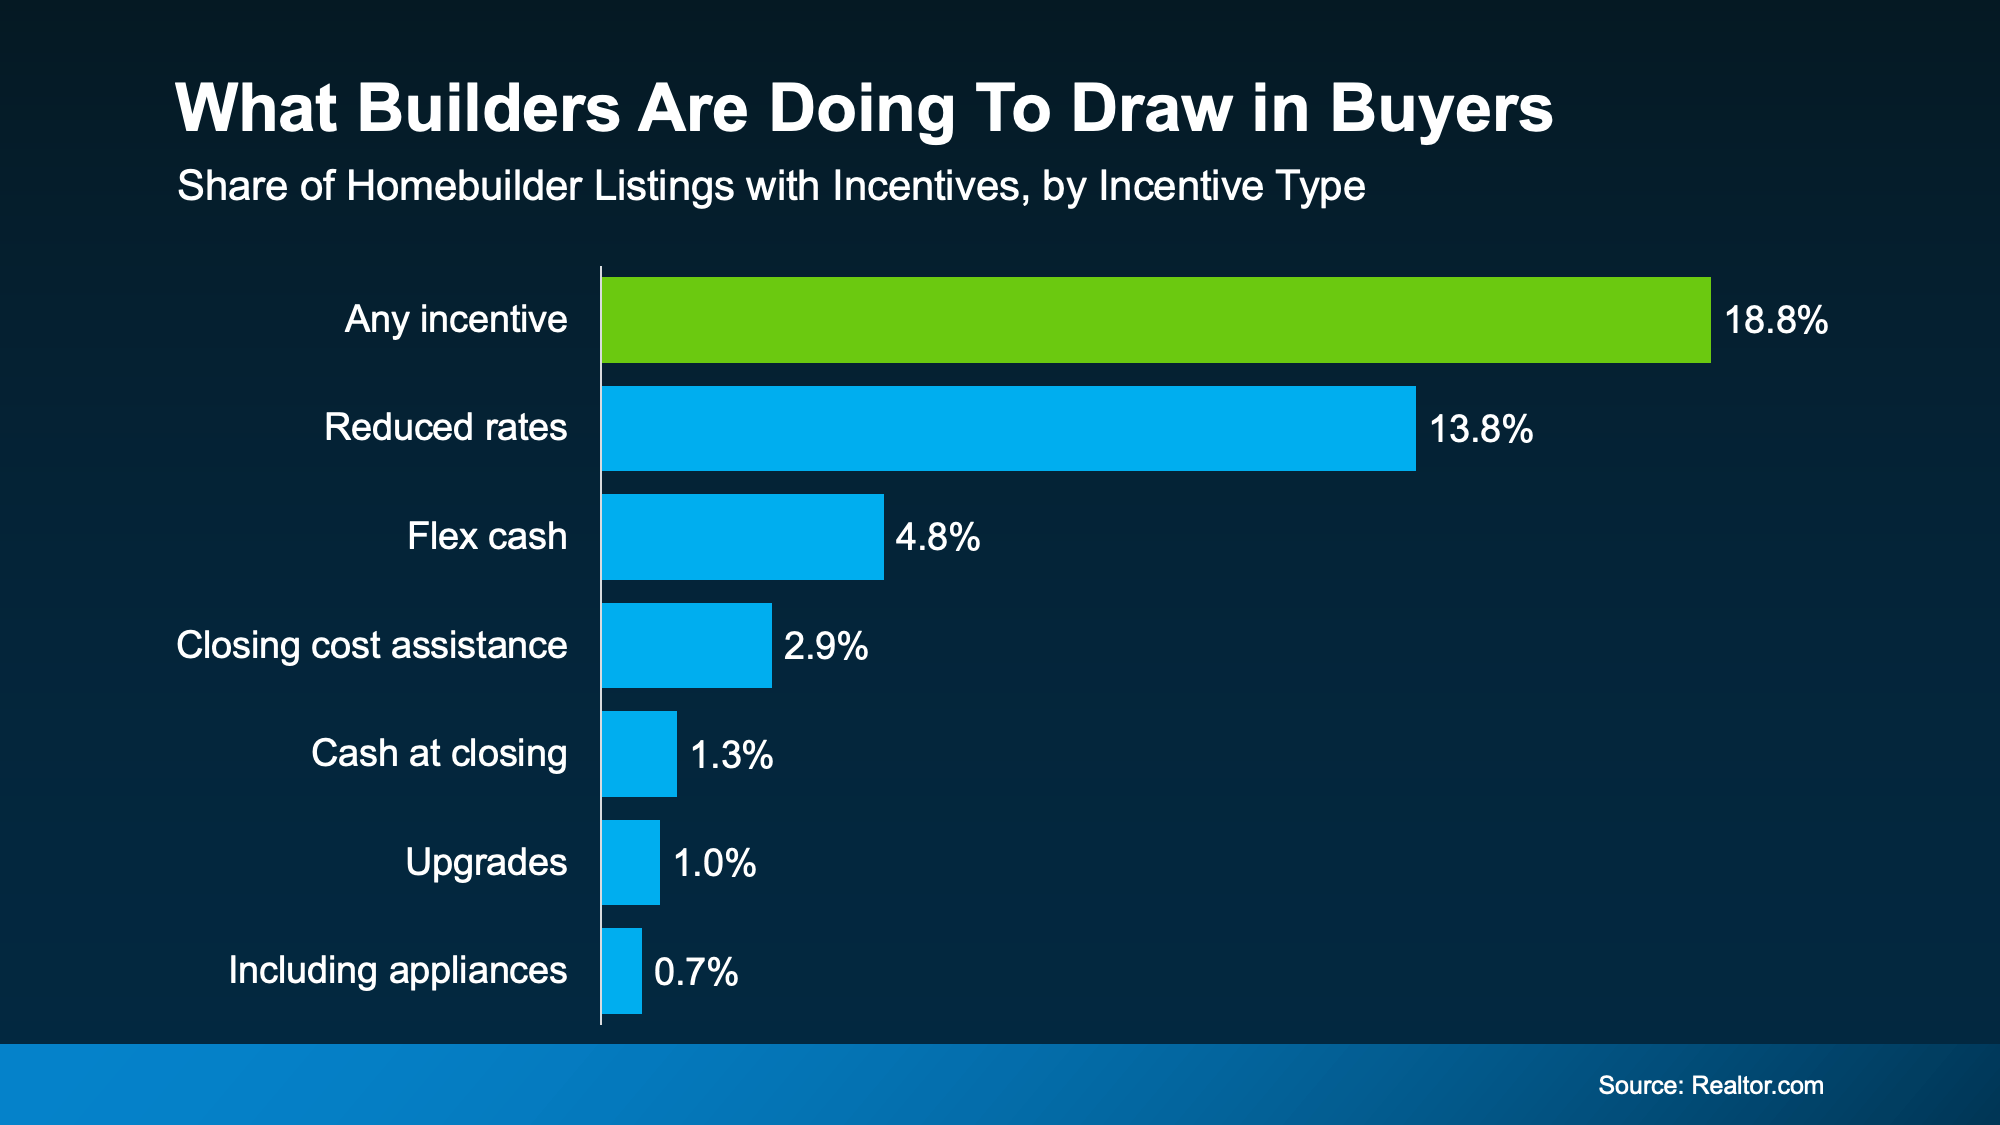
One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:

a graph of a company's sales

The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.

It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.

In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That’s a big difference to a buyer who are feeling the pinch right now.

So, How Can Sellers Like You Compete?

First, don’t assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer’s rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.

A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can’t. That’s why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:

“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”

A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.

Today’s Market Rewards Sellers Who Adapt

Builders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That’s putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:

“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”

That’s an important message if you’re hoping to sell.

You don’t automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.

And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren’t equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.

Bottom Line

Higher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with rate buydowns, closing-cost help, price reductions, and other incentives.

If you’re thinking about selling, talk to an agent about what buyers are getting from other homes in your area – including new construction – so you can make sure your house is positioned to compete.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get. Simplifying The Market

You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember… 

That’s not necessarily the number you’d get. 

It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. 

What Determines Your Real Rate? 

Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. 

That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:

  • Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.

  • Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.

  • The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. 

  • The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. 

Even after you find a home you love, other things can have an impact too. For example:

  • A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.

  • Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. 

There’s a lot that can ultimately have an impact on your actual rate. 

Your First Step? Getting Pre-Approved.

If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. 

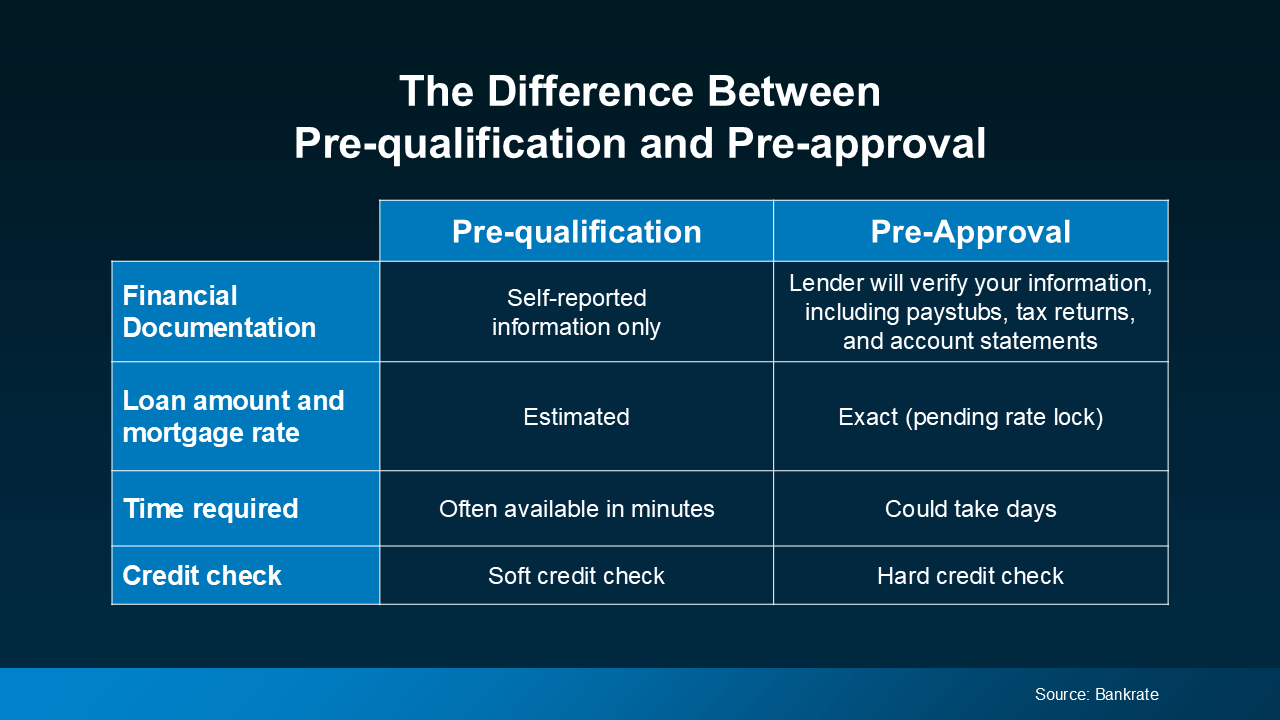
Your lender may recommend a pre-qualification and pre-approval:

  • Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. 

  • On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. 

Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:

a blue and white chart with white text

How To Get Ready for the Conversation

Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: 

  • What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? 

  • Will I get any tax advantages by buying a home – and what are they? 

  • What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?

  • How will rate changes in either direction affect me?

Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.  

Bottom Line

Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. 

With the right help, you can find out what your real rate is – and where it can take you.

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In? Simplifying The Market

Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell. Which type you’re in changes how you should buy or sell. Ryan Serhant, CEO of SERHANT agrees:

“There is no longer a housing market . . . There are four Americas.”

Here’s what each looks like, and what it means for you.

Cash Buyers: 1 in 4 Buyers Are Paying with Cash

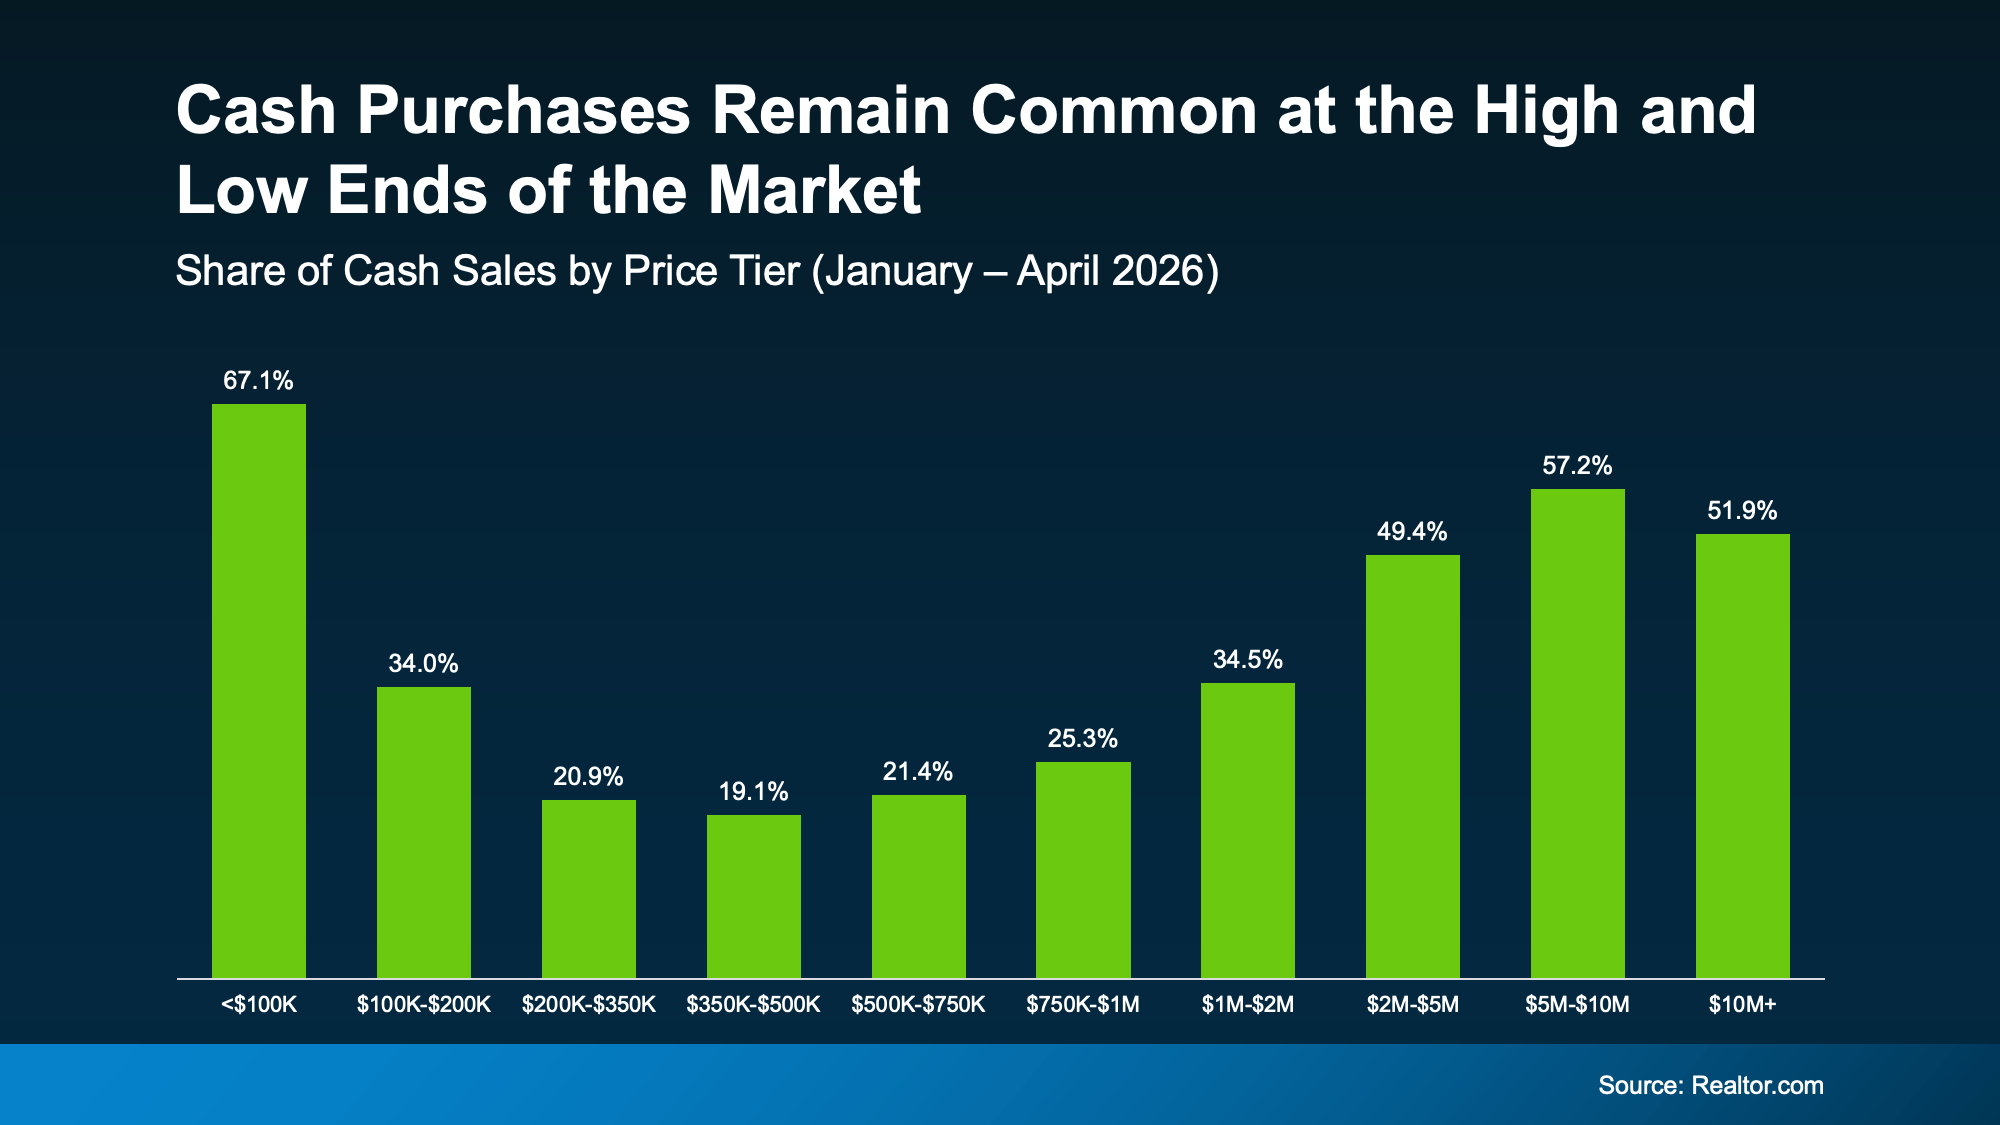
If you already own a home, you may be able to buy your next place in cash thanks to your equity. In fact, 26% of existing home sales this summer were all-cash, according to the National Association of Realtors (NAR). That’s roughly 1 in 4 buyers skipping a home loan entirely.

Data from Realtor.com shows most are at the very top and very bottom of the market by price point (see graph below):

a graph of green bars

For Buyers: If you’re able to buy in cash too, having no financing contingency means your offer is going to look really appealing to sellers. You may get a faster close and more room to negotiate.

For Sellers: A cash offer can mean less risk of the deal falling through, but that certainty sometimes comes with a lower number attached. Compare the whole picture before deciding it’s automatically your best offer.

Buyers Using Financing: They’re Not Getting Help from Rates, But They Are from Sellers

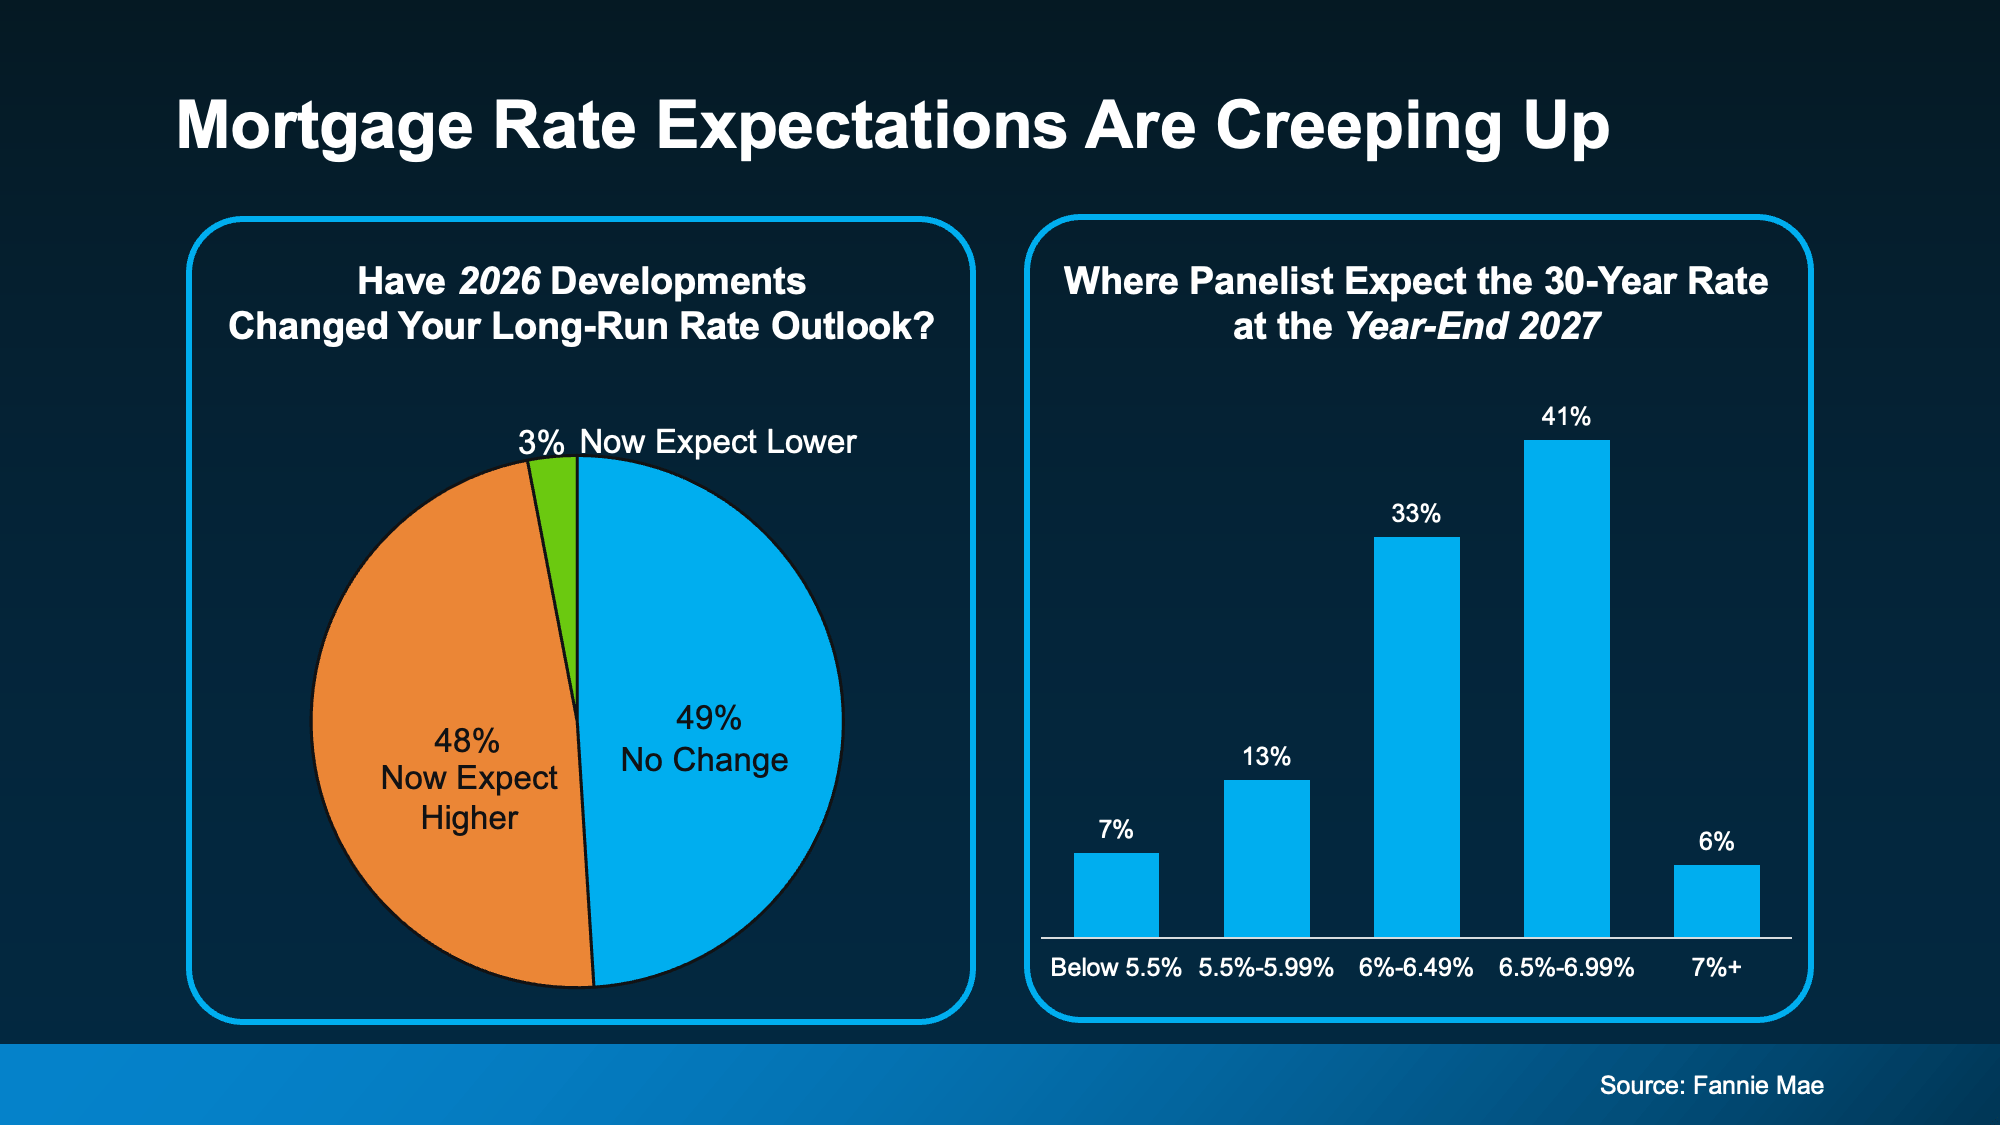
If you’re looking to take out a mortgage, you should know mortgage rates aren’t likely to come down anytime soon. Data from Fannie Mae shows nearly half of experts actually raised their long-term rate forecast this year (see graphs below):

a graph of growth and growth

That’s tough for homebuyers relying on a mortgage, especially first-time buyers. But it’s not all bad news.

While buyers may not be getting the lower rates they want, at least there’s help to be had if you ask sellers for what you really need. Redfin data shows almost half of May sales included a concession like a rate buydown or closing-cost credit from the homeowner.

For Buyers: Stop waiting on rates to drop. Negotiate the concession instead. If the payment works today, that’s your signal.

For Sellers: Expect to negotiate. Build a concession into your pricing strategy from the start could be the thing that gets a deal done.

Rate-Locked Homeowners: Most Are Sitting on a Rate Below 5%

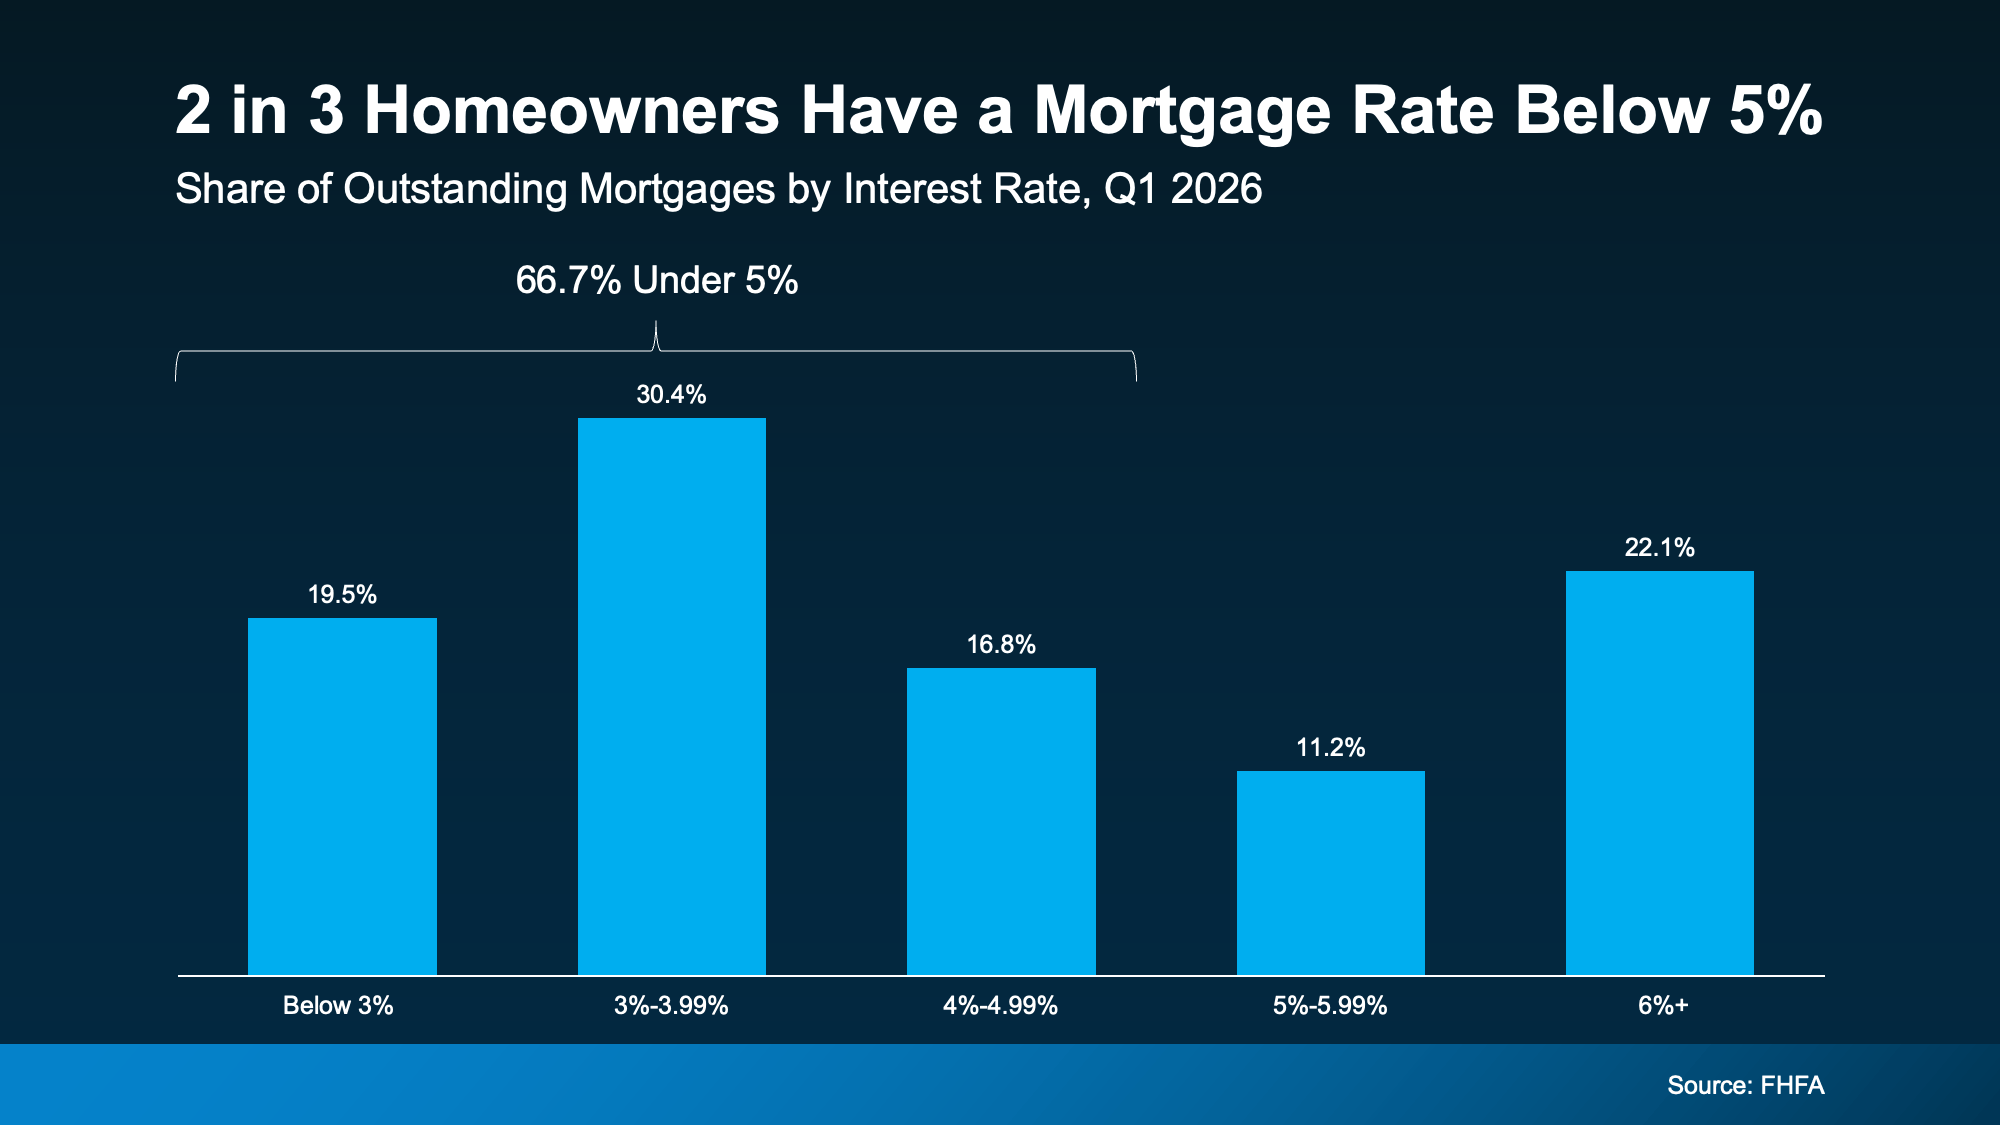
If you own a home already, you might not want to move and take on a higher rate than the one you’ve got. That’s the case for a lot of people. About 2 in 3 homeowners have a mortgage rate under 5%, according to Federal Housing Finance Agency (FHFA) data (see graph below).

When a homeowner has a rate that low, it’s harder for them to want to move and leave behind that ultra-low rate. Because, they’d likely have to take on a higher one on their next home. Hence “rate locked” – they feel locked in.

a graph of a graph with text

And, according to Fannie Mae data, most experts think that lock-in will stick around another 3-5 years. That means this will continue to be a factor in how many homes come up for sale.

For Buyers: Fewer homeowners are listing, but the ones who do usually have a real reason to move. They’re often more flexible, motivated sellers.

For Sellers: Run the math on what your equity actually buys before ruling out a move. Got an FHA or VA loan? Ask about making it assumable. It’s rare, but it’s a real selling point.

Homebuilders: They’re Negotiating More Than You Think

If you’re looking at new construction, this might be your moment. According to the latest Census data, builders have more unsold new homes sitting around than usual, enough that it would take nearly 10 months to sell them all at the current pace (well above the normal 4-6 months pace). That’s pushing builders toward price cuts and rate buydowns.

For Buyers: That’s where the deals are right now. Just be sure to use your own agent and compare the whole incentive package, not only the price tag.

For Sellers: Lead with what a builder can’t offer – mature landscaping, an established neighborhood, and a house that’s ready today, not in 8 months. That can help your house seem like a better optiona

Bottom Line

Four different housing markets are running at once: cash buyers, financed buyers, locked-in owners, and builders. Each one plays by its own rules, and the right move for one is exactly the wrong move for another.

Connect with a local real estate agent to figure out which one you’re actually in and build your next move from there.

3 Things You Can Actually Control About Your Mortgage Rate Right Now

3 Things You Can Actually Control About Your Mortgage Rate Right Now

3 Things You Can Actually Control About Your Mortgage Rate Right Now Simplifying The Market

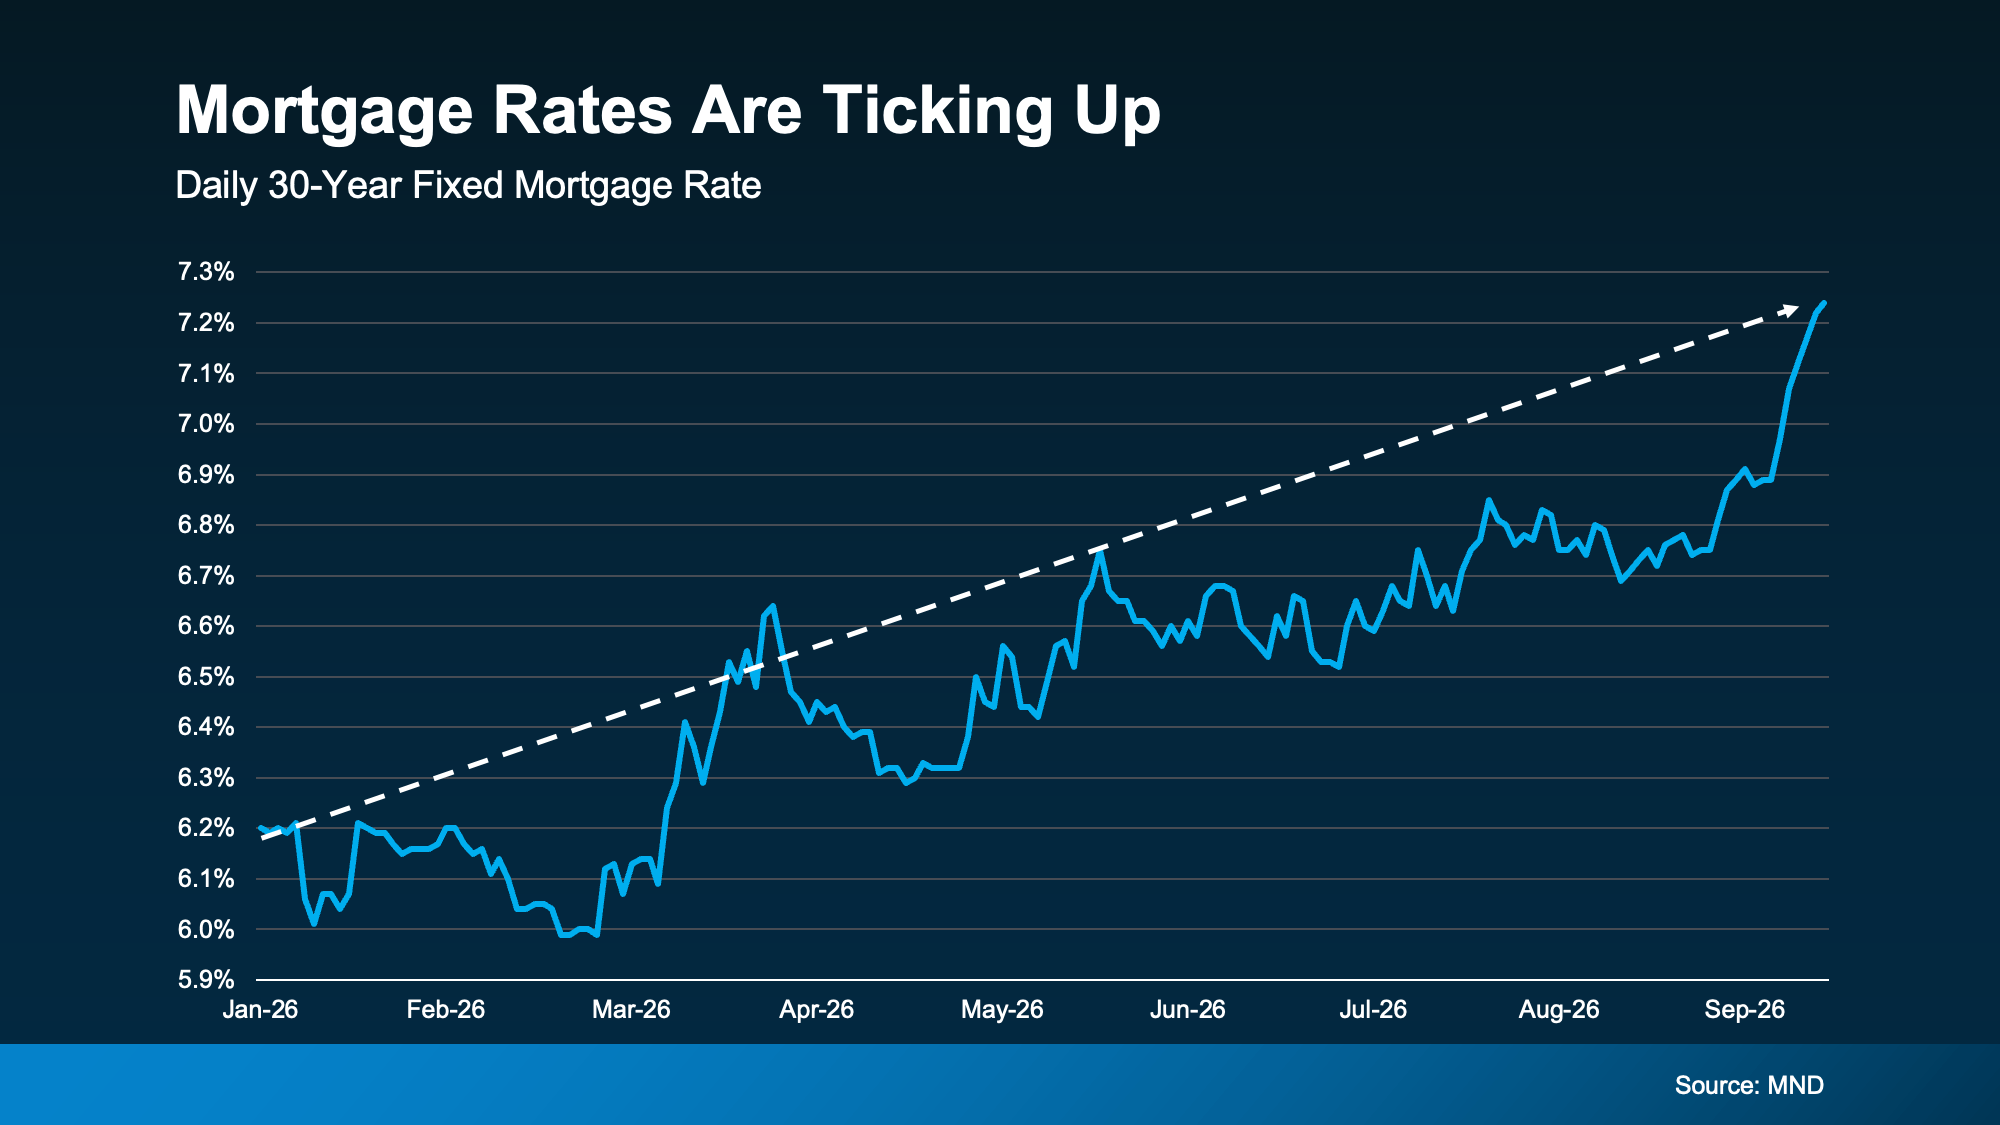
If you’re trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and wait for them to go down.

For now, though, they’re headed the other way. Mortgage News Daily data shows how rates have risen this year (see graph below):

a graph of a moving rate

And if you’re wondering why? There are actually a number of reasons. 

Mortgage rates are impacted by the situation overseas, economic data, inflation numbers, oil prices, and even decisions from the Federal Reserve (who recently decided to hike their Fed Funds Rate – which often affects mortgage rates too). As Danielle Hale, Chief Economist at Realtor.com, explains:

“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”

Now, that’s probably not what you wanted to hear. But, it doesn’t mean there’s nothing you can do. While you can’t control where rates go from here, you absolutely can control several things that shape the rate you actually get. 

So where should you focus? Let’s walk through it.

Work on Your Credit Score

Your credit score plays a big role in the rate you qualify for, and even a small improvement can make a real difference in your monthly payment. As Freddie Mac puts it:

“Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate.“

So, make sure you do what you can to keep your credit score up. If you’re not sure where your score stands right now, or how to improve it, talk to a trusted loan officer.

Explore Your Loan Options

The type and term of your loan both affect your rate. Conventional, FHA, VA, and USDA loans each come with their own requirements and rates, and your term (15, 20, or 30 years) changes both your payment and the total interest you’ll pay. The structure matters, too. A fixed-rate loan holds the same rate over time, while an adjustable-rate loan usually starts lower and can move later on. Bankrate explains it this way:

“. . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk.“

It’s important to explore your options with a lender to see what makes the most sense for you. Just be sure to balance your goals, your possible rate, and any potential tradeoffs before making any decision. You may even want to talk to multiple lenders to see how the options vary. 

Consider a Newly Built Home

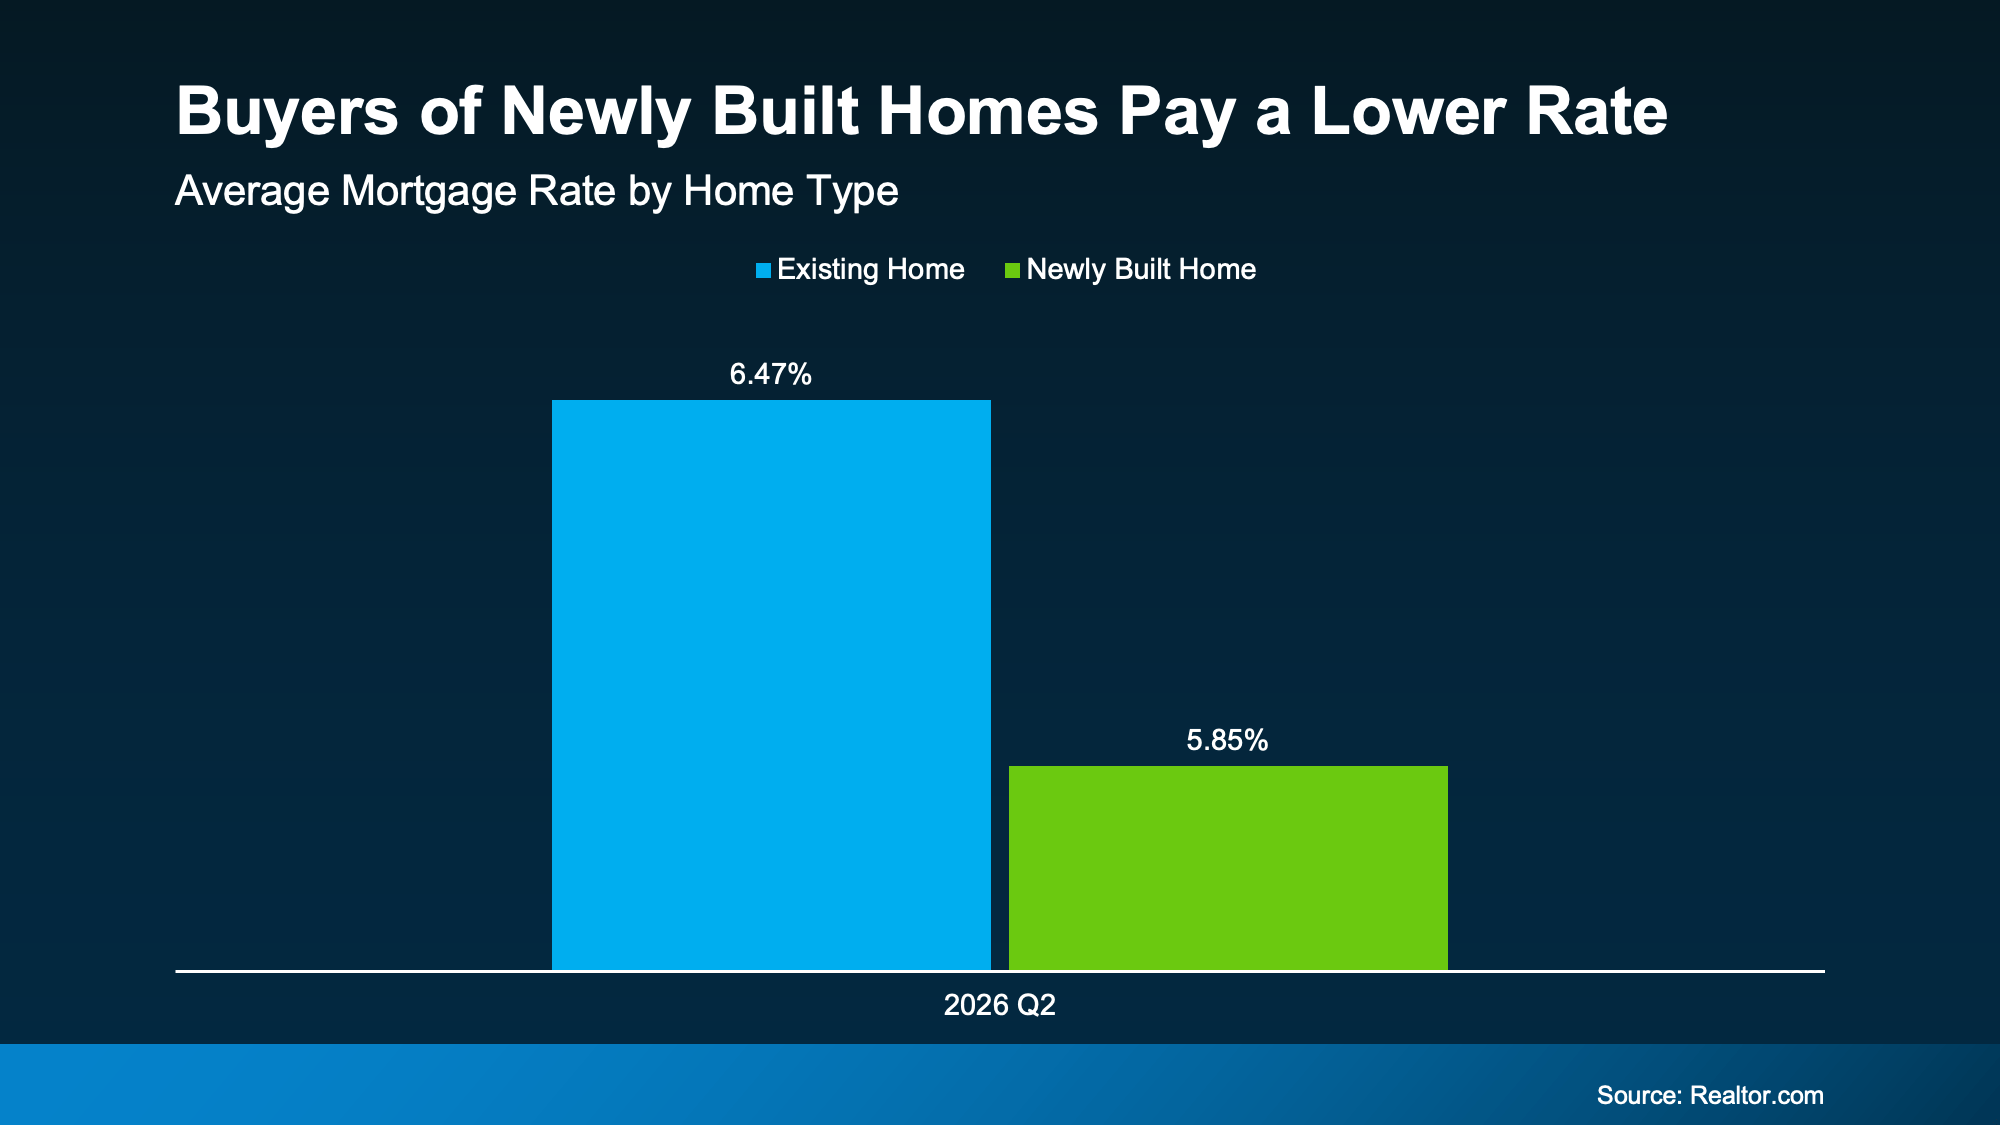
Another path to a lower rate comes down to the kind of home you buy. Many builders are buying down mortgage rates, which lowers your monthly payment. It’s just one way they’re trying to attract buyers and get their homes sold.

According to Realtor.com, buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes (see graph below):

a graph of a graph showing a number of houses

If a lower rate is your goal, it may be worth asking your agent to show you some new build communities that are offering this type of incentive locally.

Bottom Line

You can’t control where mortgage rates go, but you can control your credit, your loan, and the kind of home you buy. Working with a trusted lender can help you lock in the best rate you qualify for. And when you’re ready to make a move that fits your budget, connect with a local real estate agent.

The Best Time To Buy a Home in 2026 Is Almost Here

The Best Time To Buy a Home in 2026 Is Almost Here

The Best Time To Buy a Home in 2026 Is Almost Here Simplifying The Market

Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.

Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.

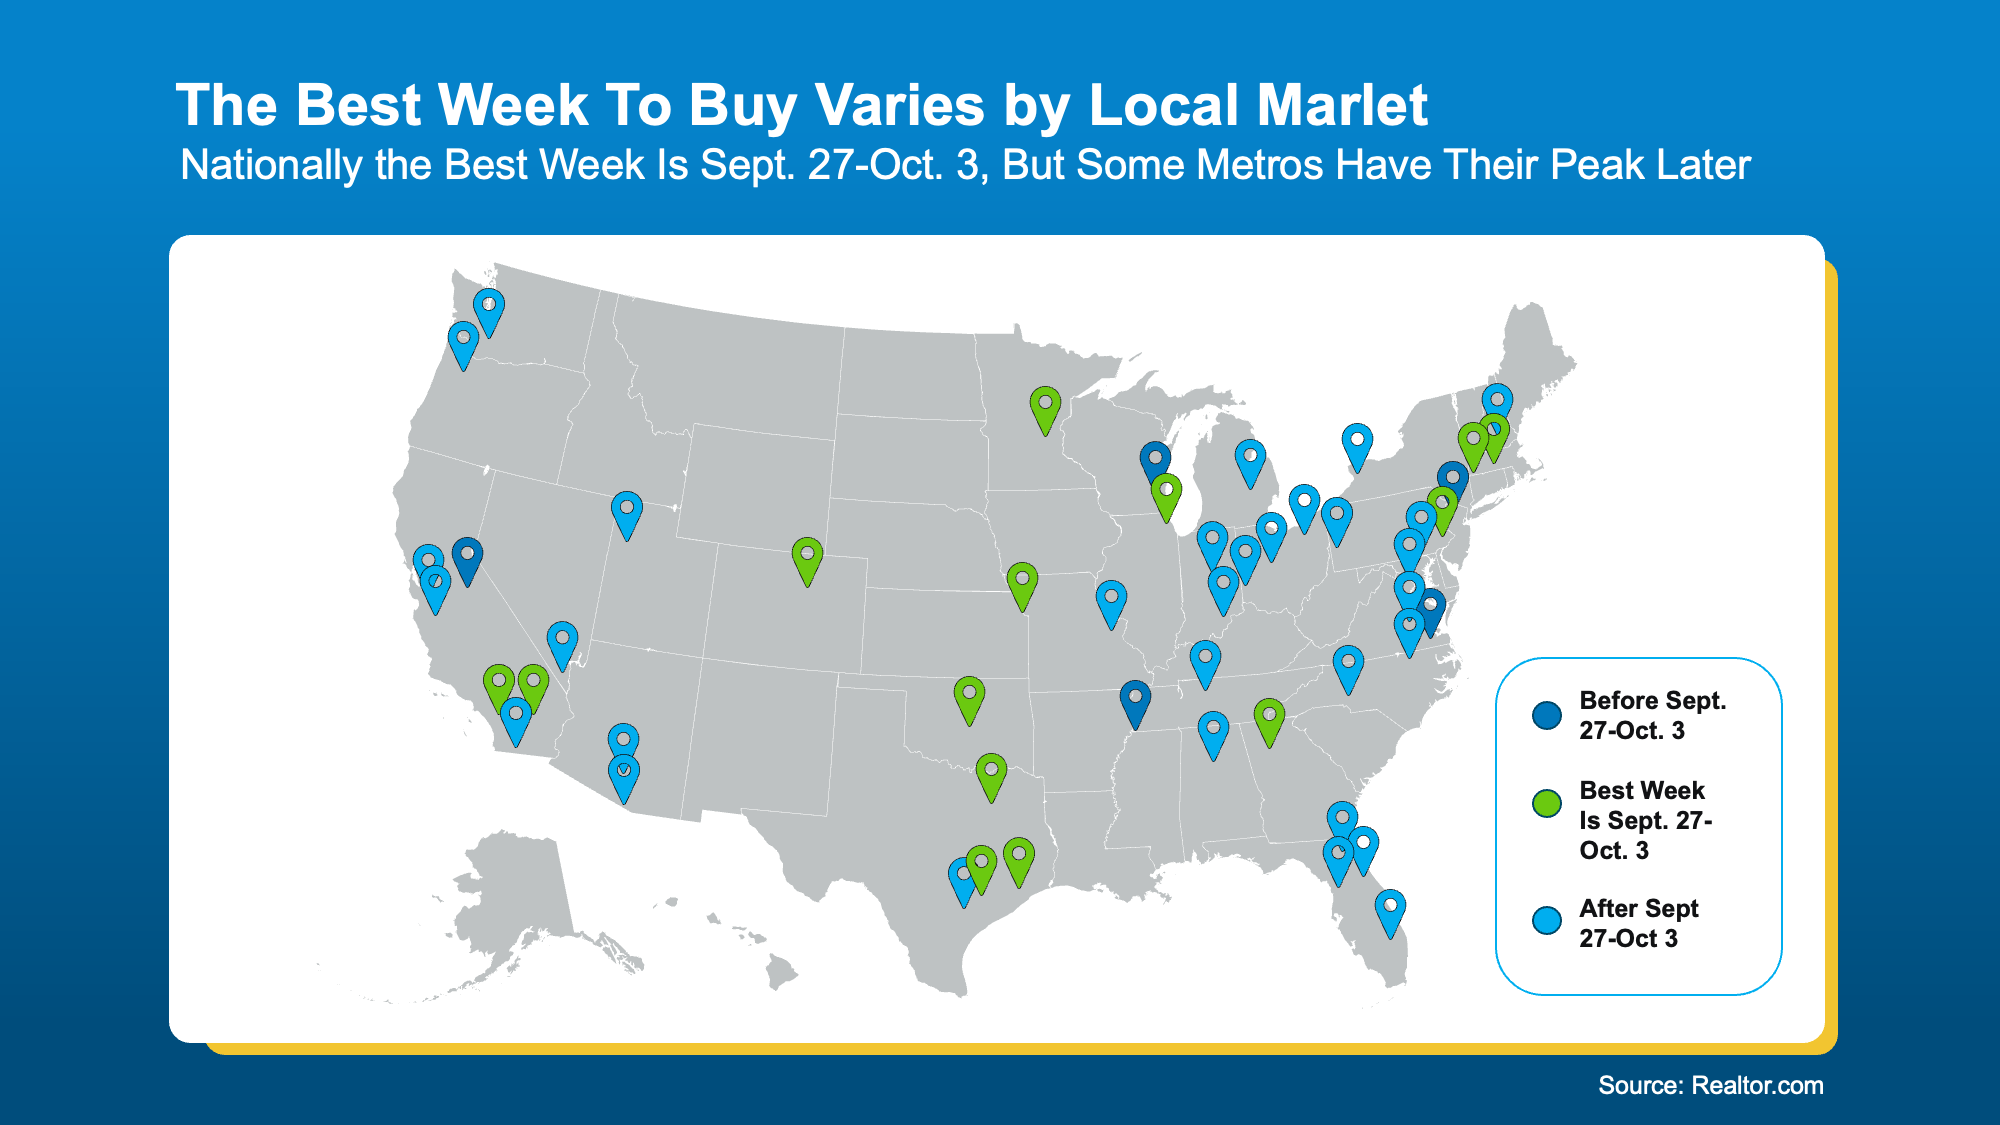
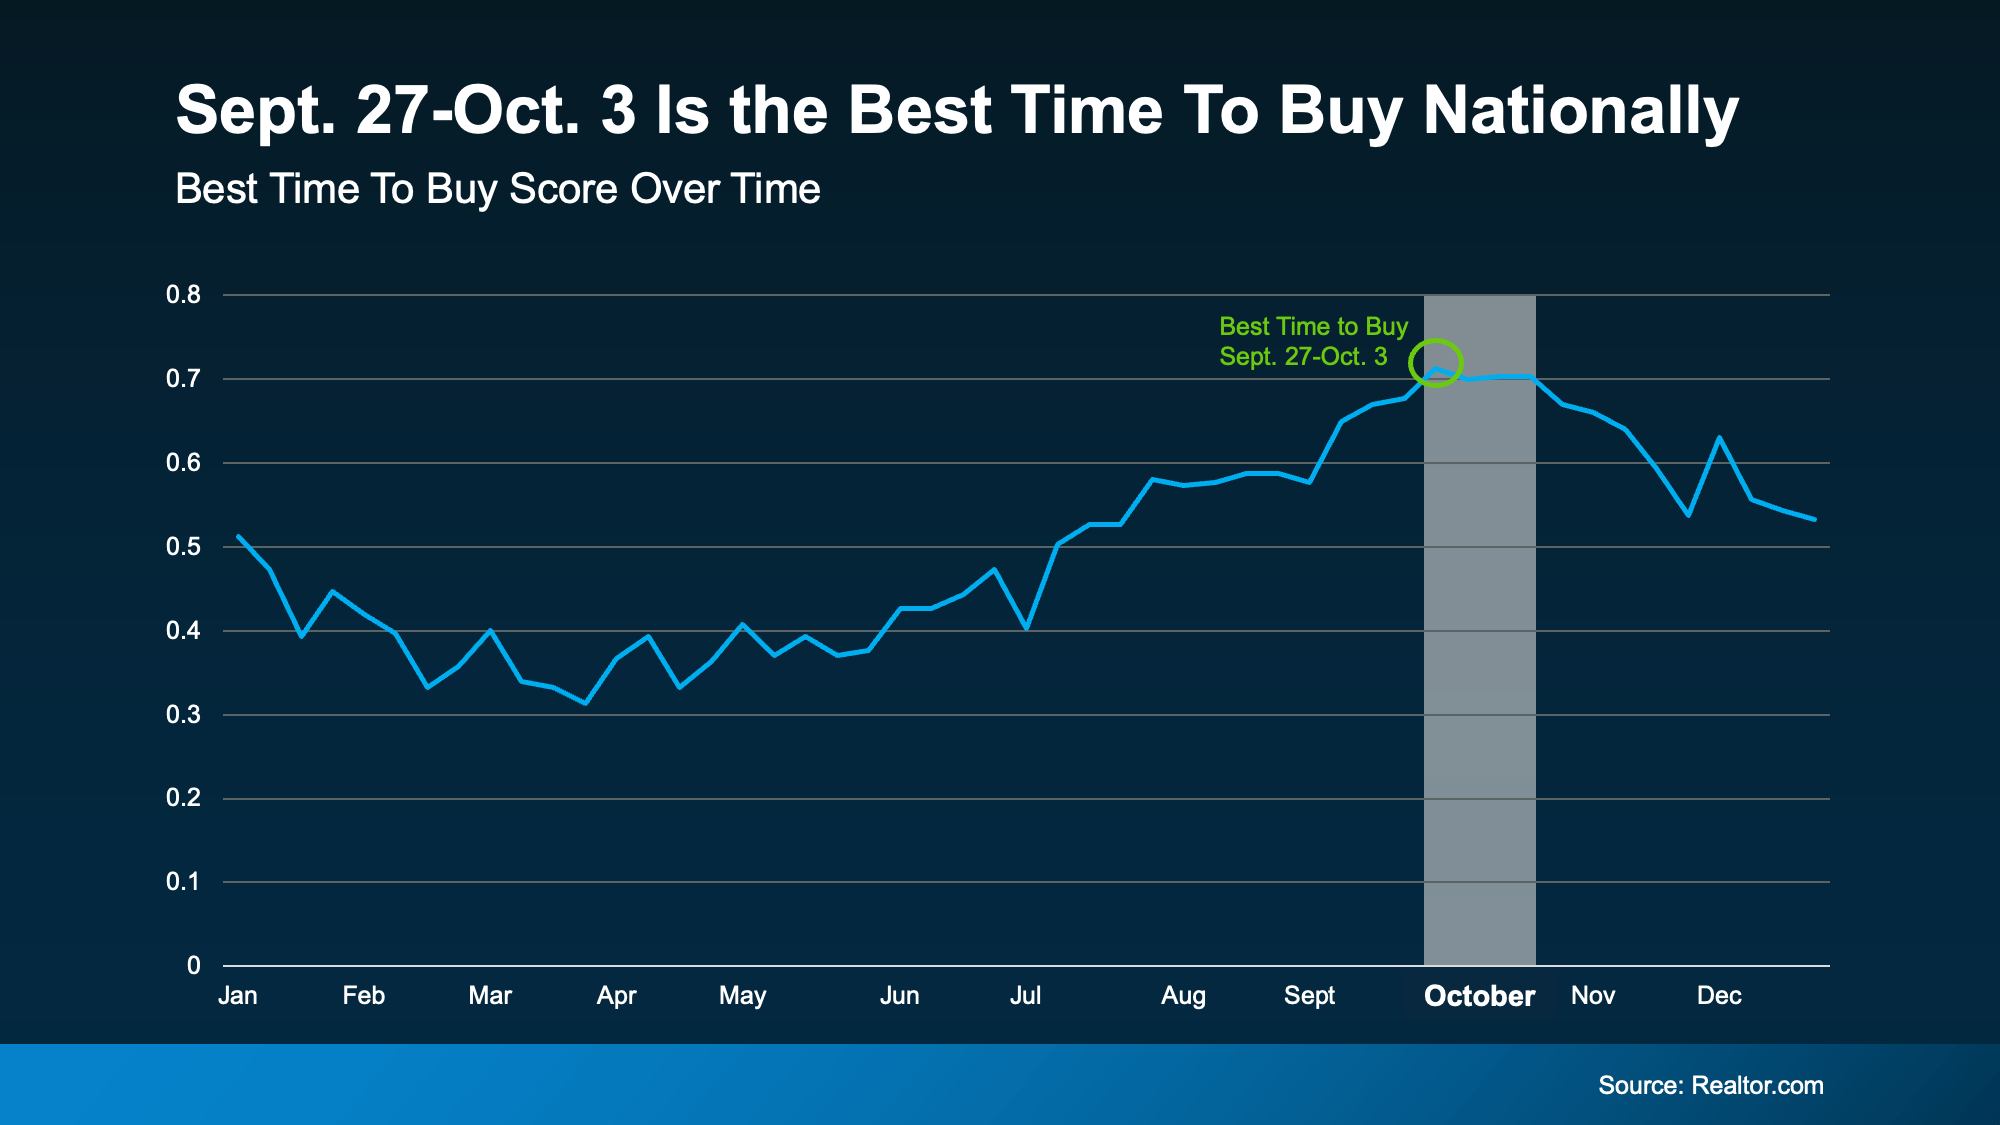
According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:

“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence.”

But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):

a map of the united states with pins

It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.

More Choices, Better Prices, and Less Competition

For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:

“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”

That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.

Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision. 

  • More choices.

  • Better pricing.

  • Less competition.

That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.

The Window Doesn’t Close After This One Week

But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:

a graph on a dark background

In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains: 

“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”

Bottom Line

If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.

Want help figuring out when those advantages typically show up in your market?

Have a quick conversation with a lender and a local agent about how your market works and the steps you’ll need to take to get ready. 

Pin It on Pinterest