If you were thinking about buying a home this year, but already pressed pause on your plans due to rising home prices and increasing mortgage rates, there’s something you should consider. According to the latest report from ATTOM Data, owning a home is more affordable than renting in the majority of the country. The 2022 Rental Affordability Report says:
“. . . Owning a median-priced home is more affordable than the average renton a three-bedroom property in 666, or 58 percent, of the 1,154 U.S. counties analyzed for the report. That means major home ownership expenses consume a smaller portion of average local wages than renting.”
Other experts in the industry offer additional perspectives on renting today. In the latest Single-Family Rent Index from CoreLogic, single-family rent saw the fastest year-over-year growth in over 16 years when comparing data for November each year (see graph below):
Molly Boesel, Principal Economist at CoreLogic, stresses the importance of what the data shows:
“Single-family rent growth hit its sixth consecutive record high. . . . Annual rent growth . . . was more than three times that of a year earlier. Rent growth should continue to be robust in the near term, especially as the labor market continues to improve.”
What Does This Mean for You?
While it’s true home prices and mortgage rates are rising, so are monthly rents. As a prospective buyer, rising rates and prices shouldn’t be enough to keep you on the sideline, though. As the chart above shows, rents are skyrocketing. The big difference is, when you rent, that rising cost benefits your landlord’s investment strategy, but it doesn’t deliver any sort of return for you.
In contrast, when you buy a home, your monthly mortgage payment serves as a form of forced savings. Over time, as you pay down your loan and as home values rise, you’re building equity (and by extension, your own net worth). Not to mention, you’ll lock in your mortgage payment for the duration of your loan (typically 15 to 30 years) and give yourself a stable and reliable monthly payment.
When asking yourself if you should keep renting or if it’s time to buy, think about what Todd Teta, Chief Product Officer at ATTOM Data, says:
“. . . Home ownership still remains the more affordable option for average workers in a majority of the country because it still takes up a smaller portion of their pay.”
If buying takes up a smaller portion of your pay and has benefits renting can’t provide, the question really becomes: is renting really worth it?
Bottom Line
If you’re weighing your options between renting and buying, it’s important to look at the full picture. While buying a home can feel like a daunting process, having a trusted advisor on your side is key. Work with an agent to explore your options so you can learn more about the benefits of homeownership today.
Are you one of the many renters thinking about where you’ll live the next time your lease is up? Before you decide whether to look for a new house or another apartment, it’s important to understand the true costs of renting in 2022.
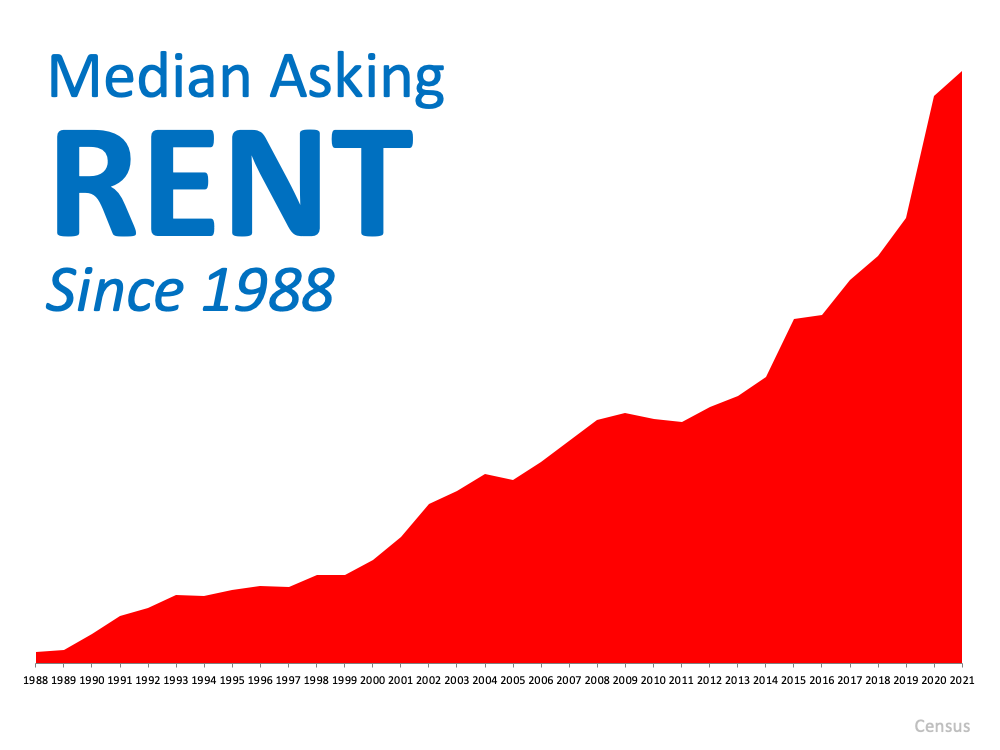
As a renter, you should know rents have been rising since 1988 (see graph below):
In 2021, rents grew dramatically. According to ApartmentList.com, since January 2021:
“. . . the national median rent has increased by a staggering 17.8 percent. To put that in context, rent growth from January to November averaged just 2.6 percent in the pre-pandemic years from 2017-2019.”
That increase in 2021 was far greater than the typical rent increases we’ve seen in recent years. In other words – rents are rising fast. And the 2022 National Housing Forecast from realtor.com projects prices for vacant units will continue to increase this year:
“In 2022, we expect this trend will continue and fuel rent growth. At a national level, we forecast rent growth of 7.1% in the next 12 months, somewhat ahead of home price growth . . .”
That means, if you’re planning to move into a different rental this year, you’ll likely pay far more than you have in years past.
Homeownership Provides an Alternative to Rising Rents
If you’re a renter facing rising rental costs, you might wonder what alternatives you have. If so, consider homeownership. One of the many benefits of homeownership is it provides a stable monthly cost you can lock in for the duration of your loan.
As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:
“. . . fast-rising rents and increasing consumer prices, may have some prospective buyers seeking the protection of a fixed, consistent mortgage payment.”
If you’re planning to make a move this year, locking in your monthly housing costs for 15-30 years can be a major benefit. You’ll avoid wondering if you’ll need to adjust your budget to account for annual increases.
Homeowners also enjoy the added benefit of home equity, which has grown substantially right now. In fact, the latest Homeowner Equity Insight report from CoreLogic shows the average homeowner gained $56,700 in equity over the last 12 months. As a renter, your rent payment only covers the cost of your dwelling. When you pay your mortgage, you grow your wealth through the forced savings that is your home equity.
Bottom Line
If you’re thinking of renting this year, it’s important to keep in mind the true costs you’ll face. Let’s connect so you can see how you can begin your journey to homeownership today.
As a renter, you’re constantly faced with the same dilemma: keep renting for another year or purchase a home? Your answer depends on your current situation and future plans, but there are a number of benefits to homeownership every renter needs to consider.
Here are a few things you should think about before you settle on renting for another year.
1. Rents Are Rising Quickly
Rent increasing each year isn’t new. Looking back at Census data confirms rental prices have gone up consistently for decades (see graph below):If you’re a renter, you’re faced with payments that continue to climb each year. Realtor.com recently shared the September Rental Report, and it shows price increases accelerating from August to September (see graph below):As the graph shows, rents are still on the rise. It’s important to keep this in mind when the time comes for you to sign a new lease, as your monthly rental payment may increase substantially when you do.
2. Renters Miss Out on Equity Gains
One of the most significant advantages of buying a home is the wealth you build through equity. This year alone, homeowners gained a substantial amount of equity, which, in turn, grew their net worth. As a renter, you miss out on this wealth-building tool that can be used to fund your retirement, buy a bigger home, downsize, or even achieve personal goals like paying for an education or starting a new business.
3. Homeowners Can Customize to Their Heart’s Content
This is a big decision-making point if you want to be able to paint, renovate, and make home upgrades. In many cases, your property owner determines these selections and prefers you don’t alter them as a renter. As a homeowner, you have the freedom to decorate and personalize your home to truly make it your own.
4. Owning a Home May Provide Greater Mobility than You Think
You may choose to rent because you feel it provides greater flexibility if you need to move for any reason. While it’s true that selling a home may take more time than finding a new rental, it’s important to note how quickly houses are selling in today’s market. According to the National Association of Realtors (NAR), the average home is only on the market for 17 days. That means you may have more flexibility than you think if you need to relocate as a homeowner.
Bottom Line
Deciding if it’s the right time for you to buy is a personal decision, and the timing is different for everyone. However, if you’d like to learn more about the benefits of homeownership, let’s connect so you can make a confident, informed decision and have a trusted advisor along the way.
Rents have increased significantly this year. The latest National Rent Report from Apartmentlist.com shows rents are rising at a rate much higher than the three years leading up to the pandemic:
“Since January of this year, the national median rent has increased by a staggering 16.4 percent. To put that in context, rent growth from January to September averaged just 3.4 percent in the pre-pandemic years from 2017-2019.”
Looking back, we can see rents rising isn’t new. The median rental price has increased consistently over the past 33 years (see graph below):If you’re thinking of renting for another year, consider that rents will likely be even higher next year. But that alone doesn’t paint the picture of the true cost of renting.
The Money Renters Stand To Lose This Year
A homeowner’s monthly mortgage payment pays for their shelter, but it also acts as an investment. That investment grows in the form of equity as a homeowner makes their mortgage payment each month to pay down what they owe on their home loan. Their equity gets an additional boost from home price appreciation, which is at near-record levels this year.
The latest Homeowner Equity Insights report from CoreLogic found homeowners gained significant wealth through their home equity this past year. The research shows:
“. . . the average homeowner gained approximately $51,500 in equity during the past year.”
As a renter, you don’t get the same benefit. Your rent payment only covers the cost of shelter and any included amenities. None of your monthly rent payments come back to you as an investment. That means, by renting this year, you likely paid more in rent than you did in the previous year, and you also missed out on the potential wealth gain of $51,500 you could have had by owning your own home.
Bottom Line
When deciding whether you should rent or buy in the future, keep in mind how much renting can cost you. Another year of renting is another year you’ll pay rising rents and miss out on building your wealth through home equity. Let’s connect today to talk more about the benefits of buying over renting.
Let me start by saying that I am excited for you. The only reason that you would be reading this is because you have determined that owning a home may be right for you. It means that you are at least exploring the possibilities and considering what life would look like as a homeowner. That alone is exciting and a proposition that is full of promise.
Your reading this also means that I have a chance to earn the opportunity to help you to achieve Your Own Personal American Dream. One of the reasons that I love my job is because I get to help people just like you create and shape their lifestyle through homeownership. It is truly an honor when someone allows me that opportunity. So let me share with you how I can help.
All of our services start with a quick 15 – 30 minute coaching call which is a basic introductory consultation. On that call you take out your dream paint brush and start painting a picture of what your American Dream looks like. I will ask you some specific questions about your plans and qualifications and, if we both decide at the end of that call that we should move to the next stage, we will schedule your comprehensive buyer consultation.
Depending on your experience as a homeowner/future homeowner, right off the bat you will notice that my approach is much different than 98% or more of real estate agents that you may have talked to or even worked with in the past. Since 1989 I have been a full time REALTOR® and have had the privilege of helping hundreds of families, couples, and individuals buy and sell homes. I discovered along the way that the more time taken in planning and preparing up front, the more successful the home purchase or sale would be in the end.
As your HousingCoach℠ I will help you to develop and solid home buying game plan which will incorporate your current circumstances and your plans, goals, and dreams for the next 5, 10, or even 20 or more years into the future. Your success as a home buyer can be measured in how well you are equipped and prepared to find the home that best fits your plan, compete against other home buyers, negotiate with the seller from a place of strength, and complete the transaction with as few hassles as possible.
Once we decide to work together I will help you to build out your Home Buying Game Plan, assemble your Home Buying Real Estate Team, structure and activate an automated Home Search Process, prepare you to have the best competitive advantage, negotiate on your behalf to get the best possible deal, and coordinate all of the transaction requirements and activities until the deal is closed.
My goal is that in the process of helping you to achieve Your Personal American Dream, that you are provided a personal level of service such that you feel compelled to refer me and my services to your family, friends, co-workers, and people you care about. That is how I will know I did my job well.
A recent survey from LendingTree.com found there are multiple reasons why Americans would choose to purchase a home instead of renting. Some of the most popular non-financial reasons given include:
The flexibility to make the space your own
The pride homeownership offers
The sense of stability
In the same survey, 41% of respondents say they’d rather own a home than rent because of the unique way homeownership builds wealth over time.
And experts agree – the home you own is an important tool for building your net worth. Here’s what many of those experts have to say about building long-term financial stability through homeownership.
“Homeowners who purchased a typical single-family existing-home 30 years ago at the median sales price of $103,333 with a 10% down payment loan and who sold the property at the median sales price of $357,700 in 2021 Q2 accumulated housing wealth of $349,258, . . .”
Mark Fleming, Chief Economist at First American, points out that a home is truly a one-of-a-kind asset. It’s the only asset that’s both an investment and a place for you to call your own.
“The major financial advantage of homeownership is the accumulation of equity in the form of house price appreciation. . . . We won’t always have 17% house price appreciation, but we have to take into account the fact that the shelter that you’re owning is an equity-generating or wealth-generating asset.”
Homeowners can leverage the wealth they generate in several ways throughout their life. Tapping into accumulated equity has long been used to pay for the cost of an education, to start a business, or to fund various other expenses. The Joint Center of Housing Studies at Harvard points out:
“. . . by paying down mortgage principal each month and participating in the long-term appreciation of home values, a family can build wealth that can be used for retirement or other needs, including helping the next generation.”
Bottom Line
With home prices expected to continue to appreciate in coming years, homebuyers have an opportunity to start the long-term wealth-building process right now. Let’s connect today if you’re ready to begin your journey on the path to becoming a homeowner.