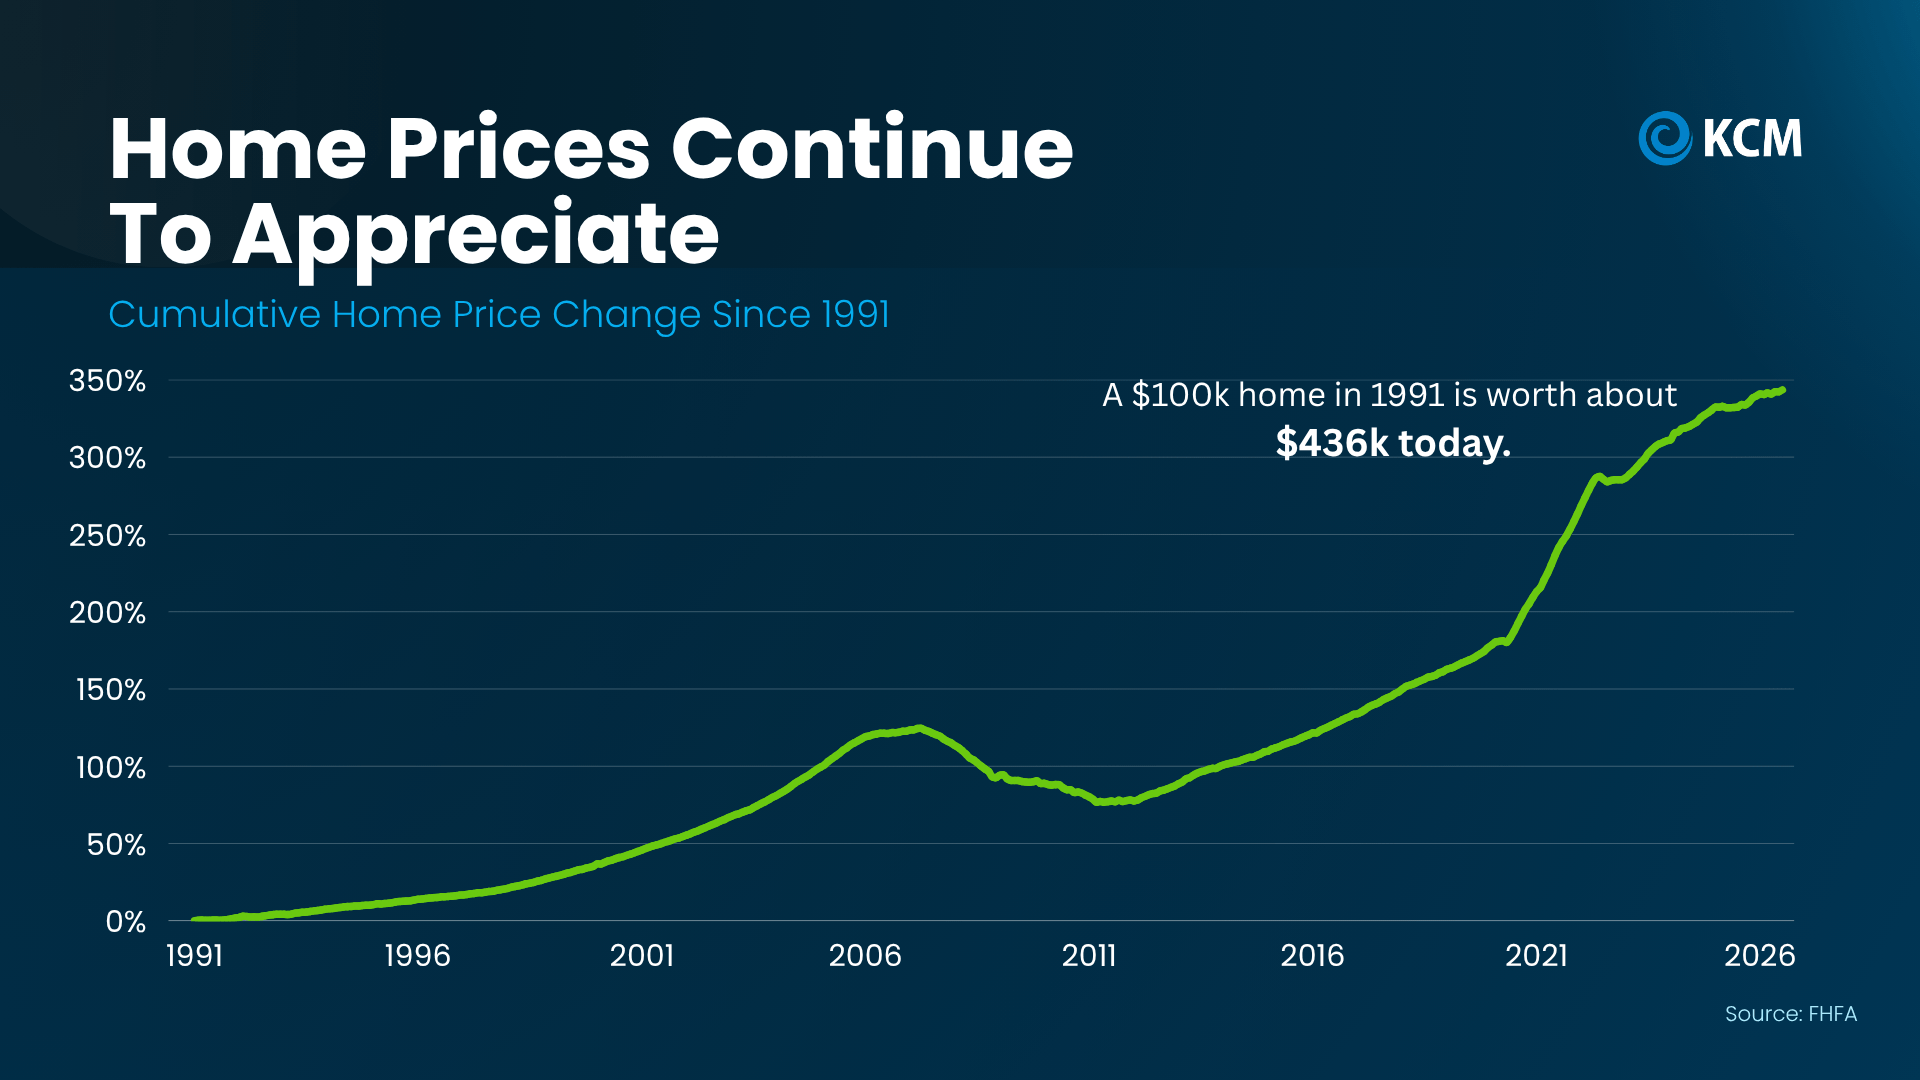
To Sell or Rent? How To Choose the Best Path for Your House.

To Sell or Rent? How To Choose the Best Path for Your House.
To Sell or Rent? How To Choose the Best Path for Your House. Simplifying The Market

Selling your house is a big step, and you want it to go smoothly. And with houses taking a little longer to sell these days, renting it out might start to sound like a nice backup plan.

But the reality is, while renting can work well for some people, it’s also a big commitment. So before you decide, it helps to see the whole picture first.

Why Some Sellers Are Deciding To Rent Instead

Lately, some sellers are choosing to hang on to their houses and rent them out instead. According to Parcl, around 9% of homes for rent right now were previously up for sale. 

Here’s why. 

Some homeowners put their houses on the market expecting a faster process than they got or a certain price buyers didn’t respond to. And when things didn’t go exactly as planned, they decided to rent instead. As Kara Ng, Senior Economist at Zillow, explains:

“Bargaining power is tilting toward buyers and homes are taking longer to sell, making renting out a property one way to buy time rather than compete aggressively on price.”

But here’s the important distinction. Just because some sellers are choosing to rent doesn’t mean selling isn’t working. In many cases, the difference comes down to how well a house is priced, prepared, and marketed for today’s buyers. 

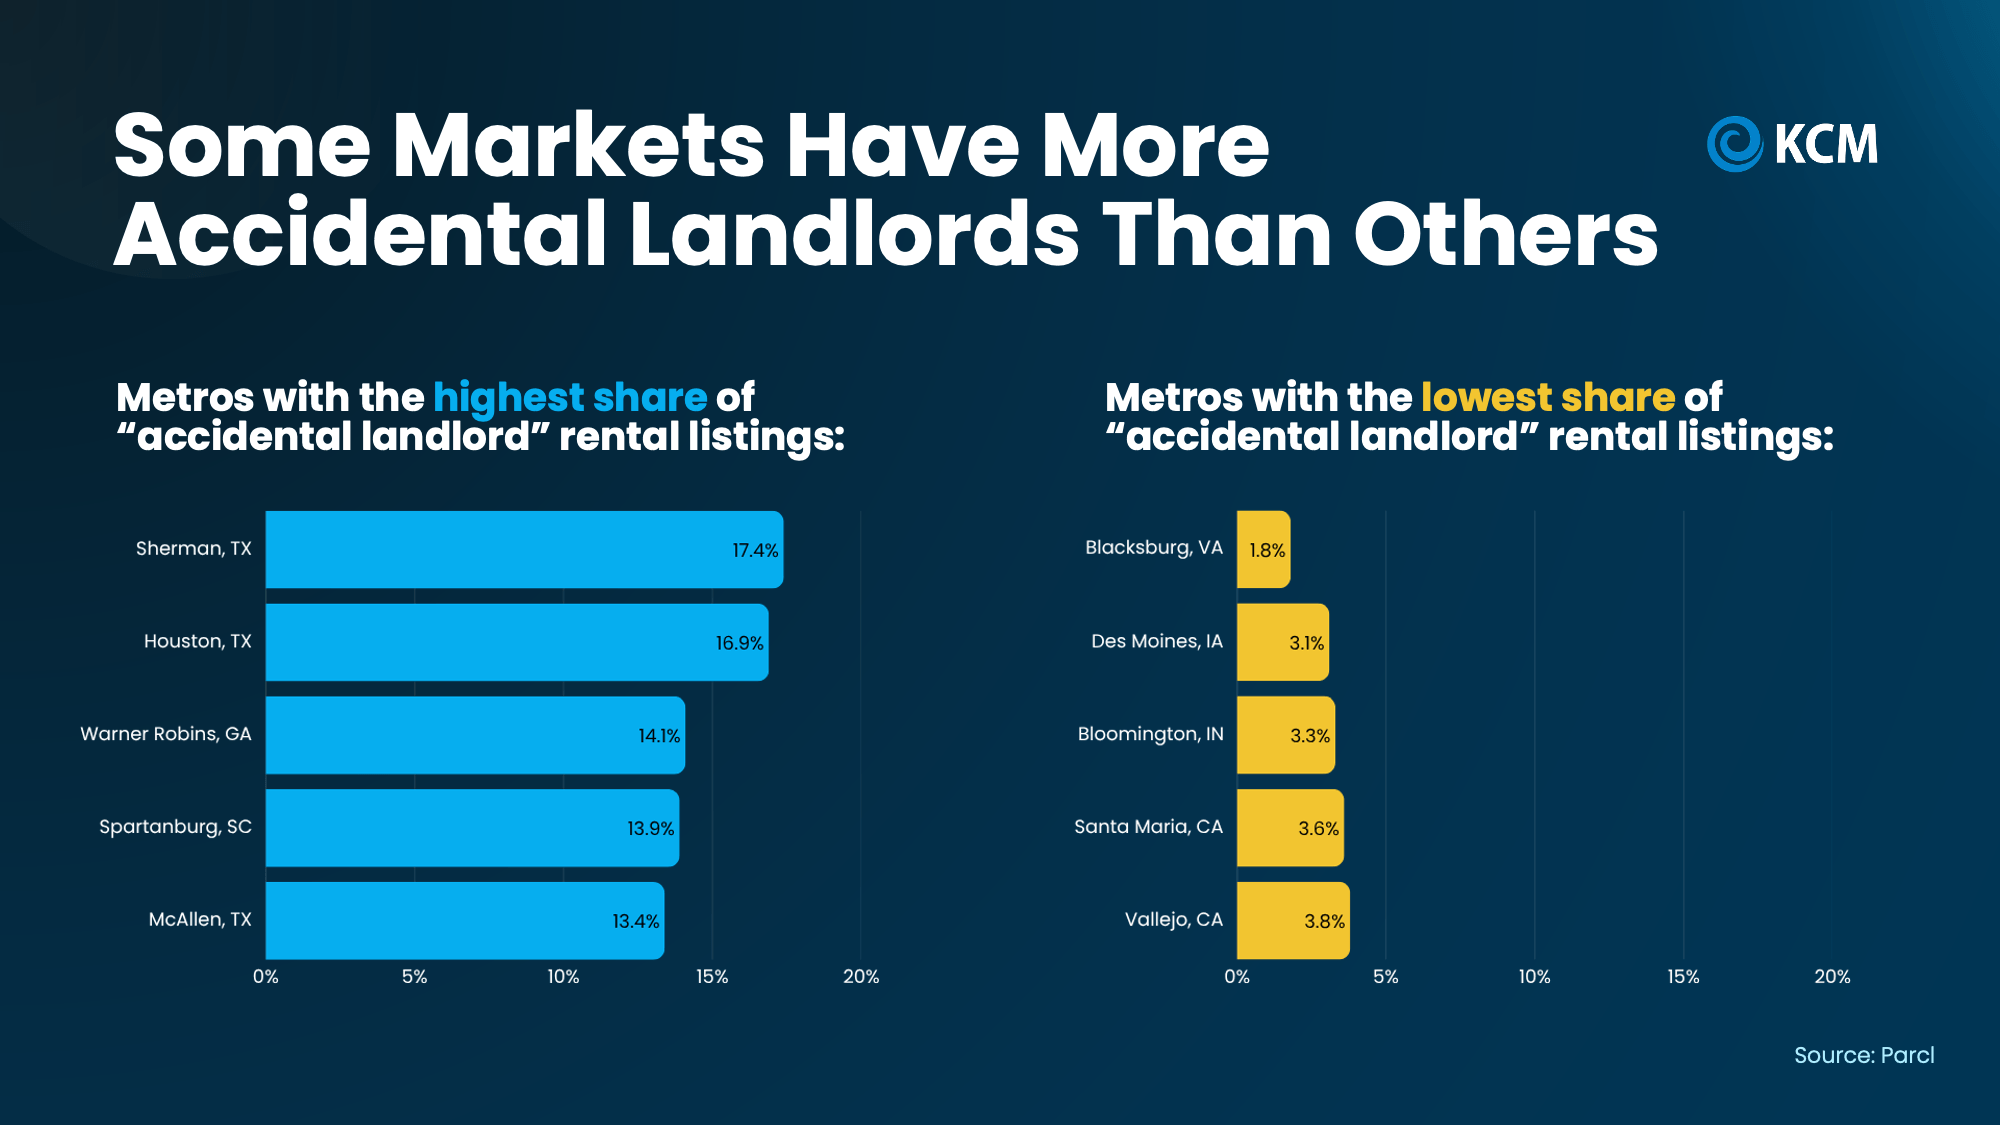
Parcl data shows where these “accidental landlords” – owners who planned to sell but decided to rent instead – are most common (see graph below):
a blue and yellow graph with white text

They make up around 17% of homes for rent in places like Sherman and Houston, TX, but less than 4% in markets like Des Moines, IA and Bloomington, IN. 

That’s a pretty big difference. And it shows why you have to know what’s happening in your neighborhood. Your market, your asking price, and your strategy all play a role in how your sale goes.

A local agent can show you how houses like yours are selling, what strategies work best, and help you weigh your options – not to push you to sell, but so you at least have the full picture based on today’s market. And part of making an informed decision is understanding what renting your house would actually take.

What Being a Landlord Actually Looks Like

While renting might sound like easy passive income on paper, in practice, it’s a hands-on job with rules to follow. As Invest West Management puts it:

“Even if you never intended to become a landlord, the law still sees you as one — and you must meet all legal obligations that come with that role. This often includes registering the tenancy, providing tenants with certain disclosures, and ensuring the property meets safety standards.”

You’d also be the one chasing missed rent payments, fixing damage between tenants, and covering unexpected repairs. Not to mention fielding weekend calls about leaky dishwashers or broken AC units. 

There are expenses beyond regular maintenance and repairs, too. According to Bankrate, these are a few of the biggest: 

  • Insurance premiums (landlord insurance typically costs about 25% more than a standard homeowners policy)

  • Management fees (if you hire a property manager, they usually charge around 10% of the rent) 

  • Gaps between tenants, when you pay the mortgage without rental income

How To Give Your House a Strong Start

If you want to be a landlord and you’re prepared for the responsibility, renting may be a great fit. But if you’d really rather sell, don’t let today’s market convince you that you can’t. 

A great agent can make it happen. The key is having an open conversation up front with your agent about pricing and how to market your house. Nailing those details from day 1 helps your house make a great first impression, so renting doesn’t have to be your fallback.

Bottom Line

Renting can be a good fit for the right person with the right house, but it isn’t the only option. A smart sales strategy can help your house stand out to buyers from day one.

So, if you’re on the fence, a local real estate agent can help you compare what selling and renting would each look like for you.
Confused by Home Price Headlines? Here’s Why.

Confused by Home Price Headlines? Here’s Why.

Confused by Home Price Headlines? Here’s Why. Simplifying The Market

Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.

One says home prices are falling. The next says they’re still climbing.

So, which one’s right? It comes down to where you live.

What’s Really Going on with Asking Prices

Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.

Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.

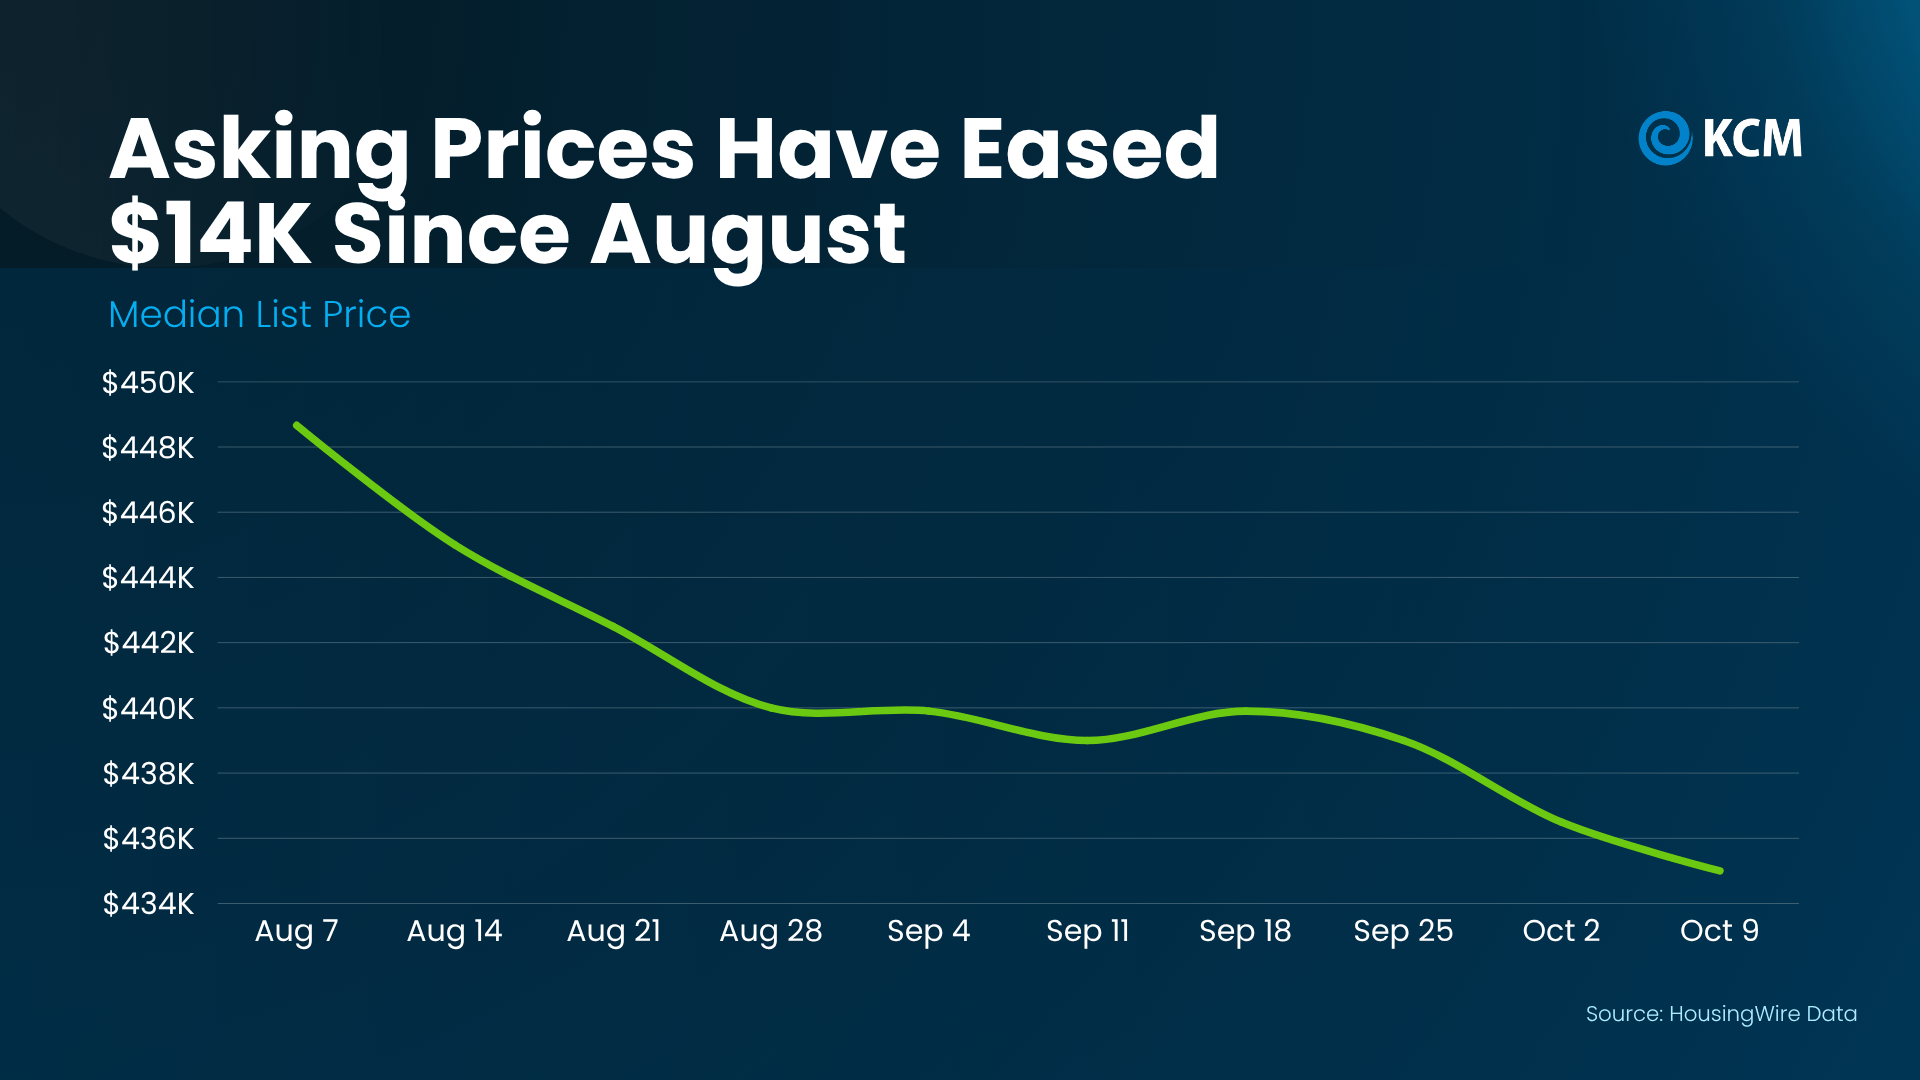
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):

a graph with green line

That’s a dip of about 3%, and a lot of it is normal for this time of year.

Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.

Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.

Where You Live Changes Everything

Realtor.com explains:

“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”

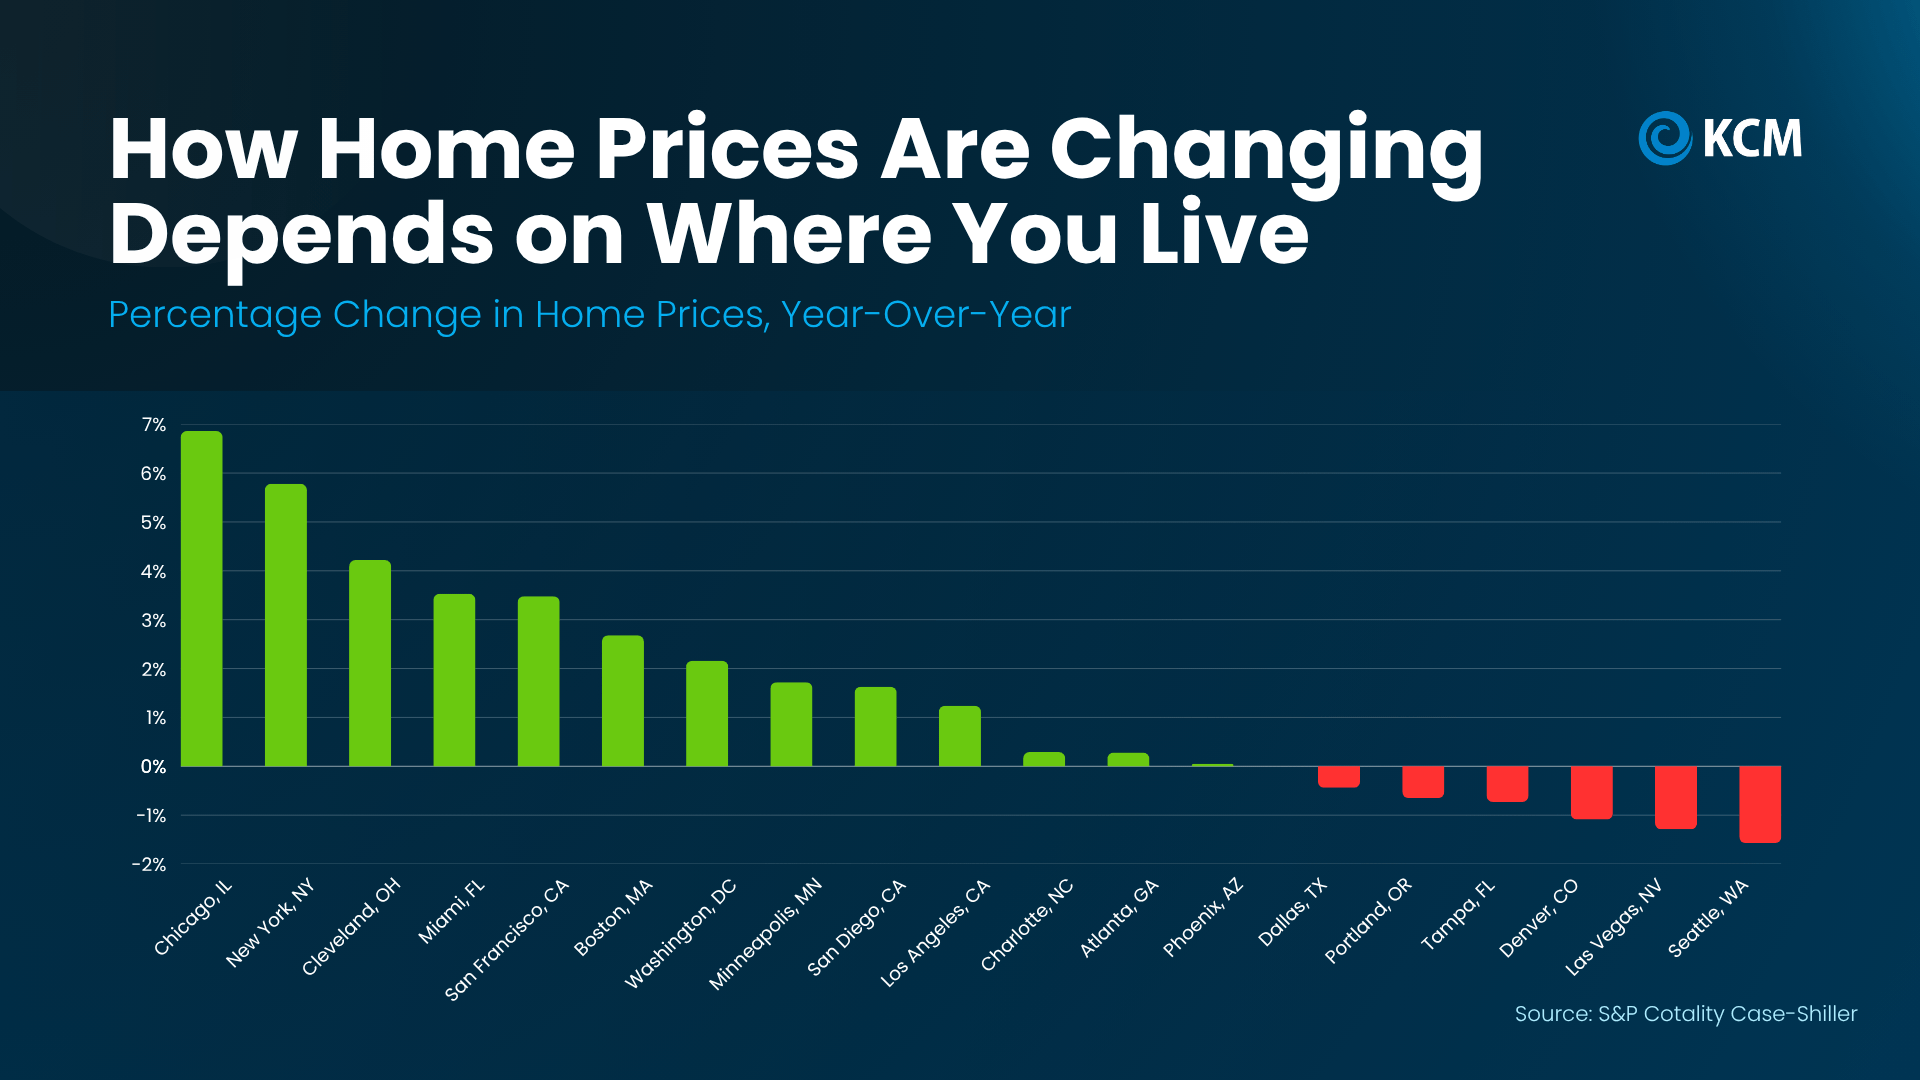
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):

a graph of a price

That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.

Why You Don’t Need To Worry About a Crash

Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.

And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):

a graph with a line going up

So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.

Bottom Line

National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, connect with a local real estate agent to look at how prices are moving in your area, so you can set your price or make your offer with confidence.

Homes Are Still Selling – Even in a Slower Market

Homes Are Still Selling – Even in a Slower Market

Homes Are Still Selling – Even in a Slower Market Simplifying The Market

If you’ve seen headlines saying home sales are slowing down, you may be wondering: is this really a good time to sell?

While the latest numbers show sales picked up slightly in September, they’re still down compared to last year. But here’s the perspective the headlines can miss.

Homes are still selling every single day. Because no matter what’s happening with mortgage rates or the economy, life keeps happening too. People get new jobs. Families grow. Relationships change. People retire, downsize, or need to move closer to the people they love. 

And those life changes create buyers and sellers in every market.

Just Look at the Math

According to the National Association of Realtors (NAR), based on the current pace homeowners are expected to sell almost 4 million homes this year. Break that down, and that’s roughly:

  • 11,000 homes every day.

  • 450 homes every hour.

  • 8 homes every minute.

So, yes, the market may be moving at a slower pace than it has at other points in time. But slower doesn’t mean it’s stopped. As Hannah Jones, Senior Economic Research Analyst at Realtor.com, says:

“Even in today’s high-price, high-rate market, homebuying activity around major life events, such as having kids, a job change, or a divorce, keeps the market in motion.”

Thousands of buyers are still making moves every day. The key is making sure your house is positioned to get their attention.

What That Means for Your Sale

Today’s buyers have more choices, so they can afford to be more selective about things like price and condition. That makes having the right strategy from the start especially important.

Because you don’t need every buyer to be looking for a home like yours. You just need the right one – and to know how to get in front of that buyer.

Bottom Line

Don’t let a headline about slowing home sales convince you no one is buying. Homes are still selling every minute of every day.

If you need or want to move, talk to an agent about what it’ll take to make sure yours is one of them.

Why There are More Homes for Sale Right Now (and What It Means for You)

Why There are More Homes for Sale Right Now (and What It Means for You)

Why There are More Homes for Sale Right Now (and What It Means for You) Simplifying The Market

Mortgage rates being back above 7% isn’t exactly the news most people wanted. But it’s changing the market in ways that matter whether you’re buying or selling.

The number of homes for sale is growing faster than it was this time last year. And interestingly, the main reason isn’t a flood of new listings. It’s because homes aren’t selling as quickly.

Here’s why – and what that means if you’re thinking about buying or selling.

Inventory Growth Is Picking Up Steam

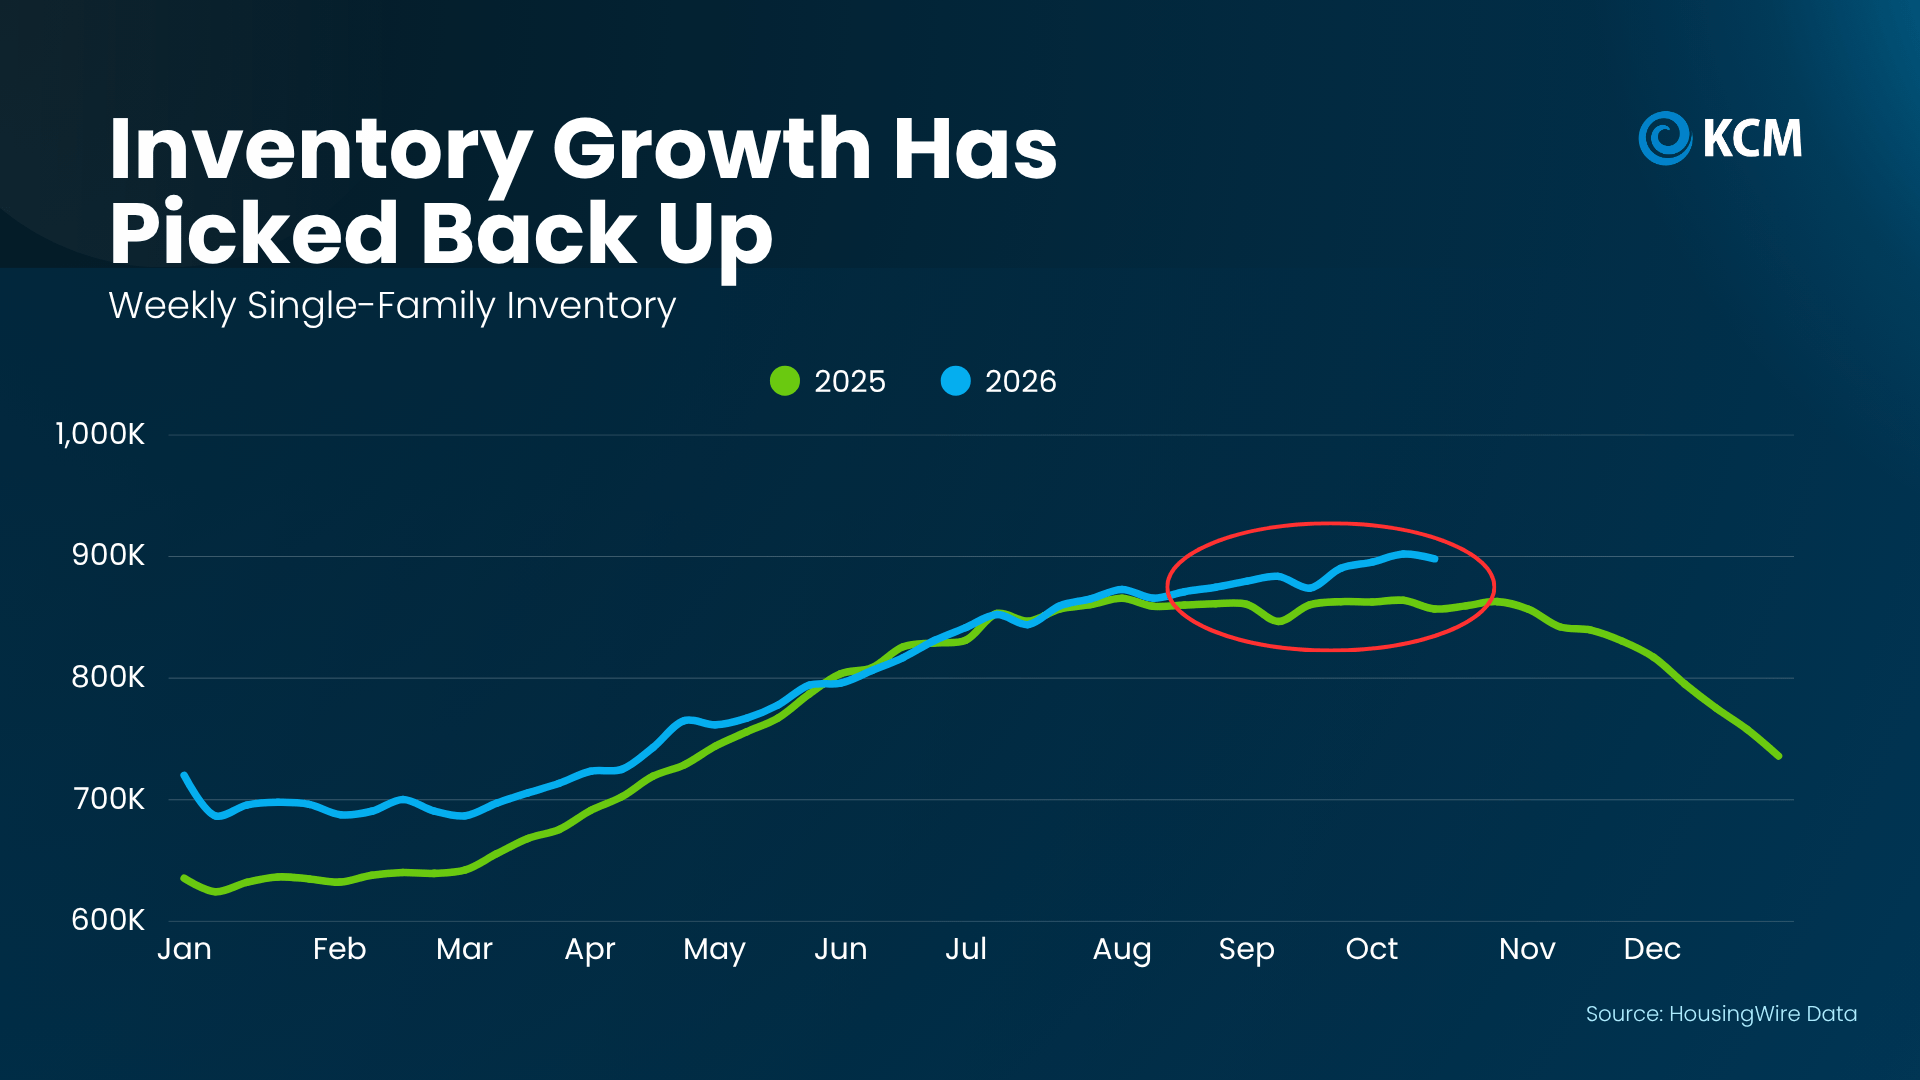
According to HousingWire Data, after inventory growth slowed down for most of the past year, it’s accelerated again in recent weeks. You can see that in the graph below. Just look at the blue line:

a graph of growth and growth

And what’s behind this shift might surprise you.

When rates rise, some buyers hit pause. That means fewer homes sell each week. And as those unsold homes stay on the market alongside new listings, the number available starts to grow (see the blue line in the graph below).

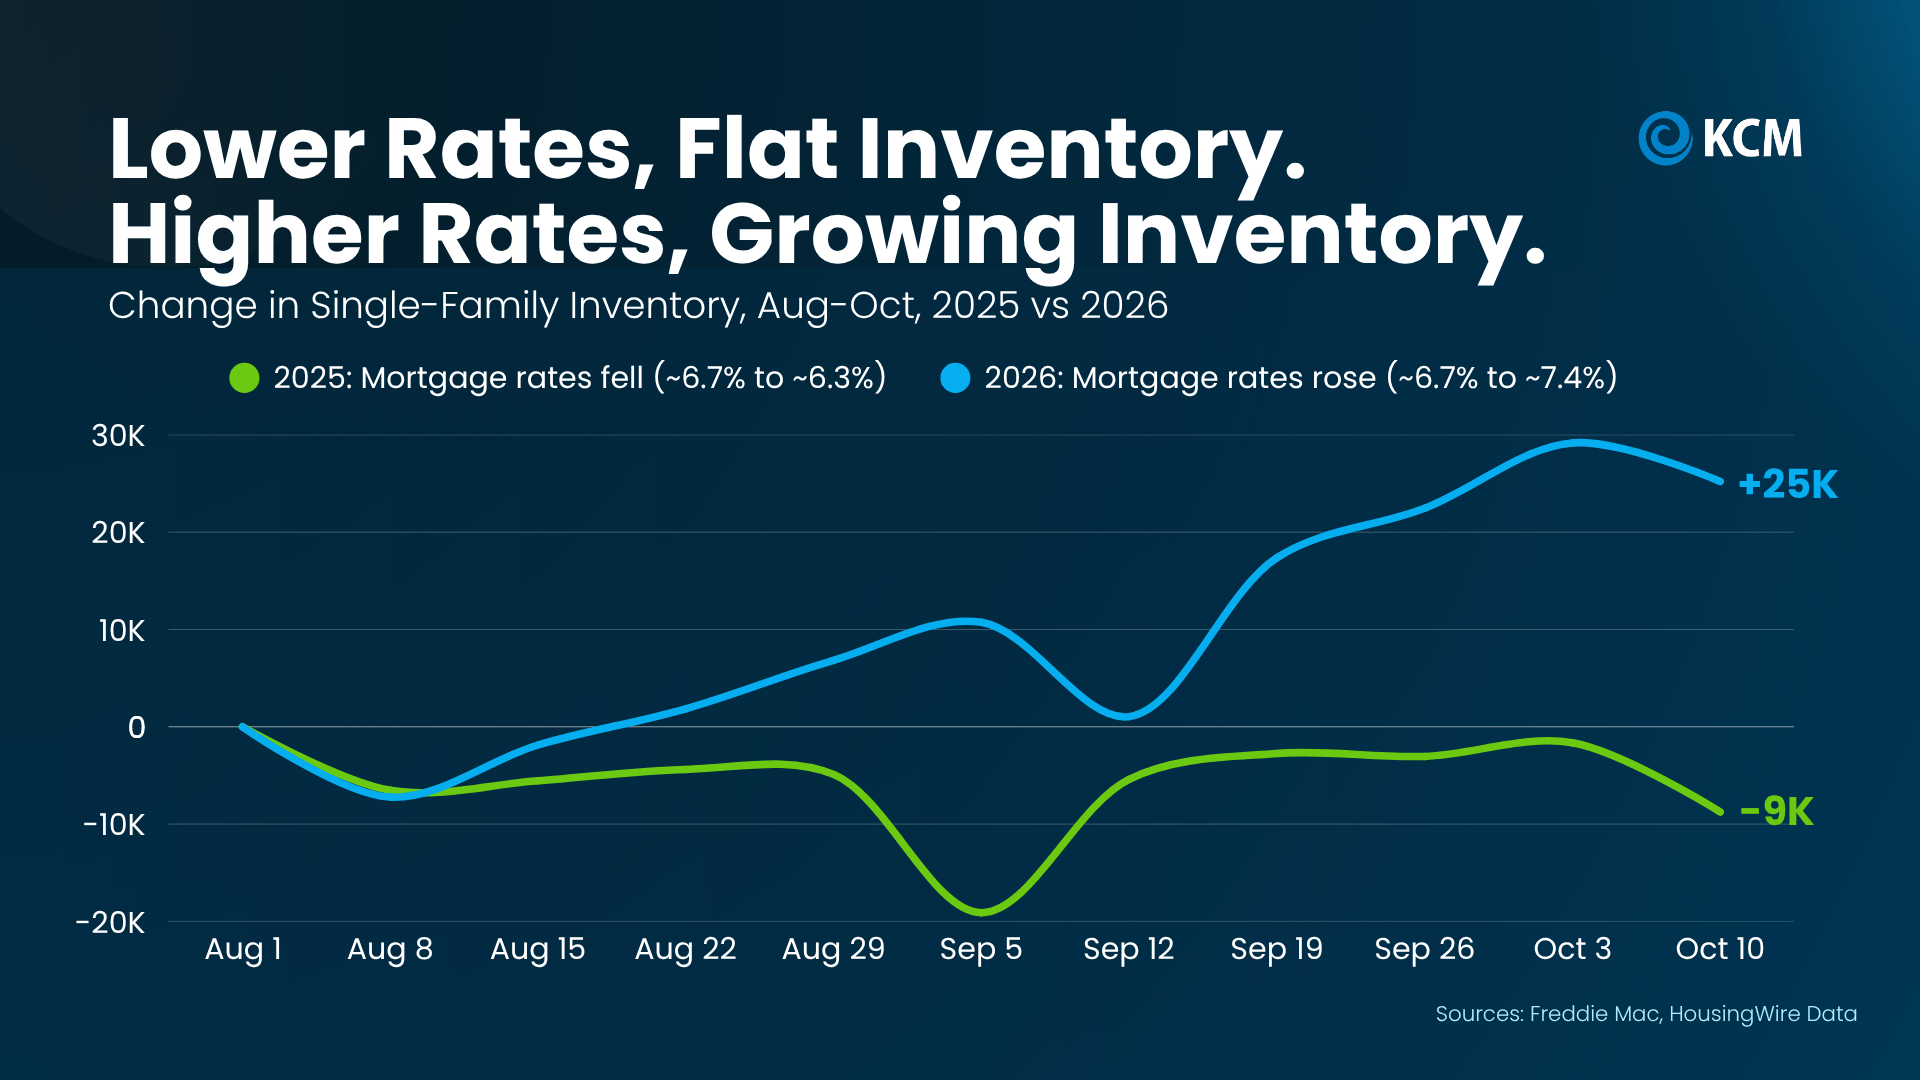
Here’s another way to look at it to make it even more obvious. The graph below shows the relationship between rates and inventory. Again, this year is the blue line. Last year? That’s the green.

With rates inching up this year, you can see inventory has grown by about 25k. But when rates went down this time last year, buyers jumped back in, and inventory actually dropped by about 9k.

a graph of growth and growth of a mortgage

Logan Mohtashami, Lead Analyst at HousingWire, explains how that’s flipped from 2025 to 2026:

“With mortgage rates over 7%, demand tends to soften and inventory rises . . .”

Homes Are Spending More Time on the Market

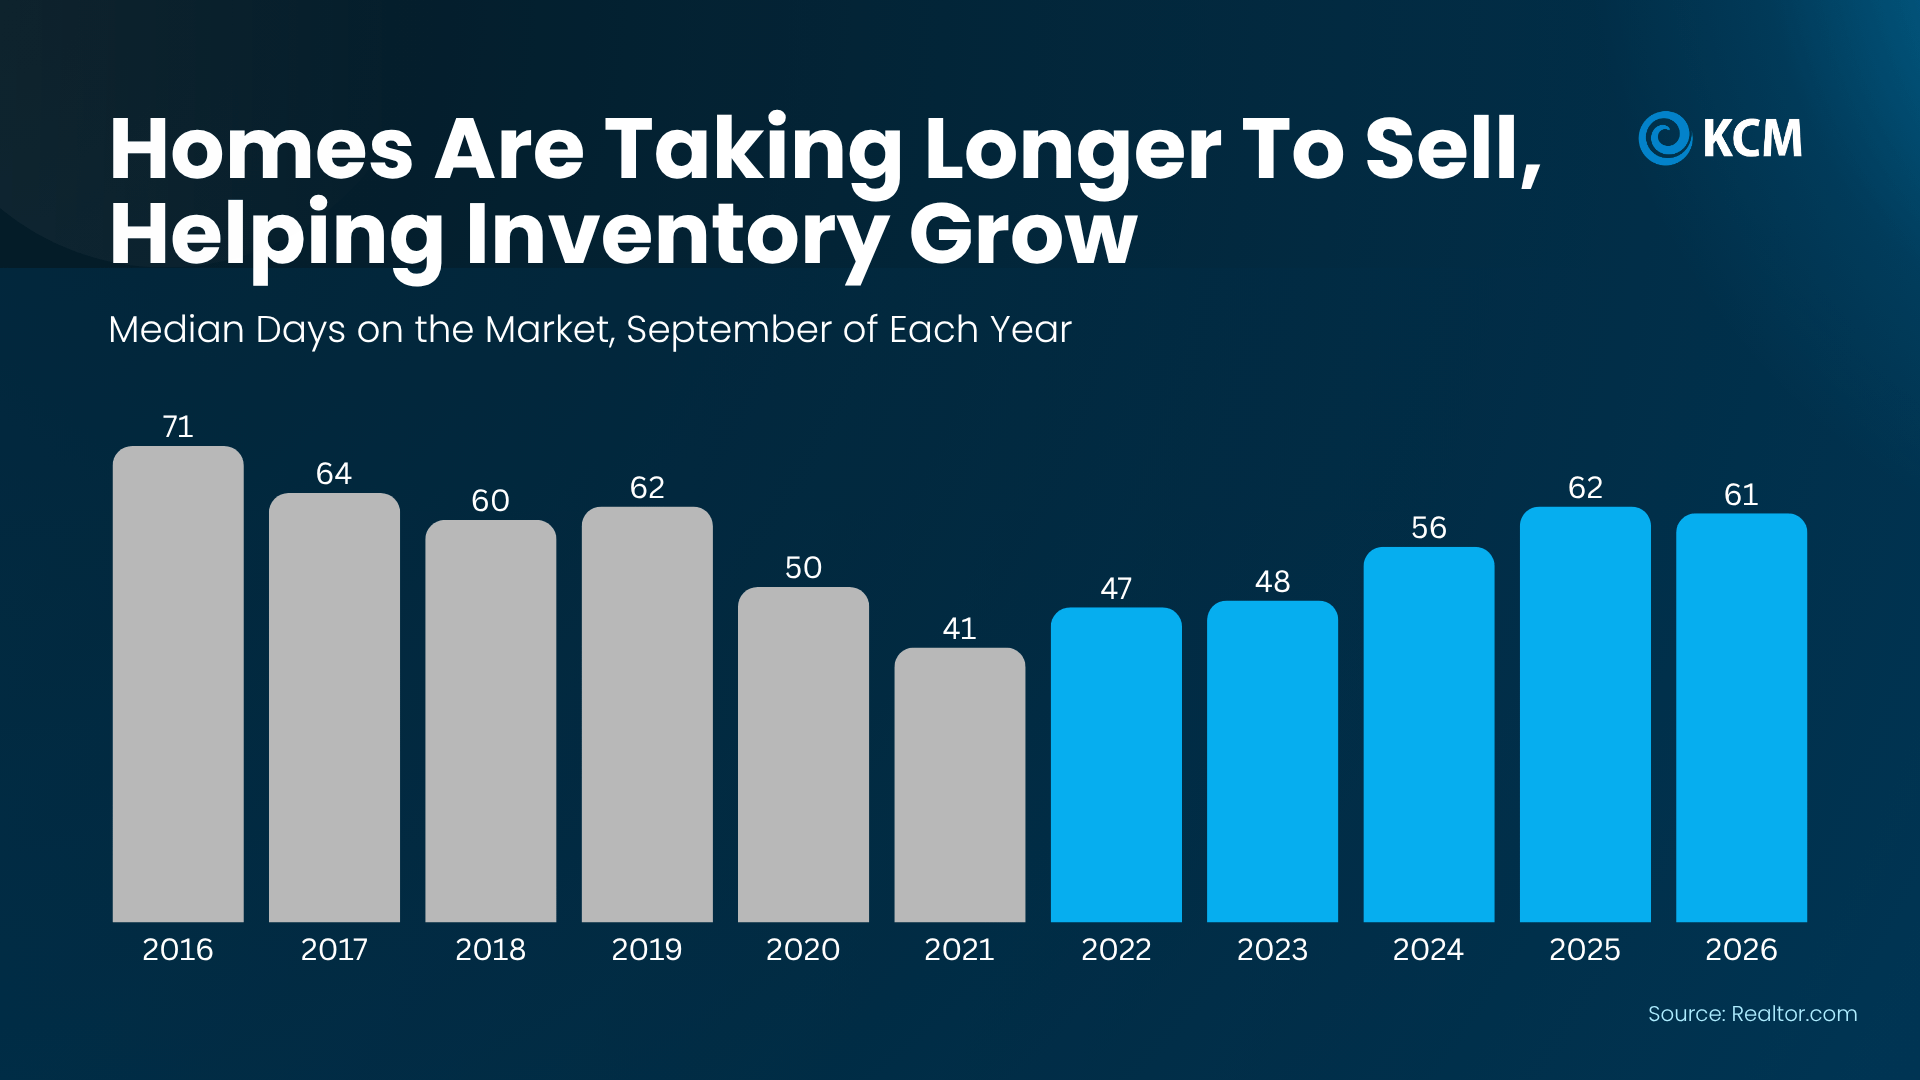
Here’s another metric that shows the impact rates are having: time on market. Data from Realtor.com shows the typical home spent 61 days on the market this September. Back in September 2021, it was just 41 days (see graph below):

a graph of sales growth

Here’s what that tells us. In 2021, when rates were low, more buyers were active, and homes sold fast. But now that rates are a bit higher, not as many buyers are interested, so it takes a bit longer to close a deal.

How To Make This Market Work for You

So, what does all of this mean for your plans? That depends on which side of the move you’re on:

If you’re buying, more homes for sale means more choices and less pressure to rush. And more room to negotiate too. A house that’s been sitting for a while could have a seller who’s more willing to talk – not just about price, but repairs, closing costs, or even helping buy down your mortgage rate.

That doesn’t mean every seller will play ball. But compared to the frenzy of a few years ago, buyers have more leverage now.

If you’re selling, the right strategy can make all the difference. Buyers have more homes to choose from, so making yours stand out is especially important. That starts with pricing it right from day one, making a great first impression, and working with your agent to highlight what makes your house worth choosing. Buyers are still buying and homes are still selling. The key is making sure yours is positioned to attract the right buyer.

The market hasn’t stopped. It’s just moving at a different pace. And whether you’re buying or selling, your strategy needs to move with it.

Bottom Line

In many places right now, inventory is growing and homes are taking a bit longer to sell. And that’s information that should shape the strategy you use going in.

Whether you’re buying or selling, connect with a local real estate agent to look at how long homes are taking to sell in your neighborhood, so your offer, or your price, fits today’s market.

Renovate or Relocate? What To Know Before You Decide To Age in Place

Renovate or Relocate? What To Know Before You Decide To Age in Place

Renovate or Relocate? What To Know Before You Decide To Age in Place Simplifying The Market

You’ve spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it’s natural to wonder if this is still the place you want to spend it.

Whether you’re leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here’s what to consider before you decide.

What It Can Take To Stay Put

Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier.

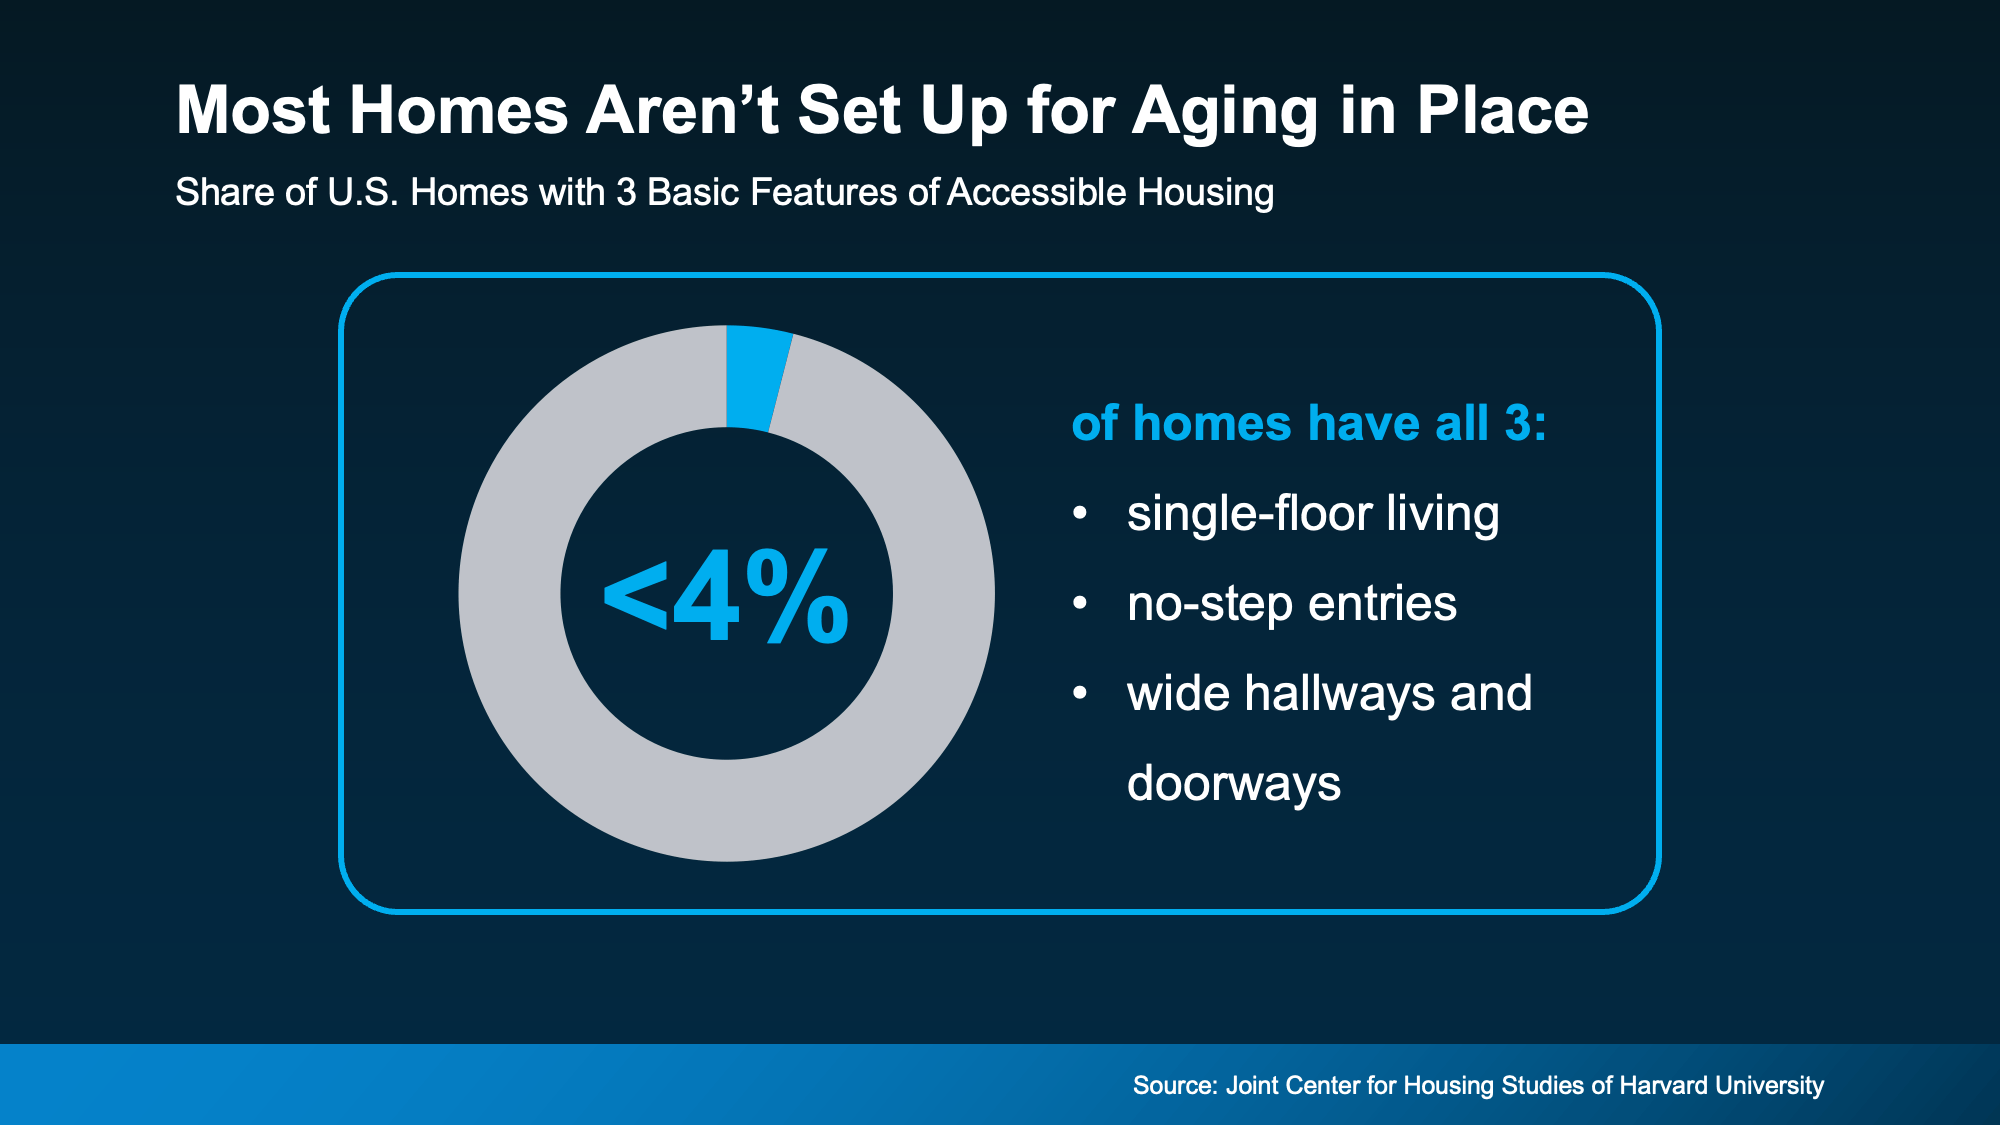
In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below):

a diagram of a pie chart

That means for most homeowners, staying put means doing a remodel.

The National Association of Home Builders (NAHB) reports more than half of remodelers (56%) take on this kind of work. Some of the most common projects are installing grab bars, curb-less showers (walk-in showers with no ledge to step over), and wider doorways.

Now, that’s not to say you can’t go this route. You most certainly can. But if this is how you’re leaning just know you’d be living with contractor noise and dust until the work gets done. Some people don’t want to live in a construction zone. Not to mention, having to manage the contractors and schedules, etc.

Your Equity Could Pay for Your Next Move

If that sounds like something you’d rather avoid, here’s the good news. The money for your next home may already be sitting in your current one. It’s called equity, which is the difference between what your house is worth and what you still owe on it. After years of mortgage payments and rising home values, it adds up. Jess Catorc, Co-Founder of Carry, explains:

“The way home equity builds and is used changes a lot depending on your stage of life. . . . For older homeowners, decades of mortgage payments and home-value growth can turn equity into a financial cushion.“

When you sell, that cushion can go toward a home that’s ready for this stage of life. No demo required. You just get the keys and it’s all there, ready for you. That means less time on projects and more time for living. And one option you may consider if you’re entertaining a move is a 55+ plus community.

Why 55+ Communities Are Worth a Look 

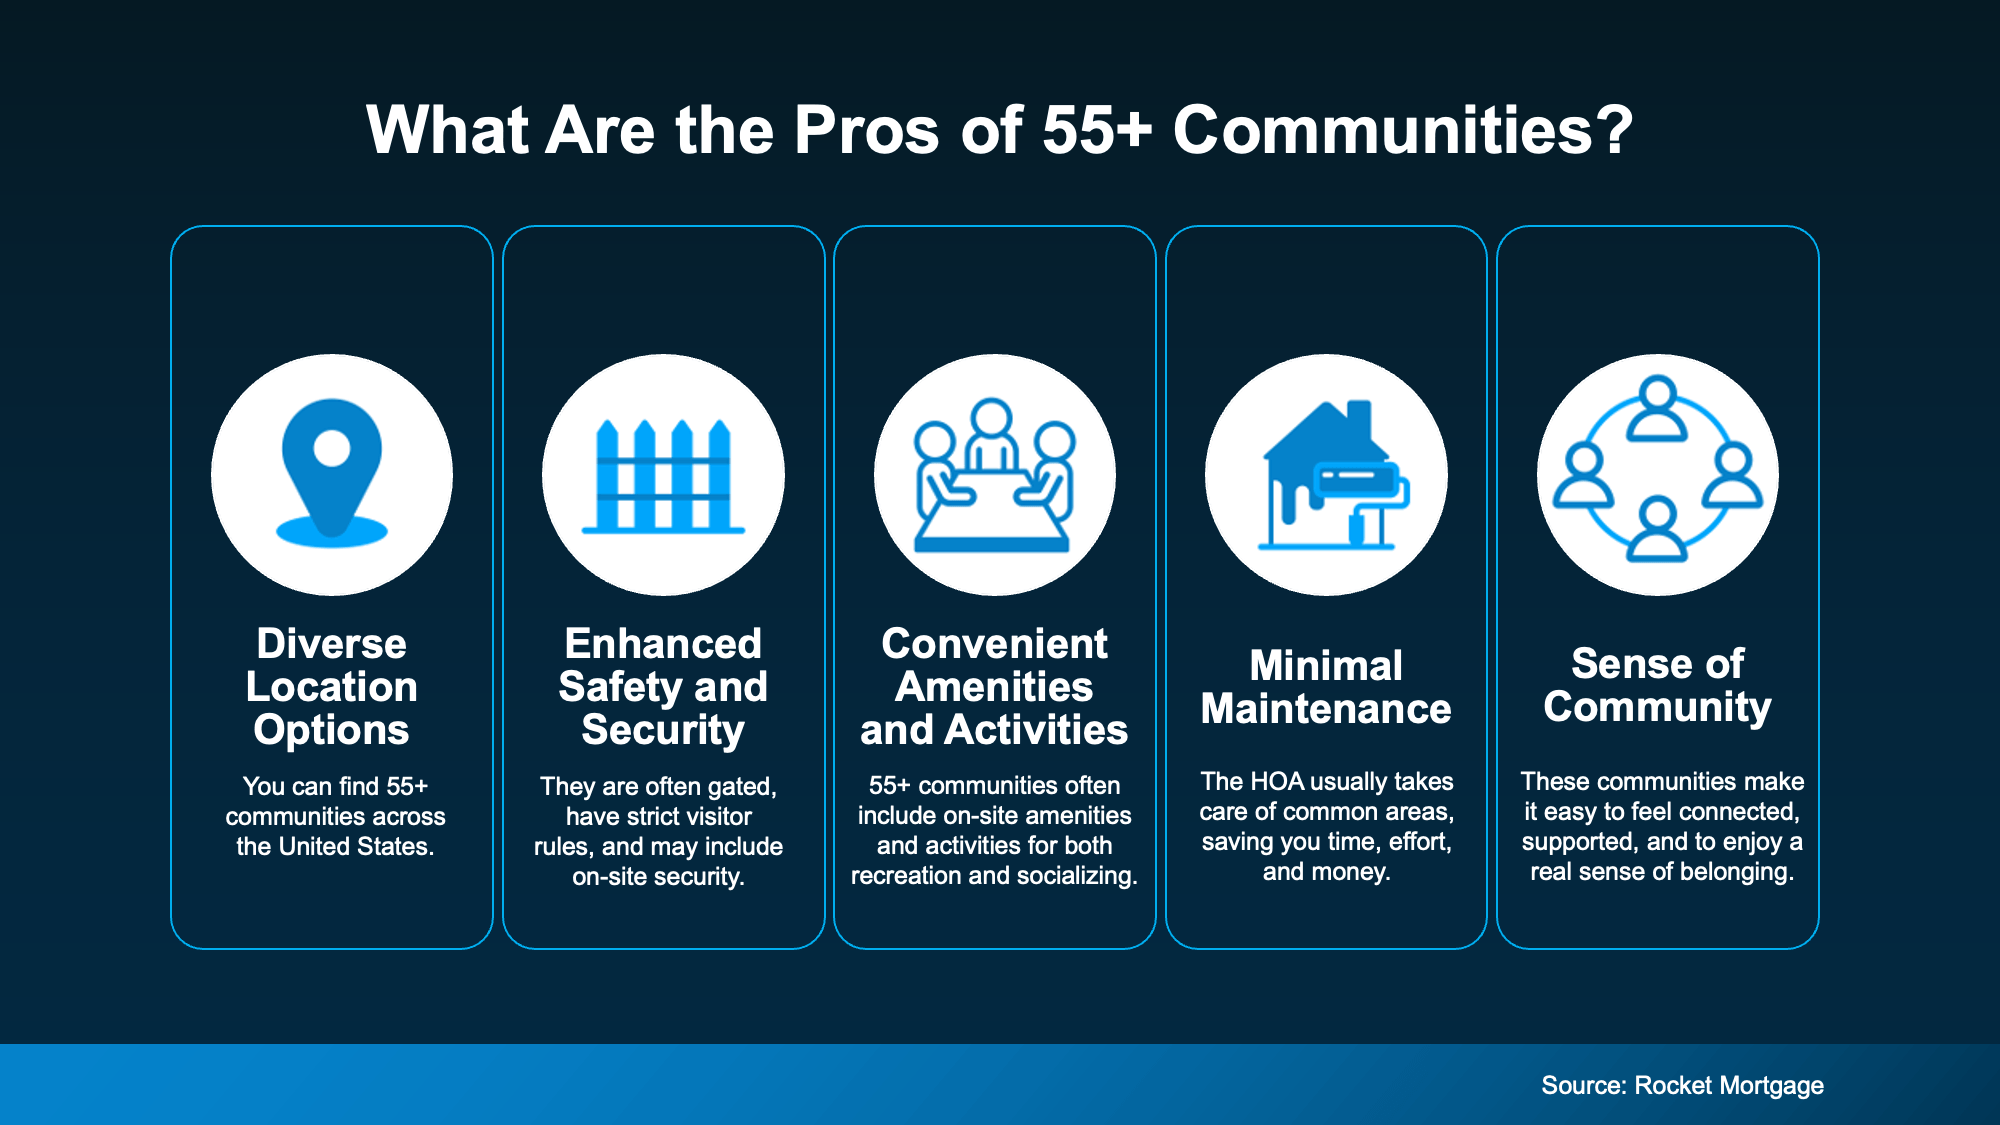
From the homes to the shared spaces to the activity calendar, these communities are planned around this stage of life. And that means everything you need is already rolled into one place. Rocket Mortgage lists some of the biggest perks (see visual below):

a blue and white diagram with white text

Instead of spending time and money to make your house easier to live in, you’d move into a community that’s designed with that in mind from the jump. That frees you up for the good stuff, like a morning walk with a neighbor, a game night down the street, or finally trying the hobby you’ve been putting off.

Bottom Line

Staying and moving can both be good choices. What matters most is finding the place where you’ll feel comfortable and at home for years to come.

A local real estate agent can help you weigh the two by showing you what your house could sell for and what 55+ communities in your area have to offer, so you can decide what feels right for you.

Myth vs. Reality: Does the Fed Control Mortgage Rates?

Myth vs. Reality: Does the Fed Control Mortgage Rates?

Myth vs. Reality: Does the Fed Control Mortgage Rates? Simplifying The Market

You’ve probably heard the Federal Reserve (the Fed) is raising rates again. And if you’re planning to buy or sell a house, you may be wondering what that means for you.

With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.

So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.

Why the Fed Is Raising Rates

It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.

So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.

  • MYTH: The Fed controls mortgage rates.

  • REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.

As NerdWallet explains:

“The Federal Reserve influences mortgage rates, but doesn’t set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve’s monetary policy is a factor, too . . .”

Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.

Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.

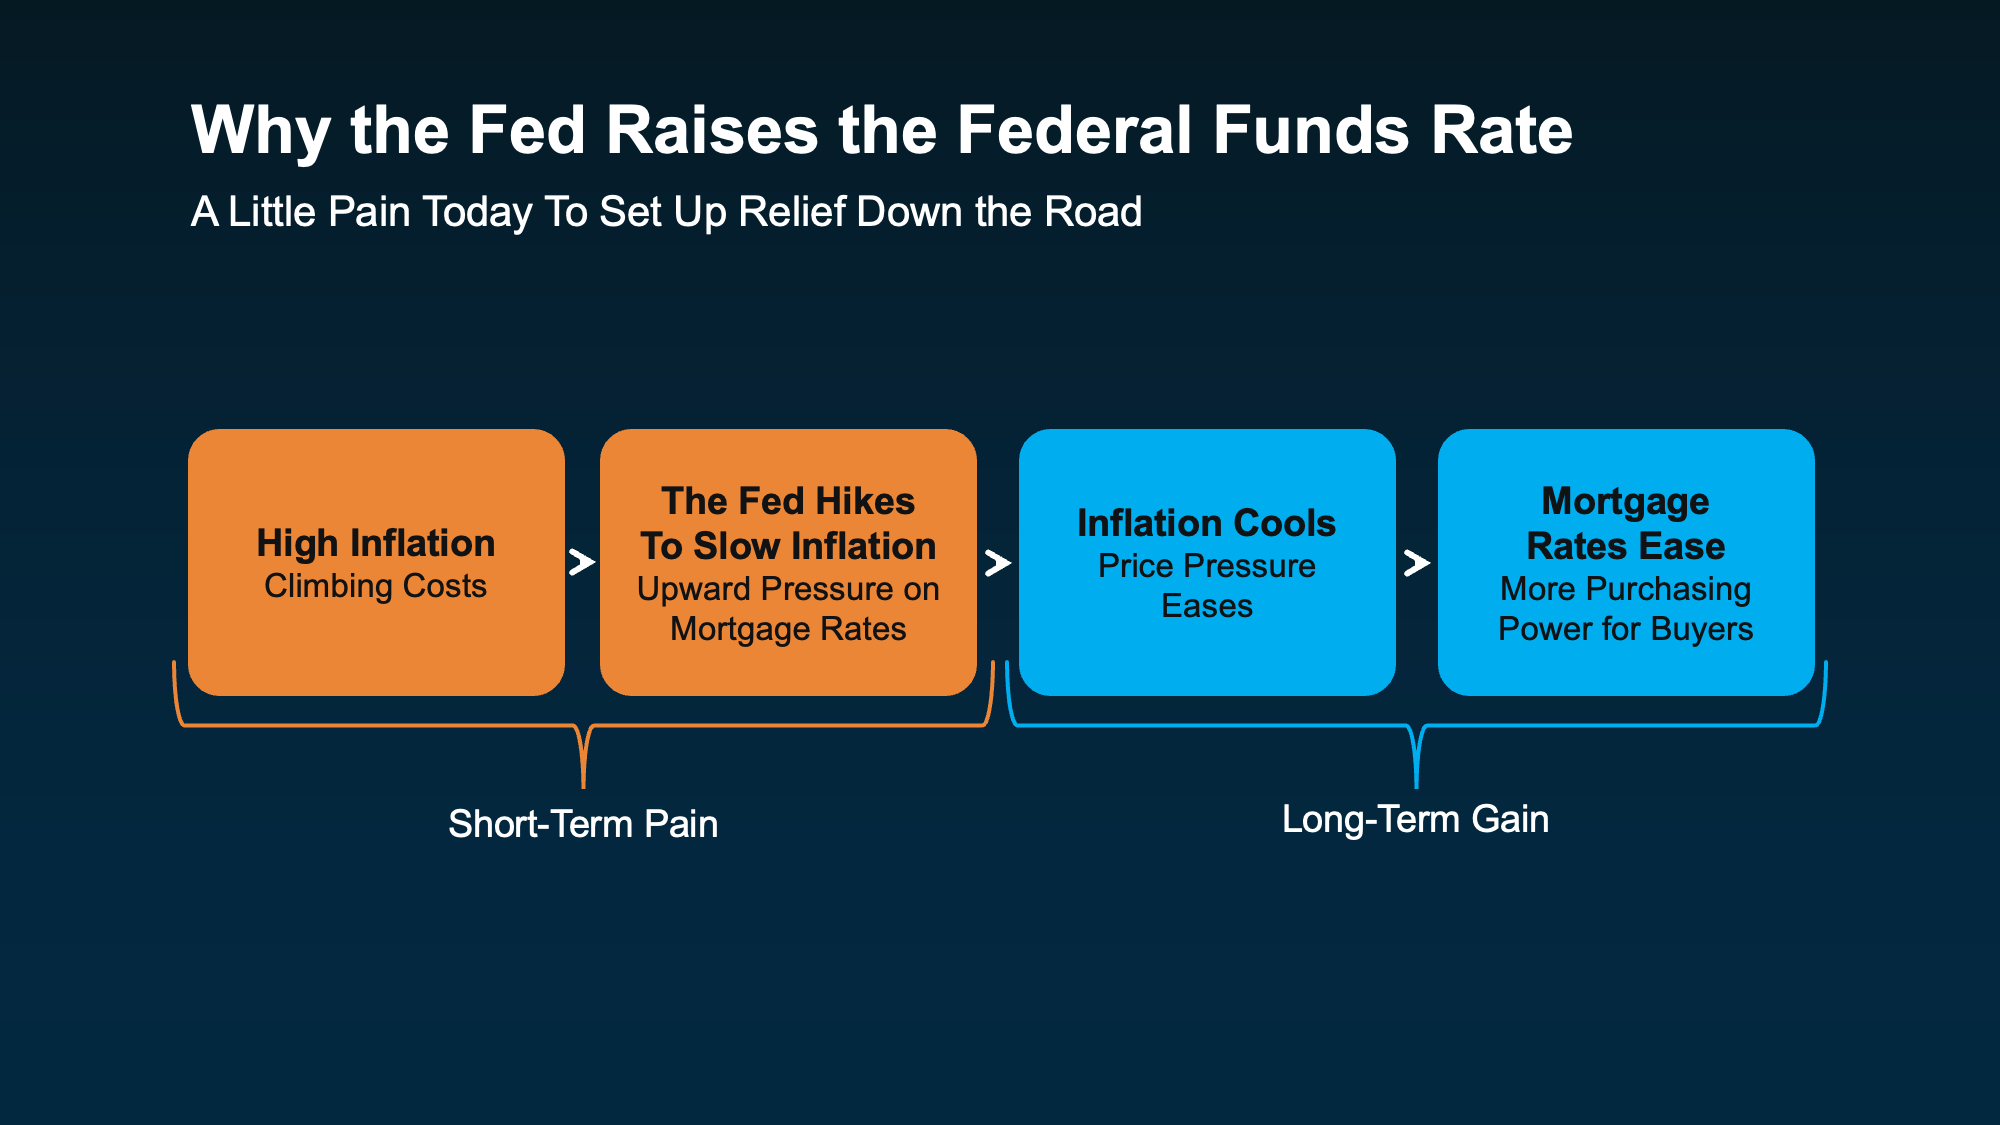
What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):

a diagram of a federal funds rate

Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.

There’s a Strong Possibility the Fed Will Hike Again This Year

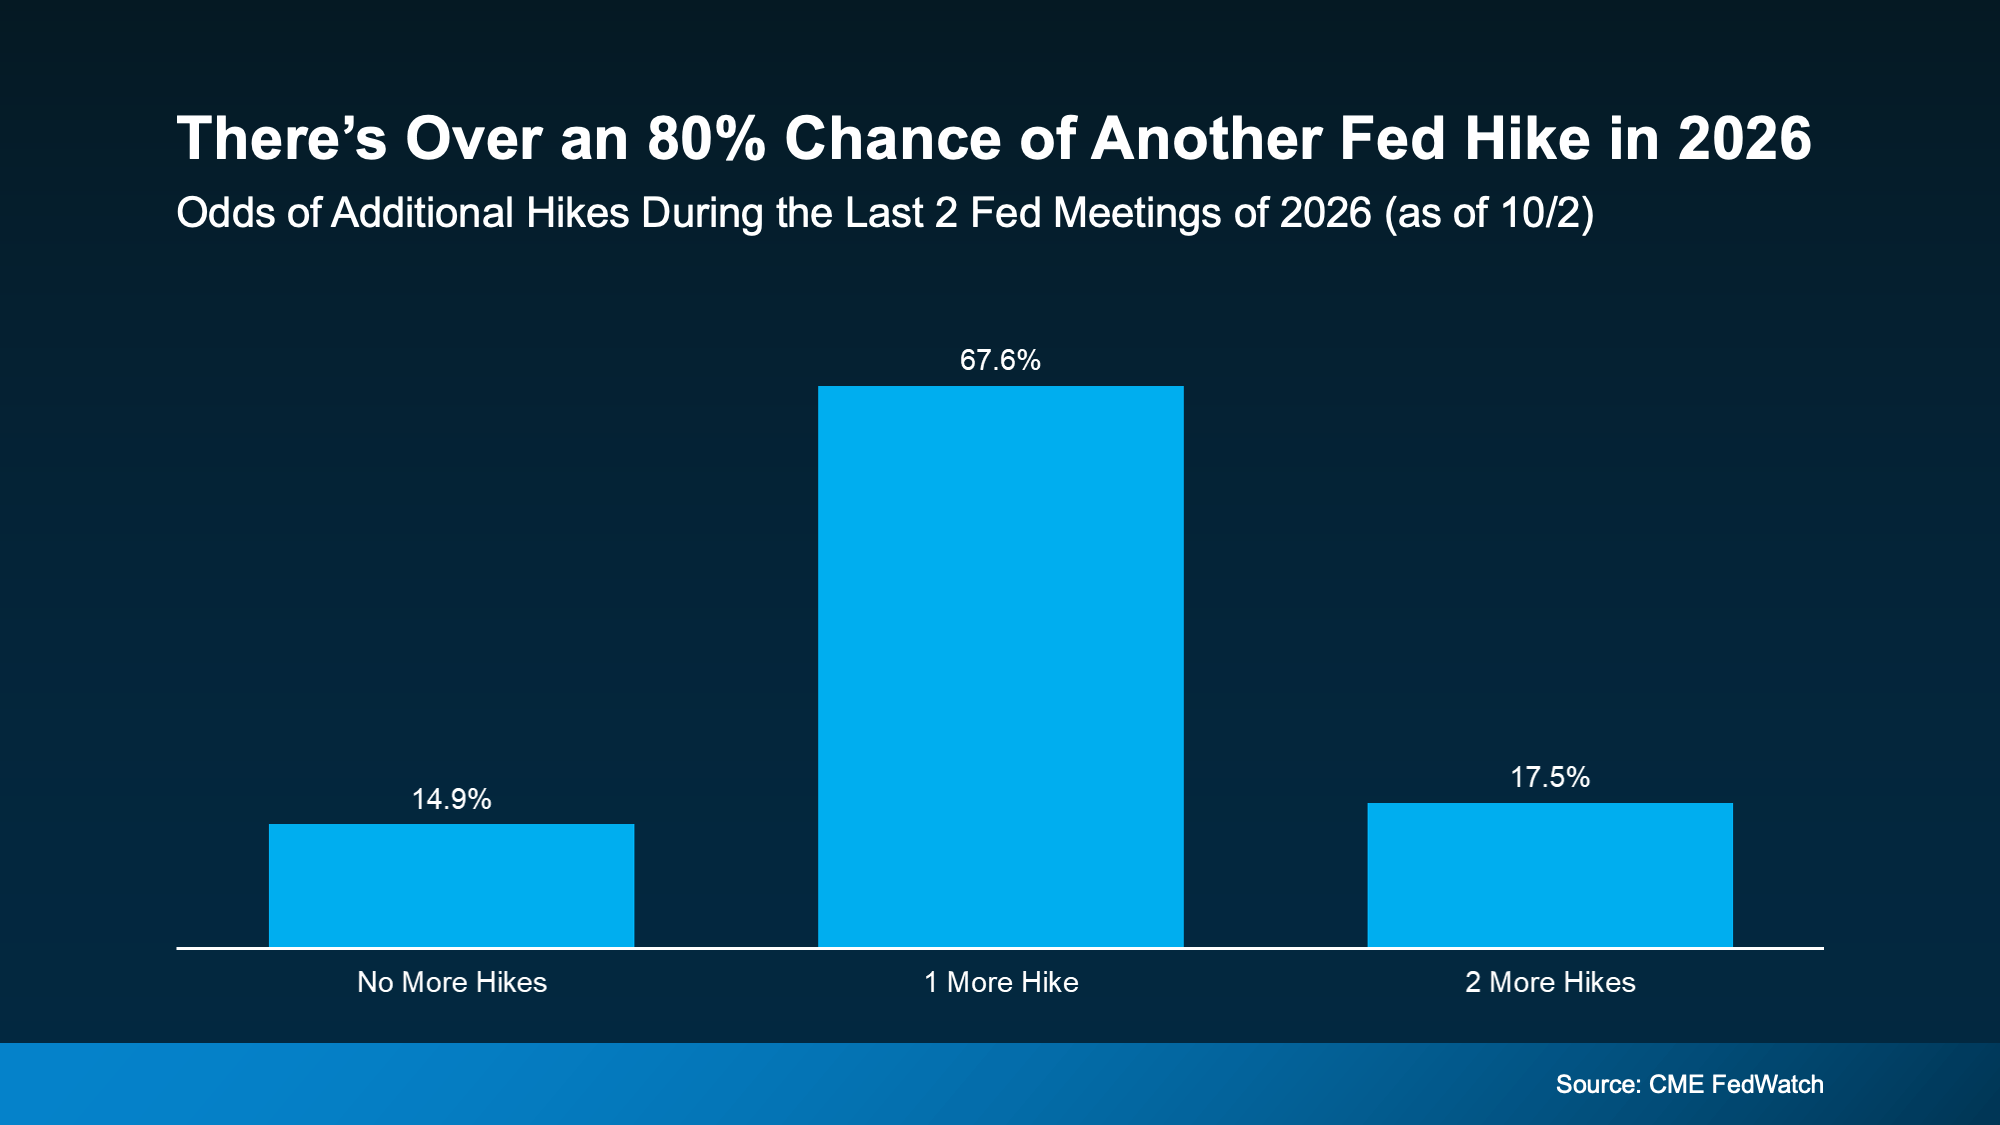
According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):

a graph of hikers with blue squares

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:

“Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control.“

And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:

  • PCE inflation dropped to 3.4%, down from 3.7% in July.

  • Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.

That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.

How To Make Your Move Work Right Now

While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.

  • If you’re buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you’re under contract, lock your rate so a jump before closing doesn’t raise your payment.

  • If you’re selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today’s buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.

Bottom Line

The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today’s rates.

Pin It on Pinterest