Selling and Buying at the Same Time? Here’s What You Need To Know

Selling and Buying at the Same Time? Here’s What You Need To Know
Selling and Buying at the Same Time? Here’s What You Need To Know  Simplifying The Market

If you’re a homeowner planning to move, you’re probably wondering what the process is going to look like and what you should tackle first:

  • Is it better to start by finding your next home?
  • Or should you sell your current house before you go out looking?

Ultimately, what’s right for you depends on a lot of factors. And that’s where an agent’s experience can really help make your next step clear.

They know your local market, the latest trends, and what’s working for other homeowners right now. And they’ll be able to make a recommendation based on their expertise and your needs.

But here’s a little bit of a sneak peek. In many cases today, getting your current home on the market first can put you in a better spot. Here’s why that order tends to work best (and how an agent can help).

The Advantages of Selling First

1. You’ll Unlock Your Home Equity

Selling your current home before you try to buy your next one allows you to access the equity you’ve built up – and based on home price appreciation over the past few years, that’s no small number. Data from Cotality (formerly CoreLogic) shows the average homeowner is sitting on $302K in equity today.

And once you sell, you can use that equity to pay for the down payment on your next house (and maybe even more). You could even have enough to buy your next house in cash. That’s a big deal, and it could make your next move a whole lot easier on your wallet.

2. You Won’t Be Juggling Two Mortgages

Trying to buy before you sell means you could wind up holding two mortgages, even if just for a few months. That can get expensive, fast – especially if there are unexpected repairs or delays. Selling first removes that stress and helps you move forward without the financial strain. As Ramsey Solutions says:

“It’s best to sell your old home before buying a new one to avoid unnecessary risks and possible headaches.”

3. You’ll Be in a Stronger Position When You Make an Offer

Sellers love a clean, simple offer. If you’ve already sold your house, you don’t need to make your offer contingent on that sale – and that can help you stand out. Your agent can position your offer to be as strong as possible, so you have the best shot at getting the home you want.

This can be a big advantage in competitive markets where sellers prefer buyers with fewer strings attached.

One Thing To Keep in Mind

But, like with anything in life, there are tradeoffs. As you weigh your options, consider this potential drawback, too:

1. You May Need a Place To Stay (Temporarily)

Once your house sells, you may need a short-term rental or to stay with family until you can move into your next home. Your agent can help you negotiate things like a post-closing occupancy (renting the home from the buyer for a set period) or flexible closing dates to help smooth out that transition as much as possible.

Here’s a simple visual that can help you think through your options (see below):
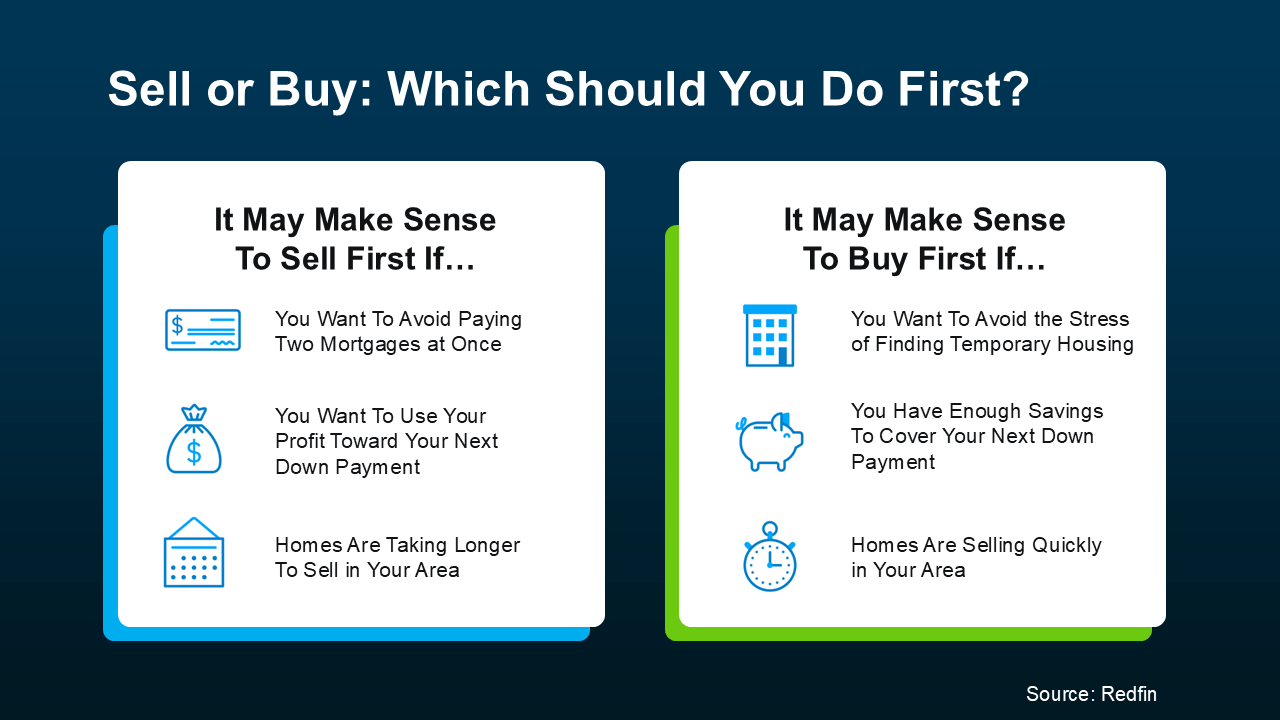
But the best way to determine what’s best for you and your specific situation? Talk to a trusted local agent.

Bottom Line

In many cases, selling first doesn’t just give you clarity, it gives you options. It helps you buy with more confidence, more financial power, and less pressure.

If you’re ready to make a move but not sure where to begin, talk to a local agent. They’ll walk you through your equity, your timing, and your local market so you can decide what’s right for you.

Should You Buy a Vacation Home?

Should You Buy a Vacation Home?

Should You Buy a Vacation Home? Simplifying The Market

a screenshot of a cellphone

Some Highlights

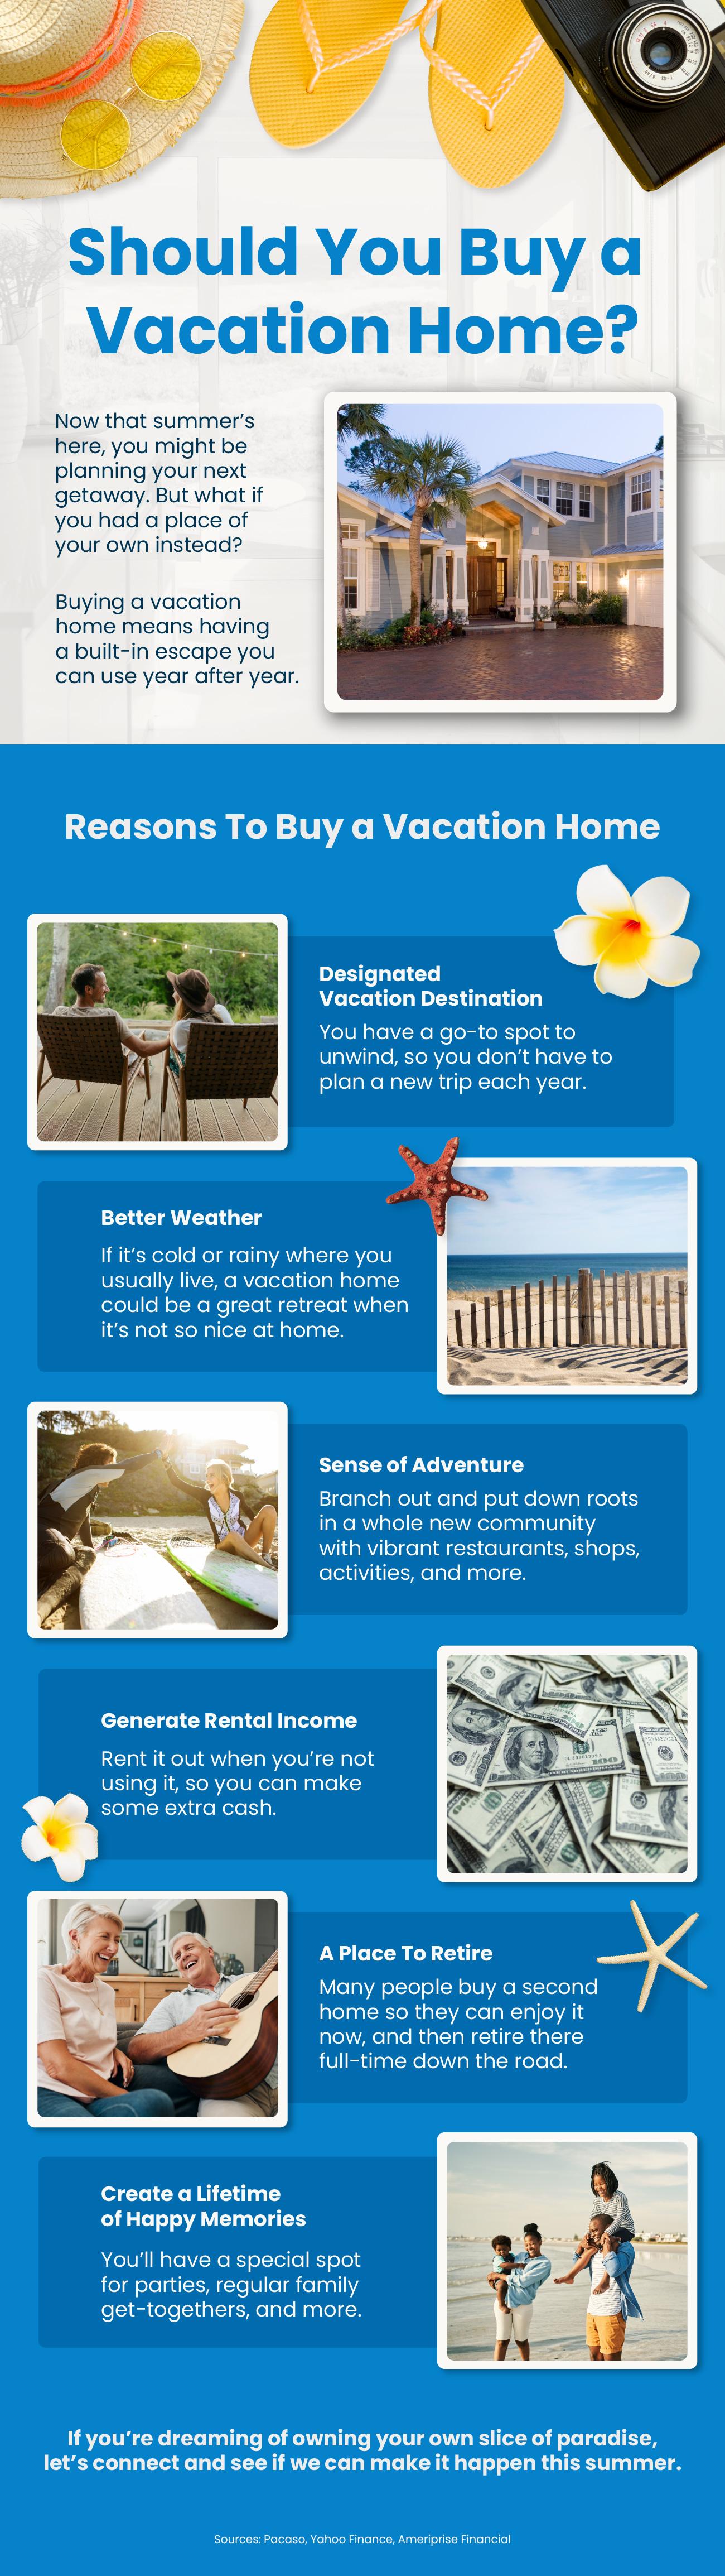
  • Now that summer’s here, you may be planning your next getaway. But what if you didn’t have to? ​
  • Buying a vacation home means having a built-in escape you can use year after year. It gives you the chance to generate rental income and have a go-to retirement destination in the future.
  • If you’re dreaming of owning your own slice of paradise, connect with an agent to see if you can make it happen this summer.​
What You Should Know About Getting a Mortgage Today

What You Should Know About Getting a Mortgage Today

What You Should Know About Getting a Mortgage Today Simplifying The Market

If you’ve been putting off buying a home because you thought getting approved would be too hard, know this: qualifying for a mortgage is starting to get a bit more achievable, but lending standards are still strong.

Lenders are making it slightly easier for well-qualified buyers to access financing, which is opening more doors for people ready to make a move.

So, if strict requirements were holding you back, this shift could be the opportunity you’ve been waiting for, without repeating the risky lending practices that led to the housing crash back in 2008.

Lenders Are Opening More Doors

Banks are offering credit to more people in an effort to boost activity in the housing market, including buyers who have lower credit scores or smaller down payments. And that means more people are getting approved for mortgages.

But it doesn’t mean we’re heading for another crash like 2008. Even with the slight easing lately, lending standards today are still much tighter than they were back then.

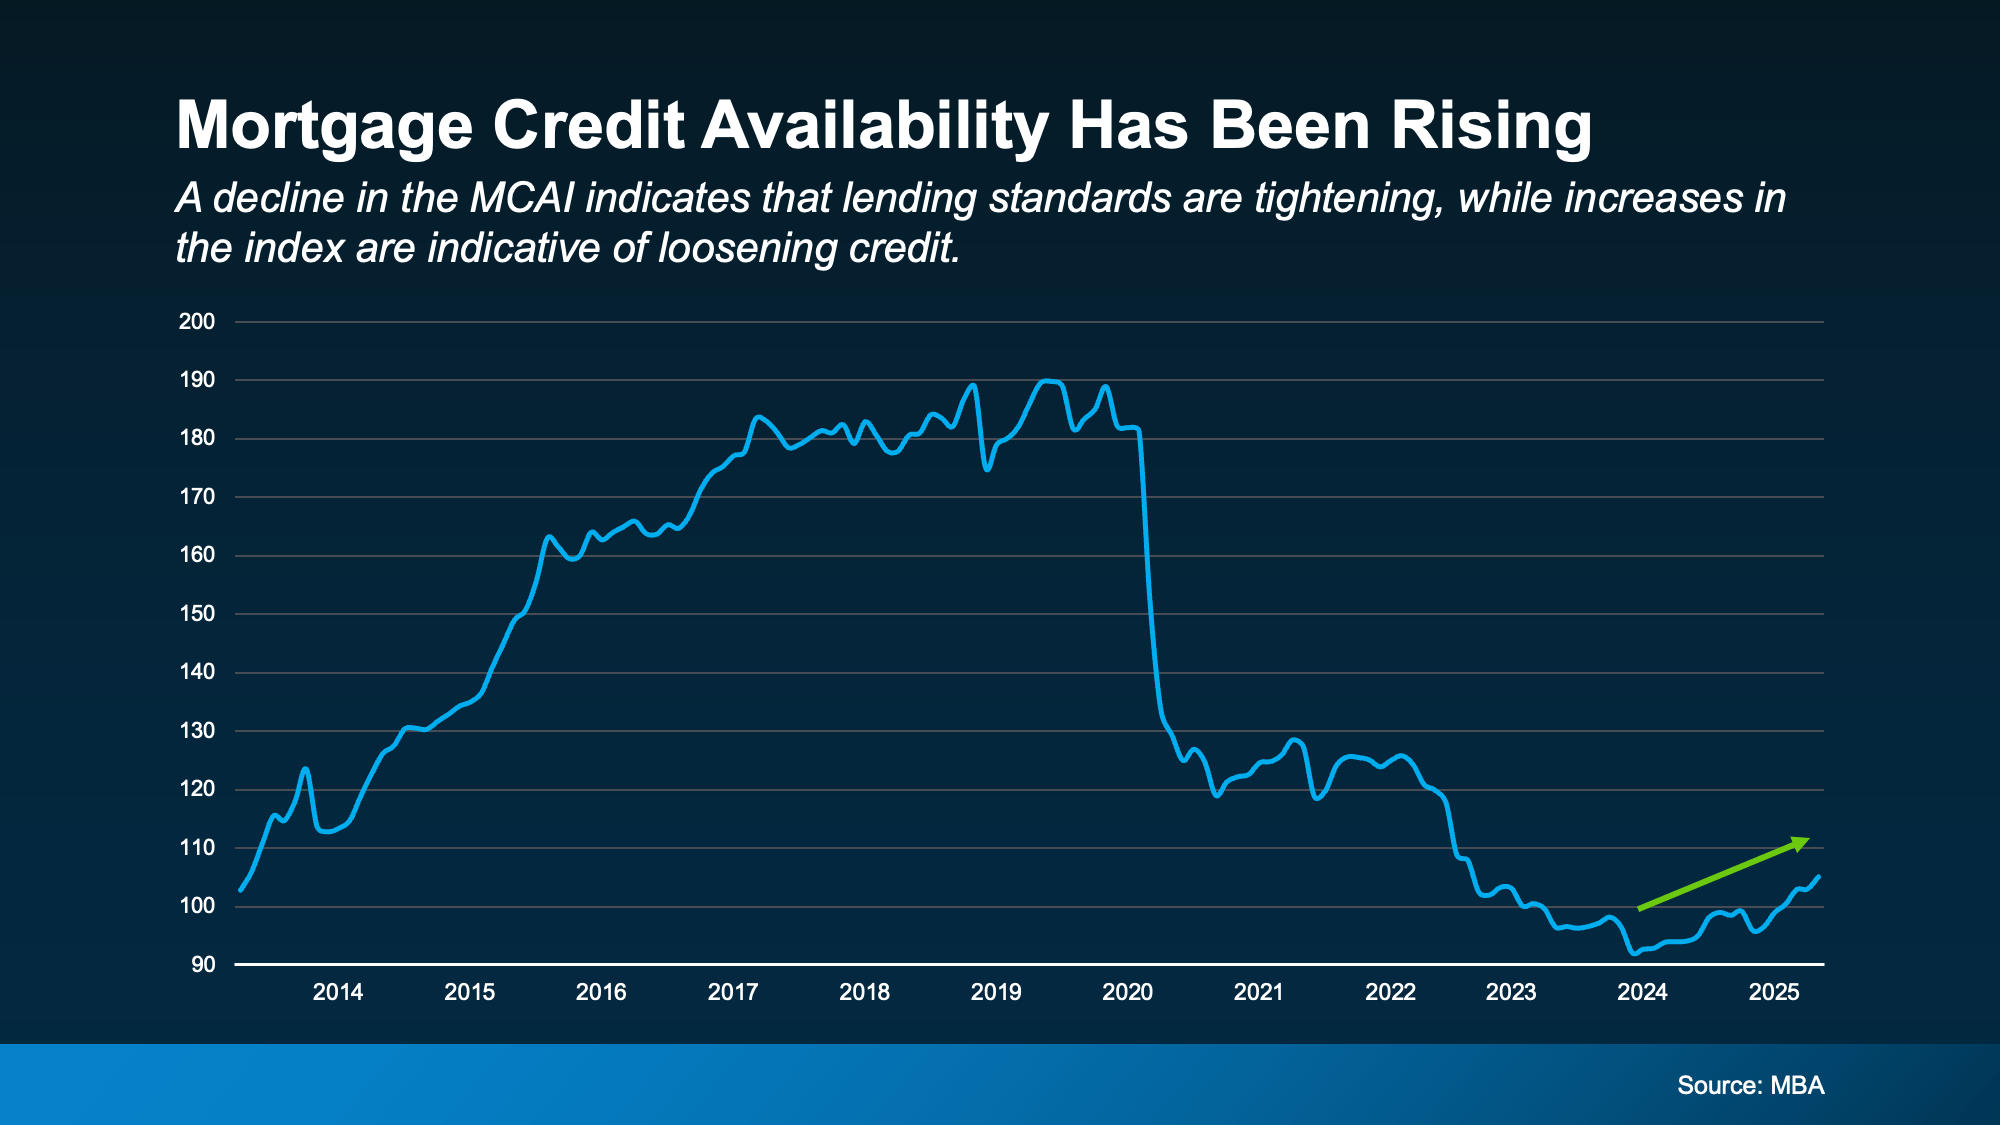
According to the Mortgage Bankers Association (MBA), the Mortgage Credit Availability Index (MCAI) has been going up. This index shows how easy or hard it is for people to get a mortgage.

When the index rises, it means banks are easing their lending standards. And in May, credit availability hit its highest point in almost three years (see graph below):

a graph showing a line graphWhy does this matter to you? It means you may now be able to qualify for a mortgage that you wouldn’t have just a few months ago. The National Association of Underwriters (NAMU) explains:

“Mortgage credit availability surged in May, reaching its highest level since August 2022. The uptick signals that lenders are increasingly willing to loosen underwriting standards, providing borrowers with greater access to financing options . . .”

But What About 2008?

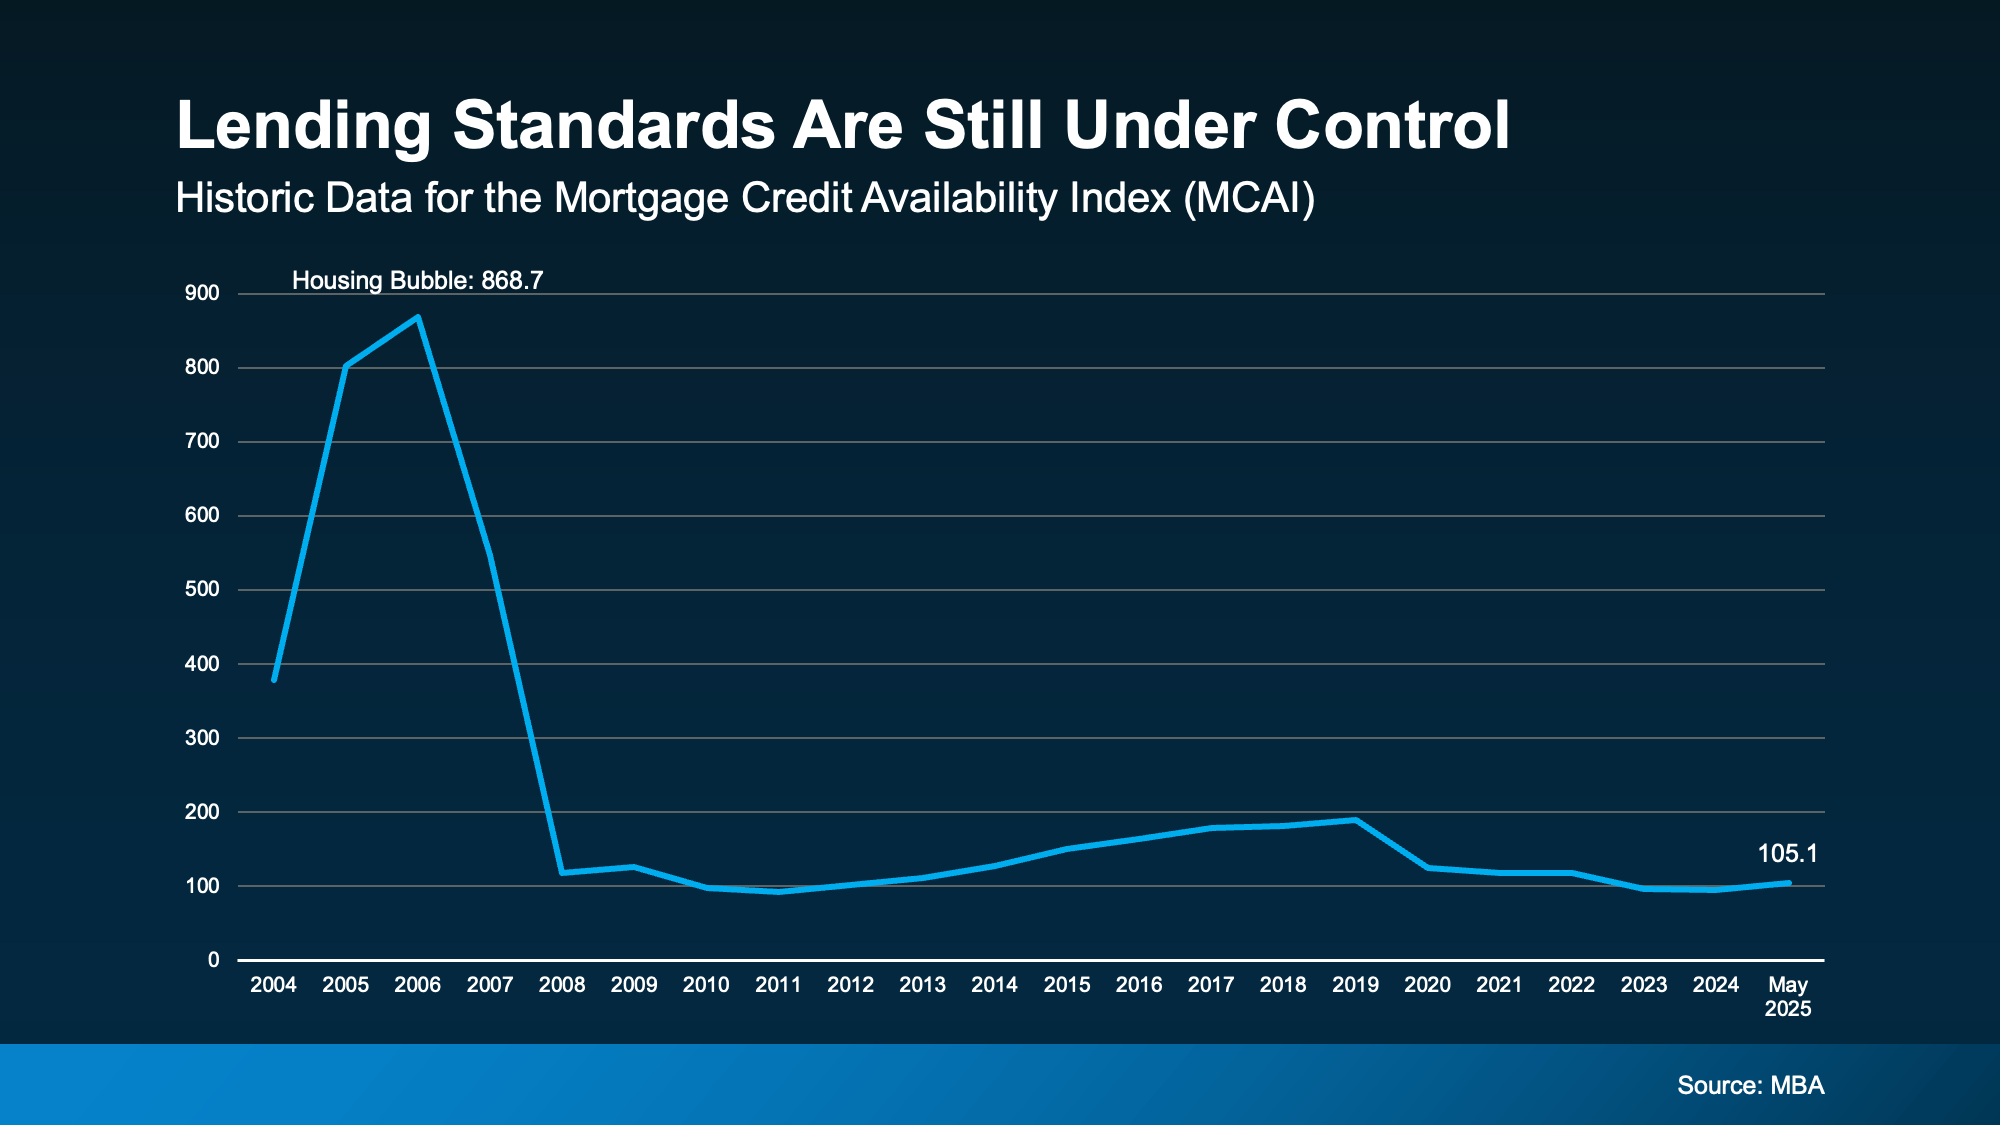
Now, you might be thinking, “Didn’t looser lending standards play a role in the 2008 housing crash?” That’s a smart question – and an important one. But here’s the difference. While credit availability is rising, lending standards are still under control.

Based on MCAI data going all the way back to 2004, today’s lending levels are still way below what they were leading up to the housing bubble (see graph below):

a graph showing the cost of a mortgageSo, increasing mortgage credit availability right now isn’t a concern. It’s just a good thing for anyone looking to buy a home. As Brett Hively, SVP of Mortgage, Finance, and Strategy at Ameris Bancorp, recently said:

“This uptick is opening the door for many borrowers to move forward with a home purchase or a refinance program.”

Bottom Line

So, if you’ve been holding back because you thought you couldn’t get approved for a mortgage, it’s worth finding out what’s possible today. Talk with a lender about your options to see if you’re ready to take that next step toward homeownership.

Why Big Investors Aren’t a Challenge for Today’s Homebuyer

Why Big Investors Aren’t a Challenge for Today’s Homebuyer

Why Big Investors Aren’t a Challenge for Today’s Homebuyer Simplifying The Market

Remember the chatter in the headlines about all the homes big institutional investors were buying? If you were thinking about buying a home yourself, you may have wondered how you’d ever be able to compete with that. Here’s the thing. That’s not the challenge so many people think it is – especially right now.

Let’s break down what’s really going on and why the recent shift in the approach investors are taking could tip the scales in your favor.

Large Investors Are Pulling Back

The truth is institutional investors never represented as big a share of the housing market as people think. And now, they’re backing off even more.

Today, big real estate investors aren’t buying as many homes. In fact, they’re actually selling more than they’re buying.

According to data from Parcl Labs, 6 out of 8 of the largest institutional single-family rental investment companies in America sold more homes than they bought in the second quarter of 2025 (see graph below):

a graph of sales and purchase

And here’s the stat that really puts it in perspective. According to Dominion Financial, for every home being bought by big investors, about 1.75 are being sold.

What’s Causing Big Investors To Change Course?

The reason institutional investors aren’t buying as many homes now compared to recent years is actually pretty simple. It’s because home values aren’t rising as fast as they were a few years ago, but the costs associated with rental maintenance are.

Since most institutional investors buy homes to rent them out, those higher costs eat into their margins. Remember, to investors, homebuying is a business.

But you’re not buying a home just for this year or next. You’re buying a place to build a life, and that’s a long-term play.

Historically, home values tend to rise over time. So, while investors may be sidelined by what’s happening right now, you’re in a different position entirely. You have the chance to buy while competition is lower and benefit from potential long-term price appreciation – something most investors are choosing not to wait for as they focus on shorter-term returns.

What Does All This Mean for You?

According to a recent survey, about 55% of real estate investors have no plans to grow their rental portfolios now or in the near future. With big investors stepping back, that means less competition from deep-pocketed buyers. And since they’re adding to today’s for-sale inventory, it also creates more options for you.

Bottom Line

If you’ve been holding off on buying, now might be the time to take another look. Connect with a local real estate agent so you can get expert guidance on what’s available and what might be a good fit for you.

What kind of home would you be excited to make yours this year?

Multi-Generational Homebuying Hit a Record High – Here’s Why

Multi-Generational Homebuying Hit a Record High – Here’s Why

Multi-Generational Homebuying Hit a Record High – Here’s Why Simplifying The Market

Multi-generational living is on the rise. According to the National Association of Realtors (NAR), 17% of homebuyers purchase a home to share with parents, adult children, or extended family. That’s the highest share ever recorded by NAR (see graph below):

a graph of sales growthAnd what’s behind the increase? Affordability. NAR explains:

“In 2024, a notable 36% of homebuyers cited “cost savings” as the primary reason for purchasing a multigenerational home—a significant increase from just 15% in 2015.”

In the past, caregiving was the leading motivator – especially for those looking to support aging parents. And while that’s still important, affordability is now the #1 motivator. And with current market conditions, that’s not really a surprise.

Pooling Resources Can Help Make Homeownership Possible

With today’s home prices and mortgage rates, it can be hard for people to afford a home on their own. That’s why more families are teaming up and pooling their resources.

By combining incomes and sharing expenses like the mortgage, utility bills, and more, multi-generational living offers a way to overcome financial challenges that might otherwise put homeownership out of reach. As Rick Sharga, Founder and CEO at CJ Patrick Company, explains:

“There are a few ways to improve affordability, at least marginally. . . purchase a property with a family member — there are a growing number of multi-generational households across the country today, and affordability is one of the reasons for this.”

But this strategy doesn’t just help with affordability. It may even allow you to get a larger home than you’d qualify for on your own and that gives everyone a bit more breathing room. As Chris Berk, VP of Mortgage Insights at Veterans United, explains:

“Multigenerational homes are more than a trend: They are a meaningful solution for families looking to care for one another while making the most of their homebuying power.”

And momentum may be growing. Nearly 3 in 10 (28%) of homebuyers say they’re planning to purchase a multi-generational home.

Maybe it’s a solution that would make sense for you too. The best way to find out? Talk to a local real estate agent who can help you decide if this option would work for you.

Bottom Line

If your budget feels tight, buying a multi-generational home could be a smart solution. 

Would you ever consider buying a home with a family member? Why or why not? 

Connect with an agent to talk through your options.

Think It’s Better To Wait for a Recession Before You Move? Think Again.

Think It’s Better To Wait for a Recession Before You Move? Think Again.

Think It’s Better To Wait for a Recession Before You Move? Think Again. Simplifying The Market

Fear of a recession is back in the headlines. And if you’re thinking about buying or selling sometime soon, that may leave you wondering if you should reconsider the timing of your move.

A recent survey by John Burns Research and Consulting (JBREC) and Keeping Current Matters (KCM) shows 68% of people are delaying plans to buy or sell due to economic uncertainty.

But it may not be for the reason you think. Not everyone is holding off because they’re worried. Some buyers are waiting because they’re hopeful. According to Realtor.com:

“In 2025Q1, 3 in 10 (29.8% of) surveyed homebuyers said a recession would make them at least somewhat more likely to purchase a home . . . This reflects a common dynamic where some buyers see a downturn as an opportunity. If the economy enters a recession, the Federal Reserve may respond by lowering interest rates to stimulate activity, potentially putting downward pressure on mortgage rates and easing affordability concerns. As a result, buyers—especially those with limited down payments—might view a recession as a more favorable time to enter the market.”

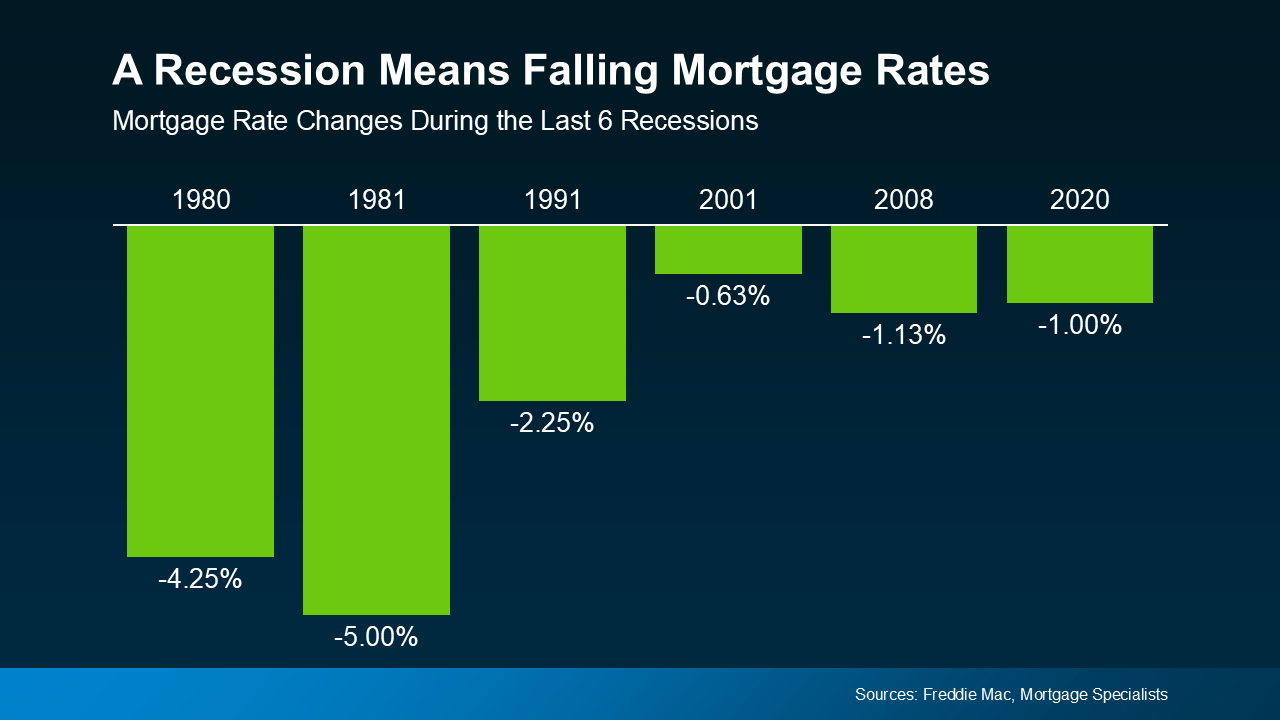
And there’s some truth to the idea that a recession could bring about lower mortgage rates. History shows mortgage rates usually drop during economic slowdowns. That’s not guaranteed – but it is a common pattern. Looking at data from the last six recessions, you can see mortgage rates fell each time (see graph below): 

a graph of a graph showing the rise of mortgage ratesBut here’s what those buyers may not be considering. Many of those hopeful buyers are assuming something else will happen too – that home prices will drop. And that’s where history tells a different story.

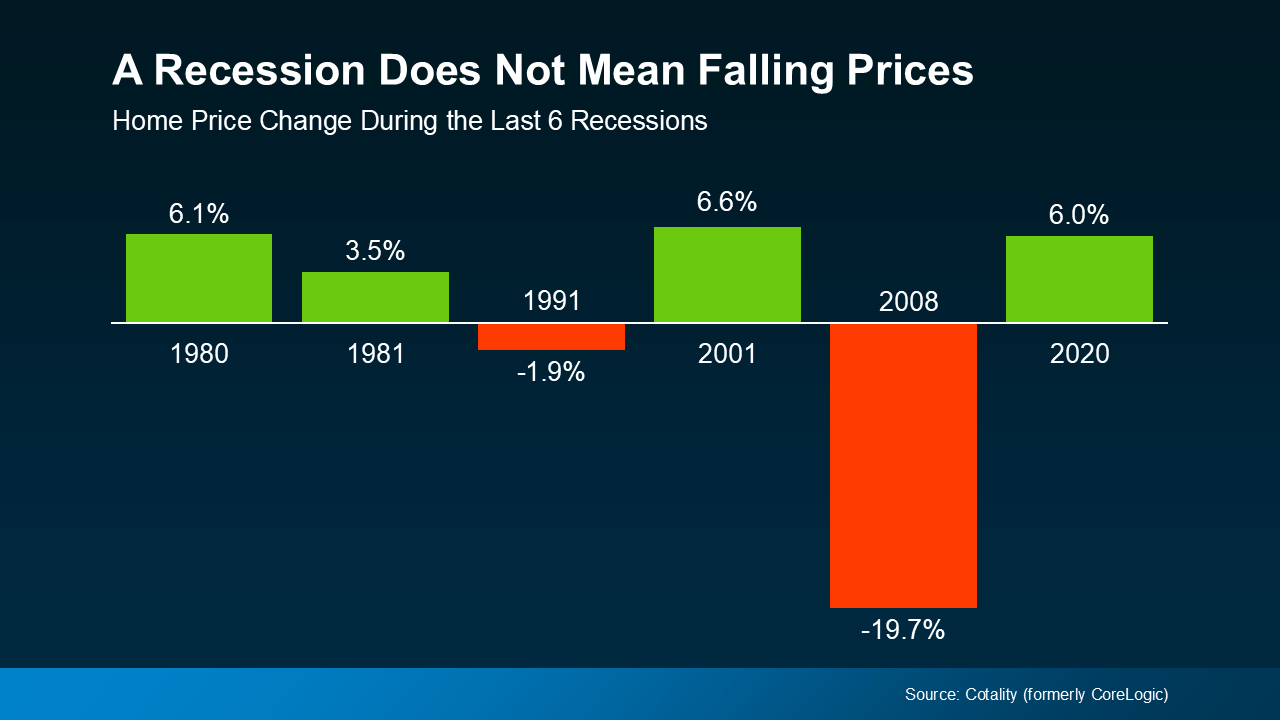
According to data from Cotality (formerly CoreLogic), home prices went up in four of the last six recessions (see graph below)

So, while many people think that if a recession hits, home prices will fall like they did in 2008, that was an exception, not the rule. It was the only time the market saw such a steep drop in prices. And it hasn’t happened since, mainly because there’s still a long-standing inventory deficit, even as the number of homes on the market is rising.
Since prices tend to stay on whatever path they’re already on, know this: prices are still holding steady or rising in most metros, although at a much slower pace. So, a big drop isn’t likely. As Robert Frick, Corporate Economist with Navy Federal Credit Union, explains:

“Hopes that an economic slowdown will depress housing prices are wishful thinking at this point . . .”

Bottom Line

If you’ve been waiting for a recession to make your move, it’s important to understand what really happens during one – and what likely won’t. Lower mortgage rates could be on the table. But lower home prices? That’s far less likely.

Don’t wait for a market that may never come. If you’re thinking about buying or selling, connect with an agent to talk through what today’s economy really means for you – and make a smart plan that works in your favor, regardless of what the headlines say.

Pin It on Pinterest